Golden Shield Life Insurance evaluates final expense coverage on two things: what the costs actually are, and how clearly a company explains its underwriting. The National Funeral Directors Association reports a national median of $6,280 for a funeral with cremation and $8,300 for a funeral with viewing and burial. Neither figure includes a cemetery plot or a headstone, and neither accounts for what often arrives alongside a death, including unpaid medical bills, legal fees, and outstanding personal debt.
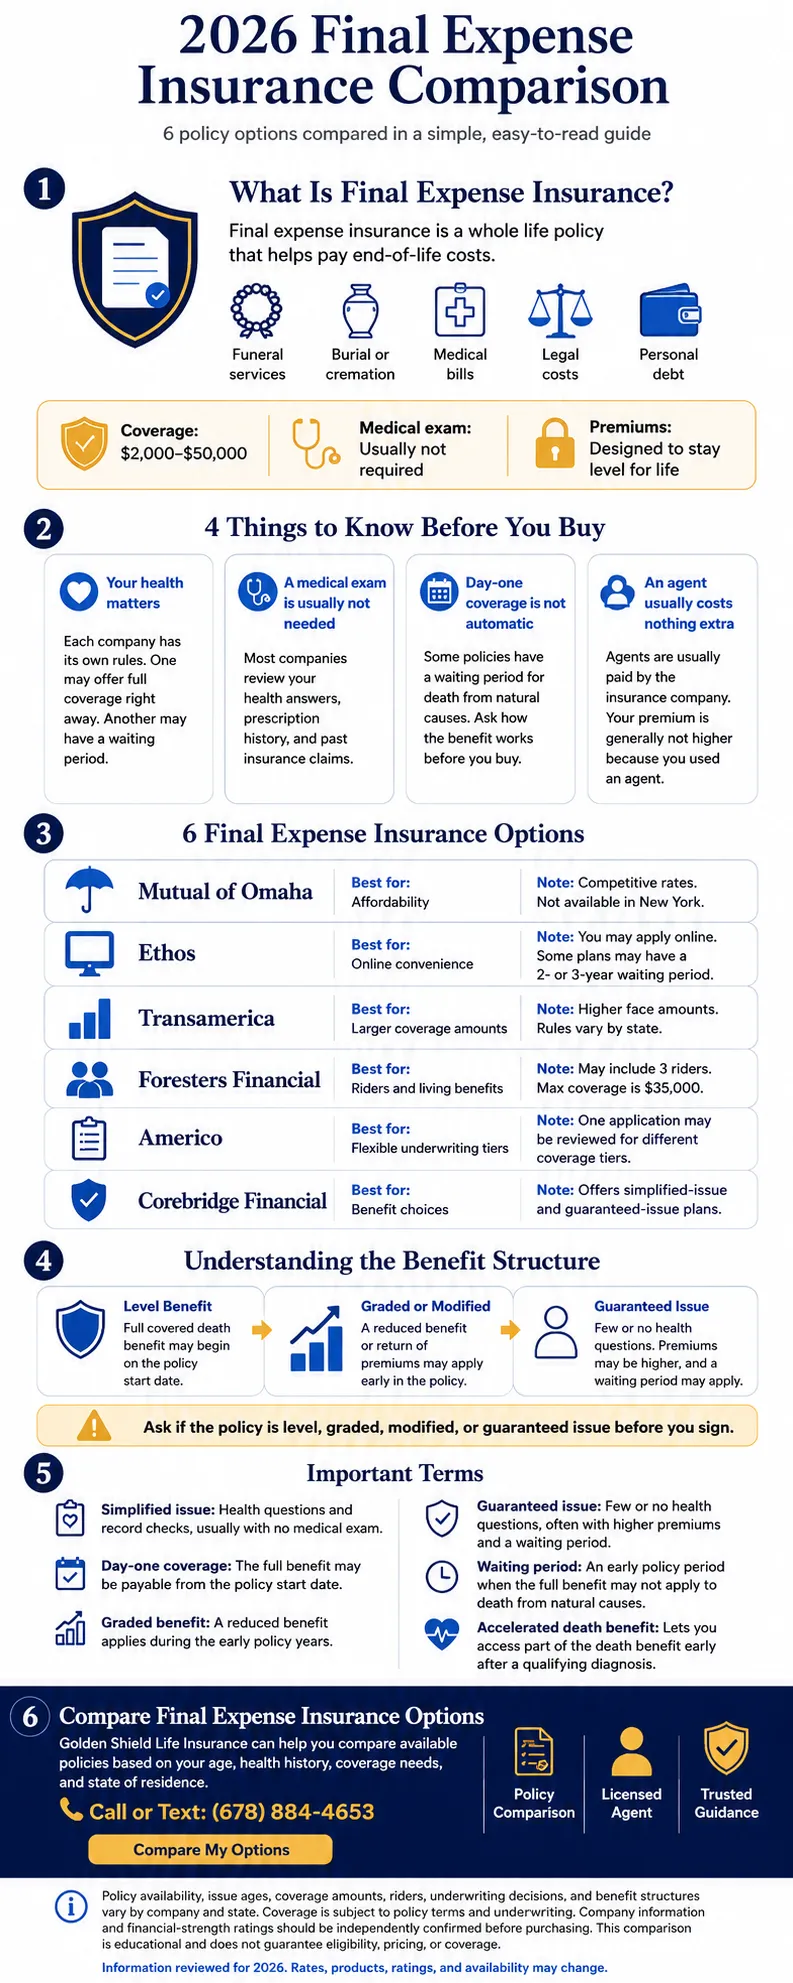
Final expense insurance, also called burial insurance, is a form of permanent whole life insurance meant to cover that gap. These policies generally pay a cash death benefit between $2,000 and $50,000, use premiums designed to stay level for the life of the policy, and usually do not require a medical exam.
To build the six picks below, Golden Shield Life Insurance reviewed each company on whether the full benefit is payable from day one, how the application runs, how underwriting treats pre-existing conditions such as diabetes, COPD, and a cardiac history, and financial strength ratings from AM Best and the other agencies. The full method is below, and every pick names a drawback.
Four Things Worth Knowing First
- 1The difference is rarely the brand. It is whether that company was the right fit for the answers on your application, because the same answers can produce different offers at different companies.
- 2A medical exam is usually not required. Most final expense companies use a short set of health questions along with a check of prescription and claims records.
- 3Day one is not automatic. One company may pay the full amount immediately where the next limits the first two years, which is the single most important thing to confirm in writing.
- 4A licensed agent costs you nothing extra. The insurance company sets your rate and pays the agent when a policy is placed, so your premium is generally the same either way.
How Golden Shield Life Insurance Chose These Six
Golden Shield Life Insurance is an independent agency in Atlanta that submits these applications and sees what comes back. These six picks are based on that casework plus published carrier materials. The factors weighed were which applicants each company tends to approve, how the application runs, what is payable during the early policy years, which riders come included at no additional premium, financial strength ratings from AM Best and the other agencies, and state availability.
Six companies, six different jobs. No company is best at all of them. A company that offers strong terms to a 62-year-old with controlled diabetes may decline a 78-year-old on oxygen, which is why naming a single winner would be useless to you.
Price alone is not the tiebreaker. The cheapest offer is often the one with the most limited early benefit, which means the lowest premium and the highest chance your family receives less than you expected.
Pick 1 of 6
Best for Affordability: Mutual of Omaha
- Plans
- Living Promise level benefit, Living Promise graded benefit, and Guaranteed Whole Life
- Issue ages
- 45 to 85 on Guaranteed Whole Life
- Coverage
- Up to $25,000 on Guaranteed Whole Life
- Underwriting
- Simplified issue on Living Promise, no health questions on Guaranteed Whole Life. No medical exam on any of the three.
- On price
- Mutual of Omaha was tied for the lowest average rate in MoneyGeek's 2026 rate analysis. Averages are not a quote and your own rate depends on your age, health, and state.
- Financial strength
- United of Omaha Life Insurance Company holds A+ from AM Best, A+ from Standard and Poor's, and A1 from Moody's, with a stable outlook on all three. AM Best places A+ in its Superior category, one band above the Excellent category where the other five picks sit.
- Claims record
- Mutual of Omaha publishes a monthly claims table, which almost no insurer does. Over the twelve months through May 2026, between 81.0 and 89.2 percent of eligible guaranteed issue claims were paid within one day of receiving all required documentation.
See the details
Pros
- Tied for the lowest average rate in an independent 2026 analysis
- Highest rated of these six picks, and the only one in AM Best's Superior category
- Three Mutual of Omaha plans span simplified issue through no health questions
- Publishes a monthly claims record any consumer can read
Cons
- The published claims record covers Guaranteed Whole Life only, not Living Promise
- $25,000 ceiling on Guaranteed Whole Life
- United of Omaha does not write business in New York
- The Living Promise graded benefit form pays less than the full amount for death from natural causes in the early years
Who is Mutual of Omaha best for? Someone on a fixed income who wants the lowest sustainable premium without giving up options, and who does not yet know whether they will clear the health questions.
Standout benefit. A low rate that does not box you in. If the Mutual of Omaha plan that pays the full amount from day one is out of reach, the next option is generally down the hall rather than at a new company with a new application and a new set of questions. Golden Shield Life Insurance can move you between the three in one sitting.
Pick 2 of 6
Best for Convenience: Ethos

- How it works
- Online from start to finish. Quote, apply, and pay without a phone call or an appointment.
- Underwriting
- Health questions online. No medical exam.
- Who issues the policy
- Ethos is an agency, not an insurer. Partner insurance companies underwrite the policy and pay the claim.
- Availability
- Ethos does not offer coverage in New York
- Included
- Will and estate planning tools come with most Ethos policies. Issue ages and coverage amounts vary by plan and by partner insurer and change regularly, so confirm them on the quote itself rather than relying on any published figure.
See the details
Pros
- Nobody comes to your house, and nobody calls you back unless you ask
- You can do the whole thing at your kitchen table at two in the morning
- Ethos shows a real price before you hand over a phone number
- Free will and estate planning tools with most policies
Cons
- Ethos prices generally run above what a fully reviewed policy costs a healthy applicant
- On the guaranteed acceptance plan the early limited period can run two to three years, longer than the two years common elsewhere
- Ethos does not pay the claim. A partner insurer does, and that is who your family deals with
- Fewer plan choices, and nobody reading the benefit schedule with you
Who is Ethos best for? Someone who would rather not sit across from an agent at all, and would rather handle this on their own time.
Standout benefit. Nobody in your living room. That sounds small until you have had four agents call you in a week. With Ethos you look at real prices, decide on your own schedule, and finish it or close the laptop. Golden Shield Life Insurance is here if you want a second opinion, and not if you do not.
There is also a result on health history worth mentioning. In Golden Shield Life Insurance's own casework, Ethos has approved applicants with a cardiac history or a prior stroke on terms other companies would not offer. That is what we have seen placing these cases. It is not a promise, because the issuing insurer makes the decision and yours may come back differently.
One thing worth doing before you check out. Read what the Ethos plan pays if death comes from natural causes during the first two years. That figure decides whether the policy does what you think it does, and on a self-service purchase nobody is going to read it to you.
Pick 3 of 6
Best for Larger Face Value: Transamerica
- Plans
- An immediate benefit plan and a graded benefit plan
- Underwriting
- Health questions. No medical exam.
- Face amounts
- Reach higher than most final expense products. Amounts and issue ages shift by age band, so Golden Shield Life Insurance confirms them for your age at the time of quoting.
- Included
- A funeral concierge service is available on some Transamerica plans
- Graded benefit terms
- On the Transamerica graded plan, death from a cause other than an accident during the first two policy years pays 110 percent of the premiums paid rather than the face amount. Accidental death is generally paid at the face amount from day one. After two years the face amount is payable whatever the cause.
See the details
Pros
- Transamerica goes well past the $25,000 to $35,000 ceiling most final expense products stop at
- Often competitive on applicants other companies price harshly
- Frequently workable for tobacco users
- Both an immediate benefit and a graded benefit path
Cons
- Rarely the lowest price for someone in good health
- Transamerica cannot be bought online. It runs through a licensed agent
- Availability and issue ages vary by state, and New York terms differ
- The maximum face amount is not the same at every age, so the headline figure may not apply to you
Who is Transamerica best for? Someone who needs a larger face amount than the category usually allows, because the funeral is only part of what has to be paid, or someone who has already been priced badly somewhere else.
Standout benefit. Headroom. If $25,000 will not cover the funeral plus the remaining medical balances plus what is left on the car, Transamerica is the pick that can go higher. It is also the one Golden Shield Life Insurance reaches for when tobacco use or a health history has made the other companies expensive.
Neighbors and Families
Six Companies Compete. One Person Does the Comparing.
The companies on this page want your business. Here is what it has been like working with the person who compares them.
Testimonials reflect the experience of individual clients of Golden Shield Life Insurance and are not a promise of any particular result. Coverage, approval, and rates vary by age, health history, state, and company underwriting.
Pick 4 of 6
Best for Riders and Living Benefits: Foresters Financial
- Plan
- PlanRight Whole Life
- Issue ages
- 50 to 85
- Coverage
- $5,000 to $35,000
- Underwriting
- Simplified issue. No bloodwork, no saliva sample, no paramedical visit. Insurability still depends on your answers plus underwriting review.
- Included at no additional premium
- An accelerated death benefit rider that pays early on a terminal illness diagnosis. A common carrier accidental death rider that pays an additional amount for accidental death while riding as a fare-paying passenger on a plane, bus, or train. A family health benefit rider covering certain family health expenses arising from a hurricane, tornado, or earthquake. Availability and terms vary by state.
- Duration and cash value
- Foresters Financial PlanRight coverage runs to age 121 with level premiums and cash value set in the contract. A policy loan and any loan interest reduce the death benefit.
See the details
Pros
- Three riders included rather than sold separately
- Foresters Financial PlanRight coverage runs to age 121, so it does not expire on you
- Health questions only, no bloodwork and no nurse visit
- Builds cash value you can borrow against
Cons
- The $35,000 maximum is the lowest ceiling of these six picks
- Foresters Financial PlanRight starts at age 50, so it is not an option in your forties
- Borrowing against the policy reduces what your family receives
- Which riders you get depends on your state, and PlanRight is not sold in Oregon
Who is Foresters Financial best for? Someone who wants $35,000 or less and would rather have the added benefits built into the coverage than pay for them one at a time.
Standout benefit. What comes attached. Most companies charge for an early payout on a terminal diagnosis. On Foresters Financial PlanRight it is part of the coverage, along with an additional amount for an accident on a plane, bus, or train, and help with family health costs after a natural disaster. None of it adds to the premium.
Pick 5 of 6
Best for Flexibility: Americo
- Plan family
- Ultra Protector Series, written in tiers
- Underwriting
- Health questions plus a check of prescription and claims records. No medical exam.
- Financial strength
- Americo Financial Life and Annuity Insurance Company holds A, Excellent, from AM Best as of January 2026, which Americo describes as third of fifteen rating categories
- Availability
- Authorized in the District of Columbia and all states except New York
- How the Americo tiers work
- Rather than a single yes or no, the Ultra Protector Series is designed to place an applicant at the level their answers support. That generally means one application instead of four, and a clearer picture of what is actually available to you. Premiums on these Americo plans are designed not to increase, and coverage is not cancelled because you have aged or your health has changed, as long as required premiums are paid.
See the details
Pros
- Several tiers inside one Americo product family, so one application finds your level
- Coverage is not cancelled because you got older or your health changed, as long as you pay
- Premiums are designed not to increase
- Available in every state except New York
Cons
- The tier you want and the tier Americo offers may not be the same
- Riders are thin on the graded tiers and often unavailable
- Americo does not write business in New York
- Face amounts top out lower than Transamerica
Who is Americo best for? Someone managing a condition that has caused problems with other companies, whether that is diabetes, COPD, or a cardiac history, who would rather find out where they land than apply at four companies and wait.
Standout benefit. One application, several possible answers. The Americo tier structure turns a yes-or-no question into a where question, which usually means fewer applications and less waiting. Golden Shield Life Insurance will tell you which tier came back and what it pays before you sign anything.
Pick 6 of 6
Best for Choosing Your Benefit Structure: Corebridge Financial
- Plans
- Simplified issue and guaranteed issue versions
- Underwriting
- Health questions on the simplified issue version, few or none on the guaranteed issue version. No medical exam.
- Structures
- One version limits what is payable for natural causes during the first two policy years. Another pays the full amount in all policy years for applicants who qualify.
- Riders
- Accelerated death benefit riders may be included at no additional premium, with qualification and any reduction controlled by the policy
- Financial strength, with the outlooks
- American General Life Insurance Company holds A+ from Standard and Poor's, A2 from Moody's, A from AM Best, and A+ from Fitch, last updated April 8, 2026. As of that date, Standard and Poor's had the company on CreditWatch Negative and AM Best had it Under Review with Developing Implications. Moody's was Stable and Fitch was Positive. An outlook is not a downgrade and Under Review can move in either direction. It is published here because four A grades with two review flags removed is not the whole picture.
See the details
Pros
- You choose the Corebridge benefit structure instead of discovering it later
- Rated by all four major agencies
- Accelerated death benefit riders often included at no additional premium
- Both a simplified issue and a guaranteed issue route
Cons
- Two of the four rating agencies had American General Life on watch or under review as of April 2026
- Not every applicant is offered the version that pays the full amount from the start
- The limited version pays only a return of premiums during the early period
- Availability varies by state
Who is Corebridge Financial best for? Someone who wants to see a full benefit version and a limited early version side by side from the same company before deciding which one to buy.
Standout benefit. The choice happens before you sign. Golden Shield Life Insurance puts both Corebridge structures in front of you, reads the early policy years out loud, and lets you pick. That is the opposite of finding out in year one.
Glossary: Words You Will See on a Final Expense Policy
- Simplified issue
- Underwriting based on a short set of health questions plus a check of your prescription and claims records, usually with no medical exam. Approval depends on your answers. This is the most common way a final expense policy is issued, and it generally costs less than guaranteed issue.
- Guaranteed issue
- A plan with few or no health questions, written for people whose health rules out the other options. Age limits, state availability, and benefit limits still apply, and the full amount is usually limited for death from natural causes during an early period. It generally costs more per dollar of coverage.
- Day-one coverage, also called a level benefit
- A plan where the full death benefit is payable from the policy's effective date for a covered death. Where you qualify for it, it is generally the stronger option.
- Waiting period
- The early stretch of a policy, commonly the first two years, during which the full death benefit may not yet be payable for death from natural causes. Accidental death is often paid in full from the start. Not every final expense policy has one. Ask which kind you are being offered, and ask to see it in writing.
- Graded benefit
- A structure that pays a reduced portion of the death benefit for death from natural causes during the early period, then the full amount afterward. Accidental death is often paid in full from day one.
- Modified benefit, or return of premium
- A structure that returns the premiums you paid, often with stated interest, for death from natural causes during the early period rather than paying the full amount. Transamerica's graded plan returns 110 percent of premiums paid during the first two years.
- Accelerated death benefit, also called a living benefit
- A rider that pays part of the death benefit early when a qualifying condition such as a terminal illness is met. Using it reduces what your beneficiaries receive and reduces any cash value. It is not long-term care insurance.
- Prescription and claims history check
- A review of your medication and insurance claims records that most final expense companies run in place of a medical exam. It is why answering the health questions completely matters, because your answers are checked against those records.
- Contestability period
- Usually the first two years after a policy is issued. During that window the company may review your application answers before paying a claim. This is separate from a waiting period, and it can apply even on a plan that pays in full from day one.
More terms, including cash value, beneficiary, grace period, lapse, and the free look period, are defined on the final expense insurance guide.
Disclosures, Issuing Companies, and Product Details
Editorial and compensation disclosure
These are Golden Shield Life Insurance's editorial selections for 2026, reviewed in July 2026. They are not a universal ranking and not a claim that any company will offer you the lowest premium or the most suitable policy. Golden Shield Life Insurance holds appointments or business relationships with the companies named here and with Ethos, and is compensated by the issuing company when a policy is placed. That compensation does not increase your premium, because the issuing company sets the rate. Golden Shield Life Insurance will review these selections as products, ratings, state approvals, and underwriting guidelines change, and before publishing any 2027 selections.
Golden Shield Life Insurance
Golden Shield Life Insurance is an independent life insurance agency and brokerage in Atlanta, Georgia. It is not an insurance company and does not underwrite, issue, or administer policies. Each insurance company makes its own underwriting decisions and pays its own claims under the terms of its contracts. Applying does not mean you will be approved. Georgia Agency License 242517, NPN 21216745.
Testimonials
Client comments shown on this page reflect the experience of individual clients of Golden Shield Life Insurance. They are not a promise or an indication of any particular result. Coverage, approval, and rates vary by age, health history, state of residence, and company underwriting. No compensation was provided in exchange for these comments.
Our own casework
Where this page describes what Golden Shield Life Insurance has seen placing applications, that reflects the experience of this agency with its own clients. It is not a statistical sample, not a prediction, and not an indication of what any company will offer you. Underwriting outcomes depend on your age, your health history, your state of residence, and each company's own rules at the time you apply.
Rate comparisons cited
Statements about average rates refer to MoneyGeek's 2026 final expense rate analysis, which compares published market averages rather than quotes. Averages are not an offer of coverage and are not the rate any individual will be charged. Your own premium depends on your age, health history, tobacco use, state, coverage amount, and the company reviewing your application.
Issuing companies
Mutual of Omaha. Life insurance underwritten by United of Omaha Life Insurance Company, Mutual of Omaha Plaza, Omaha, NE 68175. United of Omaha is licensed nationwide except in New York and does not solicit business in New York. In New York, Companion Life Insurance Company, Melville, NY 11747 underwrites. Guaranteed Whole Life (DTC) Policy Form ICC18L198P or state equivalent. Living Promise Level Benefit Policy Form ICC12L080P or state equivalent, Graded Benefit Policy Form ICC12L081P or state equivalent.
Ethos. Ethos Technologies Inc. is an insurance agency, not an insurance company. Policies are issued and claims are paid by partner insurance companies. Ethos does not offer coverage in New York.
Transamerica. Products underwritten by Transamerica Life Insurance Company, Cedar Rapids, IA. In New York, Transamerica Financial Life Insurance Company.
Foresters Financial. Foresters Financial and Foresters are trade names and trademarks of The Independent Order of Foresters, a fraternal benefit society, 789 Don Mills Road, Toronto, Canada M3C 1T9, and its subsidiaries. PlanRight Whole Life is issued as a certificate. Not available in Oregon.
Americo. Products underwritten by Americo Financial Life and Annuity Insurance Company, Kansas City, MO. Authorized in the District of Columbia and all states except New York. Americo Life, Inc. is a holding company and is not responsible for the financial condition or contractual obligations of its affiliate insurance companies.
Corebridge Financial. Products underwritten by American General Life Insurance Company. In New York, The United States Life Insurance Company in the City of New York.
Financial strength ratings
A financial strength rating is a rating agency's opinion of an insurer's ability to meet its ongoing obligations. It is not a warranty, not a recommendation of any specific policy form, contract, rate, or claim practice, and not a promise about your claim. AM Best groups A++ and A+ in its Superior category, A and A- in Excellent, and B++ and B+ in Good. All guarantees are subject to the financial strength and claims paying ability of the issuing company, and each company is responsible for its own financial and contractual obligations. Ratings and outlooks change after publication. Verify any insurer at ambest.com.
Claims data cited
The Mutual of Omaha claims figures reflect 12 months of rolling data for guaranteed issue life insurance policies of $2,000 to $25,000, counted after all required documentation is received, and excluding claims made within 24 months from the policy issue date. They are a published record, not a promise about the timing of any claim. Figures published by Mutual of Omaha at mutualofomaha.com.
Cost figures cited
The $6,280 and $8,300 figures are national median costs for a funeral with cremation and a funeral with viewing and burial, reported by the National Funeral Directors Association at nfda.org/news/statistics. Neither includes a cemetery plot or a headstone. Coverage ranges shown are general market ranges, not an offer of coverage, and vary by company, age, and state.
Availability, eligibility, and exclusions
Coverage amounts, issue ages, premiums, riders, benefit schedules, and product availability vary by company, by plan, and by state, and change over time. Base plans, provisions, features, and riders may not be available in all states. All policies and riders contain limitations, exclusions, and a contestability period during which the company may review the application for material misstatements if a claim is filed. Death benefits are generally not paid if death results from suicide within an initial period after issue, commonly two years and one year in some states, in which case the company generally returns the premiums paid less any loan, loan interest, and withdrawals. The exclusions that apply to you are the ones printed in your contract and rider forms.
Graded and limited benefit plans
Graded, modified, and limited benefit plans may pay less than the full death benefit during an initial period, commonly the first two years and longer on some plans. Some return the premiums paid plus stated interest for death from natural causes during that period. Read the benefit schedule in your contract before you accept coverage.
Riders and living benefits
Riders are optional and are not available on every plan or in every state. Some are included at no additional premium and some cost extra. An accelerated death benefit reduces the death benefit left for your beneficiaries and reduces any cash value. It is not long-term care insurance. Receiving an accelerated death benefit, or holding cash value, may affect eligibility for Medicaid, Supplemental Security Income, or other need-based assistance.
This coverage and funerals
This life insurance does not specifically cover funeral goods or services and may not cover the entire cost of a funeral. The beneficiary you name may use the proceeds for any purpose, unless otherwise directed. It is not a prepaid funeral contract.
General
This page is educational and is not financial, legal, or tax advice. It is not a contract and not an offer of coverage. It is a solicitation of insurance and a licensed agent may contact you. Do not cancel an existing policy until a new policy has been issued, delivered, and reviewed. Policy loans and withdrawals reduce the death benefit and may have tax consequences. Trade names and logos are the property of their respective owners and appear here for identification only.