Critical illness insurance

Critical illness insurance provides financial support after experiencing a covered critical illness diagnosis or event. Is it worth buying?

Life Insurance Agent Near You

Golden Shield Life Insurance
Nationwide License # 21216745

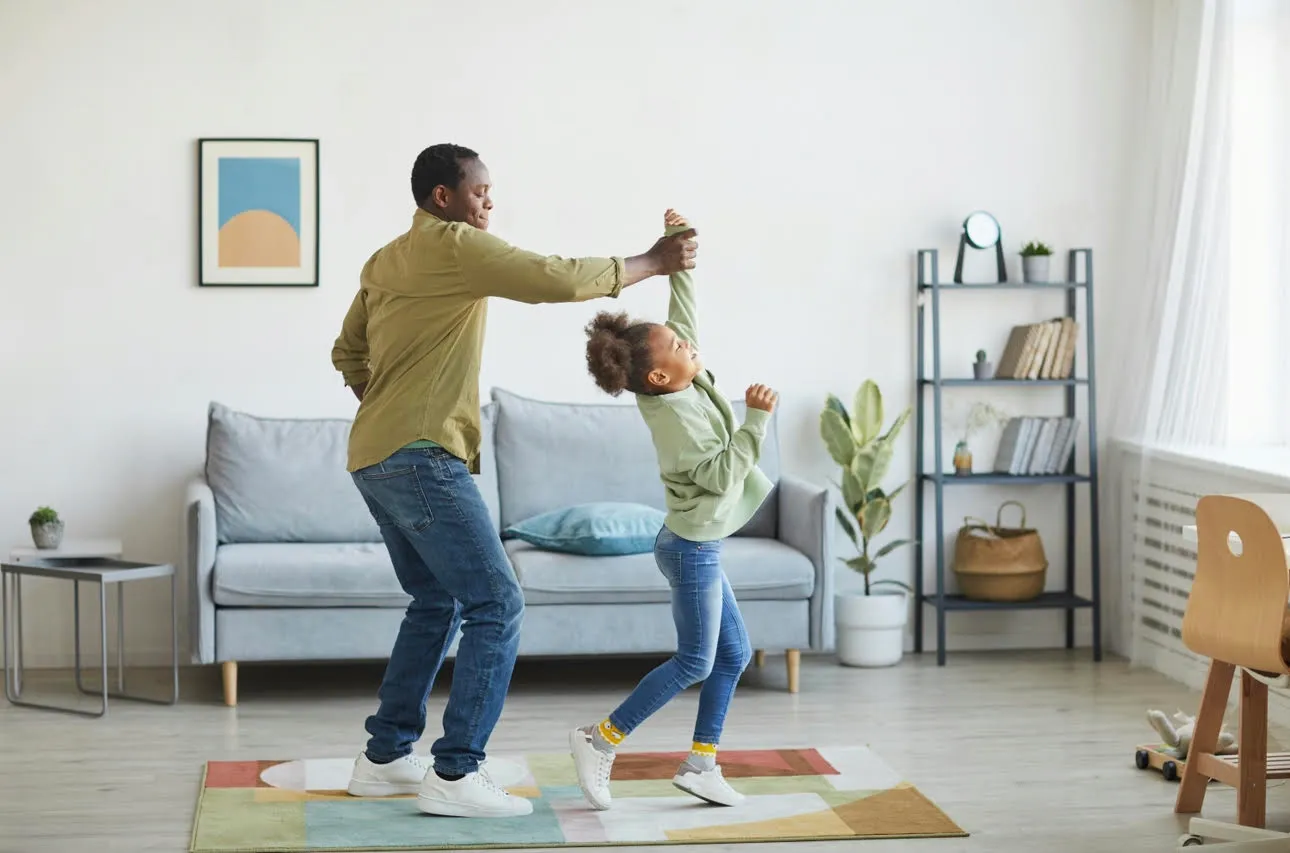
Father and young daughter dancing together at home
Ready to compare policies?Call, text or schedule an appointment.

Critical Illness Insurance Buyer’s Guide

Critical illness insurance policies can look similar until you compare their definitions, payment percentages and limitations. Before choosing a policy, review these four details:

  • Which diagnoses and procedures are covered
  • Whether each condition pays the full or a partial benefit
  • Whether benefits are available for later or recurring diagnoses
  • When coverage ends or the maximum lifetime benefit is reached

What is critical illness insurance?

Critical illness insurance is an individual policy or rider that can pay a lump-sum cash benefit directly to you after a covered diagnosis meets the policy’s requirements. The money may be used for medical or everyday expenses during recovery. It supplements but does not replace health insurance.

Covered conditions vary by policy but may include cancer, heart attack, stroke, kidney failure, major heart surgery, organ transplant, paralysis, coma, severe burns, and permanent loss of limbs, sight, hearing, or speech. Some policies also cover specified neurological conditions, including multiple sclerosis, Parkinson’s disease, Alzheimer’s disease, severe dementia, bacterial meningitis, encephalitis, and motor neuron disease.

The risk may be greater than you think. Every 40 seconds, someone in America has a heart attack, and every 40 seconds, someone has a stroke. Cancer adds approximately 5,800 new diagnoses each day. Surviving may be only the beginning. Recovery can require rehabilitation, medication, follow-up care, and time away from work. Health insurance may help with treatment, but it does not replace your paycheck or cover every mortgage payment, grocery bill, transportation cost, or caregiving expense.

Would your savings be enough?

Every 40 Seconds, Life Changes

One rotation, 40 seconds
Every 40 Seconds
Someone in America has a heart attack.
Every 40 Seconds
Someone in America has a stroke.
About 5,800 Each Day
New cancer diagnoses are expected in the United States during 2026.

We Believe Every Family Deserves a Financial Shield

You cannot control when a serious illness will happen, but you can decide how you will prepare for the financial impact. Coverage must be secured before a diagnosis meets the policy’s definition of a pre-existing condition.

Without coverage, a GoFundMe may feel like the only option left. Crowdfunding can help, but it is public and unpredictable. Not everyone who views or shares a fundraiser will donate.

Prepare while you still have the opportunity, not after the clock starts.

Explore Critical Illness Coverage

How does Critical Illness Insurance work?

  1. Step 1

    Something feels off

    You know something is wrong. You call 911, and paramedics arrive to begin emergency care.

  2. Step 2

    You arrive and receive a diagnosis

    Testing confirms a heart attack, stroke, paralysis, or another condition that may qualify under your policy.

  3. Step 3

    Submit Your Claim

    Notify Golden Shield Life Insurance and the insurance carrier. We can help you organize the requested forms and medical documentation while the carrier reviews the claim.

  4. Step 4

    The Carrier Makes Its Decision

    If the claim meets the policy’s definition of a covered condition, the carrier pays the applicable benefit directly to you.

How Can You Use a Critical Illness Benefits?

  • Keep the Mortgage or Rent Paid

  • Bring In Childcare, Caregiving, or Help at Home

  • Travel to Treatment and Follow-Up Care

  • Keep Utilities and Monthly Bills Current

  • Keep Groceries on the Table

If a covered claim is approved, the applicable benefit is paid directly to you. Benefits from an individually purchased policy paid with after-tax dollars are generally not included in taxable income. Different rules may apply to employer-paid coverage. Consult a qualified tax advisor.

What Are The Different Types of Critical Illness Insurance?

Critical illness policies are generally offered in one of two structures.

Most Popular

Term Coverage

Protection for a set number of years, often matched to a mortgage, working years, or the time children are at home.

  • Terms may be available for periods such as 10, 15, 20, or 30 years
  • Coverage ends when the term expires unless another option is provided
  • Premiums are generally lower than lifetime coverage for the same benefit amount
  • Often a fit when the need has a clear end date
Compare Term Options
Longer Lasting

Lifetime Coverage

Protection designed to stay with you rather than expire on a set date.

  • Remains in force for life as long as premiums are paid
  • Subject to the policy's termination provisions
  • Ends once the maximum benefits have been paid
  • Often a fit because of the range of premium options available
Compare Lifetime Options

How Critical Illness Insurance Compares to Other Supplemental Benefits

Different health events can affect your household in different ways. Supplemental insurance policies may pay because of a diagnosis, hospital stay, accidental injury, or inability to work. Coverage may be available through an employer or as an individual policy.

Hospital Indemnity Insurance

Pays fixed cash benefits after a covered hospital admission or confinement. Benefits may be based on the admission and number of days hospitalized.

We cannot bind coverage by text. After you text us, expect a call.

Golden Shield Life Insurance agent meeting with a client

These policies can work together because each responds to a different event. The right coverage depends on your health insurance, income, savings, workplace benefits, and budget.

Common Questions

Critical Illness Insurance FAQs

What are the 36 critical illnesses?

There is no standard list of 36 critical illnesses. Each carrier defines its own covered conditions. Policies may include cancer, heart attack, stroke, kidney failure, organ transplant, major heart surgery, paralysis, coma, severe burns, neurological diseases, and permanent loss of limbs, sight, hearing, or speech. Review the policy’s definitions, not only the advertised number.

Is critical illness insurance worth getting?

It may be worthwhile if a serious diagnosis could interrupt your income, reduce your savings, or make everyday bills difficult to manage. Consider the premium, covered conditions, payment percentages, exclusions, and whether the benefit would fill a real financial gap.

Can I receive benefits more than once?

Possibly. Some policies pay for multiple covered conditions, later diagnoses, or a recurrence after a required separation period. Other policies end after paying the maximum benefit. Check the recurrence provision, benefit schedule, separation period, and lifetime maximum.

Can I buy critical illness insurance after a diagnosis?

You may still be able to apply, but an existing diagnosis can affect eligibility. The carrier may decline coverage, exclude the diagnosed condition, limit related benefits, or charge a different premium. Coverage is generally easier to obtain before a serious diagnosis occurs.

Does critical illness insurance cover pre-existing conditions?

It depends on the policy. Some plans exclude pre-existing conditions permanently or for a stated period, while others use health questions and medical underwriting to determine eligibility. Review the look-back period, waiting period, exclusions, and policy definition before enrolling.

Expert Advice: Plan While You Still Have Options

Medical treatment can save your life, but surviving a serious illness may create a second challenge: paying for recovery while income and independence are interrupted.

I understand that reality firsthand. After a spinal cord injury left me quadriplegic, the cost extended far beyond the hospital. Transportation, caregiving, medical equipment, home modifications, supplies, and everyday bills became part of daily life. A health crisis does not stop the mortgage, groceries, utilities, or other responsibilities.

1. Do Not Assume Health Insurance Pays for Everything

Health insurance may help pay for covered medical treatment, but it does not replace lost income or cover every expense associated with recovery. Families may still face deductibles, rehabilitation costs, transportation, caregiving, mobility equipment, and household bills.

Critical illness insurance can provide a lump-sum benefit after a diagnosis meets the policy’s definition. That money may help reduce the need to rely on credit cards, retirement savings, loans, or crowdfunding.

2. Understand the Role of Each Policy

Different policies solve different financial problems:

  • Health insurance helps pay for covered medical care.
  • Disability insurance may replace part of your monthly income when you cannot work.
  • Life insurance, whether term life insurance or whole life insurance, pays according to its death-benefit provisions and may include living-benefit riders.
  • Critical illness insurance may pay a lump sum while you are living after a covered diagnosis.

Critical illness coverage does not replace these policies. It adds cash that may be used where your household needs it most.

3. Apply Before Your Health Changes

Insurance is generally easier and less expensive to obtain while you are healthy. After a serious diagnosis, the carrier may decline an application, exclude a condition, limit benefits, or require additional underwriting.

Some policies offer optional features such as recurring-condition benefits, return of premium, or coverage lasting for a stated term or lifetime. These features are not included in every policy and may increase the premium.

The Bottom Line

Do not choose a policy based only on its advertised benefit or number of covered illnesses. Compare the medical definitions, payment percentages, waiting periods, recurrence rules, exclusions, and maximum benefits.

My advice is simple: determine how long your household could manage without your full income, then consider whether a critical illness benefit could close that gap at a premium you can comfortably maintain.

Aaron Polk

Licensed Life and Health Insurance Agent

Founder, Golden Shield Life Insurance · NPN 21216745

What Our
Clients Say

Atlanta SkyView Ferris wheel Georgia State Capitol gold dome in Atlanta
★★★★★
“

Office

Atlanta 1954 Airport Rd
Atlanta, GA 30341
(678) 884-4653

Contact Us to Schedule

Your shield against a critical illness is ready. Are you?

Thank you. Your request is in. A licensed agent at Golden Shield Life Insurance will reach out shortly to match you with your options.
Something went wrong sending your request. Please try again, or call or text us at 678-884-4653.

Disclaimers View
  • This page is educational and is not financial, legal, tax or medical advice. Golden Shield Life Insurance and its agents do not provide tax, legal or medical advice. Consult a qualified professional regarding your individual situation.
  • Golden Shield Life Insurance LLC is an independent insurance agency licensed in Georgia (Agency License 242517) and in additional states. It does not underwrite or issue policies. Critical illness insurance is underwritten and issued by the insurance carrier named in the policy. Golden Shield Life Insurance compares coverage from 130+ carriers rated A- or better by AM Best. Not every carrier offers a standalone critical illness policy; many offer critical illness benefits as an optional rider on a life insurance policy.
  • Critical illness insurance is a specified disease policy that provides limited benefits. It is supplemental coverage and is not major medical insurance, is not minimum essential coverage as defined by federal law, is not a Medicare supplement policy, and does not reimburse hospital or medical expenses. It does not replace health, disability or life insurance.
  • Only the conditions and procedures named in the issued policy are covered, and each must meet the policy's medical definition. Covered conditions, benefit amounts, payment percentages, waiting periods, survival periods, separation periods, recurrence provisions, age-based reductions, lifetime maximums, exclusions and renewal terms vary by carrier, policy form and state. State-specific policy wording controls.
  • Product features described on this page are illustrative. As one example, a lump sum critical illness policy may offer benefit amounts from $10,000 to $100,000, term periods of 10, 15, 20 or 30 years or lifetime coverage, may pay 100 percent of the benefit for conditions such as cancer, heart attack or stroke and a reduced percentage for procedures such as coronary artery bypass or angioplasty, may apply a 30-day probationary period for cancer and a 12-month pre-existing condition limitation, and may end once 100 percent of the benefit has been paid. Products, riders and features are not available in all states, and some optional features, such as return of premium or cash value riders, may not be available in Georgia. Optional riders and features may increase the premium.
  • Claims are paid only after the carrier receives and approves the required claim form and proof of loss within the periods stated in the policy. Benefits are generally paid to the insured unless assigned otherwise. Nothing on this page means a claim is paid automatically or immediately.
  • Approval is not guaranteed. Applications are subject to the carrier's underwriting, which may include health questions, prescription history and Medical Information Bureau inquiries. An applicant may be declined, a condition may be excluded, or coverage may be limited based on health history, age, height and weight, residency or other factors. Some carriers require that health insurance be in force at the time of application.
  • Policies are generally guaranteed renewable until the full benefit is paid or the term period ends, as long as premiums are paid within the grace period. A carrier may change premiums for all policies of the same class with advance written notice. Rate figures are not published on this page because they vary by carrier, age, tobacco use, benefit amount, coverage type and optional riders. Your premium depends on a personalized quote.
  • Heart attack, stroke and cancer statistics describe national totals and do not predict any individual's risk. Figures are subject to revision by the publishing organization.
  • Critical illness insurance benefits paid under a policy you funded with after-tax dollars are generally not taxable income, but employer-paid or pretax premiums can change that result. Receipt of benefits may affect eligibility for Medicaid or other government programs. Consult a qualified tax professional.
  • Golden Shield Life Insurance does not guarantee approval, pricing or benefit eligibility. Any benefit payment depends on the issuing insurer and the terms of the policy. Coverage cannot be bound by text message. After you text, expect a call from a licensed agent.
  • Outbound links are provided for reference. Golden Shield Life Insurance does not control and is not responsible for third-party content, including any sponsorships or advertising those sites carry.