Life insurance for business owners helps protect your family, business income, debts, employees, and partners if you die. Coverage can fund buy-sell agreements, replace a key employee, or support business succession.
Golden Shield Life Insurance compares term, whole life, and other coverage options across multiple insurance companies to help you find a policy that fits your business, budget, and goals.
Written By:
Licensed & Reviewed
Aaron PolkAaron Polk, CEO and founder of Golden Shield Life Insurance, helps individuals and business owners secure custom life insurance, business continuity plans, and retirement income strategies.
Connect on LinkedIn
The right life insurance policy depends on what you own, who depends on your business, and what would happen financially if you were no longer there.
Key Takeaways
Protect your family: Replace lost income and help cover personal debts.
Protect your business: Provide funds for loans, payroll, and operational expenses.
Protect your partners: Fund a buy-sell agreement so ownership can transfer as planned.
Protect key employees: Help the business recover financially from losing an essential person.
Plan for disability: Review disability income and business overhead coverage separately from life insurance.
Editor's Note
In 2007, while running my moving and storage company, a vacation accident left me a quadriplegic. At 27, I had turned down life, disability, and key-person coverage because I figured I could get it later.
About a month later, everything changed.
That experience, and what it cost me financially, is why I help business owners protect their companies, income, and families before an unexpected event changes everything.
Start by identifying the need, estimating the financial gap, and building a plan for what happens if you die, become ill, or can no longer run the business.
Personal vs. Business Life Insurance
When you own a business, your death can affect more than your family's income. It may interrupt operations, leave debts unpaid, and create financial problems for employees and partners.
Most owners need to think about two kinds of protection. Personal life insurance is usually owned by you and pays your family, so they can replace your income, pay off the mortgage, and cover debts you personally guaranteed. If you are alive but cannot work, income protection insurance is what replaces part of your paycheck. Business life insurance is usually owned by the company or your partners and protects the business itself, through key person coverage or a funded buy-sell agreement.
One policy rarely does both jobs well, because the owner and beneficiary decide who controls the money. Calculate each need separately so the right people receive the death benefit.
What Business Coverage Do You Need?
Start by identifying the financial risks your business faces.
Family income: Would your household lose income if the business stopped operating?
Business debt: Are there loans, leases, or debts you personally guaranteed?
Key employees: Could the business operate without its most important people?
Business partners: Who would purchase your ownership interest if you died?
Succession: Who would take over the business, and how would the transition be funded?
Disability: Could the company continue operating if you survived an illness or injury but could not work?
These answers help determine who should be insured, who should own the policy, and the coverage amount needed.
How Much Life Insurance Does a Business Owner Need?
There is no single amount that works for every business. Calculate your family's financial needs separately from your company's obligations.
For personal coverage, consider income replacement, mortgage payments, debts, dependents, and final expenses. Mortgage protection insurance can be set up to match the balance on your home, and final expense insurance can cover funeral costs and smaller bills.
For business coverage, consider outstanding loans, payroll, lost revenue, replacement costs, and ownership agreements.
Key person insurance should reflect the financial impact of losing an essential employee or owner.
Buy-sell insurance should reflect the value of the ownership interest being purchased under the agreement.
Review these amounts as your business grows or its financial obligations change.
How Much Does Business Life Insurance Cost?
The price depends mostly on the person being insured, not the business. Insurance companies look at:
Age
Health history and current medications
Tobacco use
Coverage amount
Policy length, or whether the coverage is permanent
Key person and buy-sell policies are priced on the age and health of the owner or employee being insured, so covering two partners means two sets of underwriting. Term insurance generally costs less at the start than whole life for the same death benefit.
Each insurance company weighs health and risk differently, so the same person can receive different offers. That is why comparing actual quotes matters. Request your business life insurance quotes.
Compare Types of Business Life Insurance
Term and permanent life insurance are the two main coverage categories. Key person coverage and buy-sell funding describe how a policy is used, not separate types of insurance.
Term Life Insurance
Term life insurance provides a death benefit during a selected coverage period, commonly 10, 20, or 30 years. It generally costs less initially than permanent insurance for the same death benefit.
Term life may fit business loans, temporary income replacement, and buy-sell agreements with a defined timeline.
Permanent Life Insurance
Whole life and universal life insurance, including indexed universal life, can provide lifelong coverage, subject to policy requirements. Many policies build cash value that may be accessed through loans or withdrawals.
Permanent coverage may suit long-term succession needs, lifetime dependents, or business obligations without a defined end date.
Policy loans and withdrawals may reduce cash value and death benefits and can have tax consequences.
Term life can fit
Permanent life can fit
A large payout for a young family
Coverage that lasts your whole life
A set-time debt, like a 10-year business loan
Estate planning
Funding a buy-sell deal with a set timeline
Cash value you can borrow from like a bank, which may help pay off high-interest debt
Owners who do not need cash value
A cash reserve for the business that may have tax benefits
Some businesses rely heavily on one owner, executive, salesperson, or specialist.
With key person life insurance, sometimes called key man insurance, the business generally owns the policy, pays the premiums, and receives the death benefit.
Coverage should reflect the person's financial contribution, not simply their salary.
Life Insurance for Sole Proprietors
A sole proprietor may be the company's primary source of income and daily operations.
Owners with serious health conditions who cannot qualify for traditional coverage may still be able to get guaranteed issue life insurance, which asks no health questions but has lower coverage limits and a waiting period for the full benefit.
If the owner dies, the business may close, leaving family members without income and with unresolved debts or business obligations.
The primary needs are usually replacing household income, covering debts, and providing funds to close or transfer business operations.
A sole proprietor without partners or other key employees generally has less need for buy-sell or key person coverage.
Buy-Sell Agreements and Partner Buyouts
A buy-sell agreement establishes how an owner's share of a business will be transferred. Life insurance can provide the money needed to complete that purchase.
For example, two partners own equal shares of a business valued at $2 million. Each partner owns a $1 million policy on the other.
If one dies, the surviving partner may receive the death benefit and use it to purchase the deceased partner's share under the agreement.
The agreement should specify the purchase terms, valuation method, policy ownership, and beneficiaries.
There are two common ways to set this up. In a cross-purchase plan, each owner buys a policy on the other owners and uses the proceeds to buy the deceased owner's share. In an entity-purchase plan, the business owns the policies and buys back the shares itself. Cross-purchase plans can become hard to manage with more than two or three owners, because each owner needs a policy on every other owner.
Business loans do not automatically disappear when an owner dies. Debts that an owner personally guaranteed may also create obligations for the owner's estate.
Life insurance proceeds may help address:
Business loans and lines of credit
Commercial mortgages
Equipment financing
Outstanding leases
Personally guaranteed debts
Some lenders require life insurance with a collateral assignment. This gives the lender rights to proceeds up to the amount owed, with any remaining benefits distributed according to the policy terms.
Business Succession Planning
Succession planning determines who will operate or own your business when you retire, become disabled, or die, whether that is a family member, partner, employee, management team, or outside buyer.
If you plan to sell or step away from the business, a fixed annuity is one way some owners set aside part of the proceeds for retirement income. You can estimate growth with our fixed annuity calculator.
Legal agreements establish how ownership transfers, but they do not automatically provide the money needed. Life insurance may help fund the transition, support family members, and pay obligations, so coordinate it with your business valuation and operating agreement.
Who Should Own the Life Insurance Policy?
Policy ownership depends on what the insurance is intended to accomplish.
Personal coverage: Generally owned by the insured or an appropriate trust, with family or other designated beneficiaries.
Key person coverage: Generally owned by the business, which receives the death benefit.
Buy-sell funding: May be owned by individual partners or the business, depending on the agreement.
Business debt coverage: May involve a business-owned policy or a collateral assignment to a lender.
Ownership determines who controls the policy and receives the proceeds. Business-owned coverage may also involve tax, notice, consent, and reporting requirements.
Disability and Business Overhead Protection
Death is not the only event that can interrupt a business.
A serious illness, accident, or disability may prevent an owner from working while business expenses continue.
Business owners may offer life insurance as part of an employee benefits package.
Options include employer-paid group term coverage, voluntary supplemental insurance, and certain executive benefit arrangements.
The employer may pay all or part of the premiums, depending on the plan.
Eligibility, participation requirements, portability, and tax treatment vary by insurer and plan design.
Tax Considerations: Can Your Business Pay for Life Insurance?
Sometimes. Whether premiums are deductible depends on the policy owner, insured person, beneficiary, and business structure.
Sole Proprietorship: Personally owned life insurance premiums are generally not deductible.
Partnership: Coverage may be owned by partners or the business. Tax treatment depends on the arrangement.
LLC: Business-owned key person premiums are generally not deductible when the company benefits.
S-Corporation: Premiums are generally not deductible when the corporation is the beneficiary.
Employee Group Life: Qualifying group term coverage may receive favorable tax treatment, including special rules for the first $50,000, per IRS guidance on group-term life insurance.2
Life insurance death benefits are generally received free of federal income tax, although exceptions apply.1
Business-owned policies, buy-sell agreements, and executive benefits may have additional requirements.
Coordinate policy ownership and tax planning with your CPA or attorney.
Why Shop With Golden Shield Life Insurance?
Golden Shield Life Insurance helps business owners compare private insurance policies across multiple carriers rather than relying on one company's products.
We help evaluate coverage for family income, business loans, key employees, partner buyouts, and succession planning.
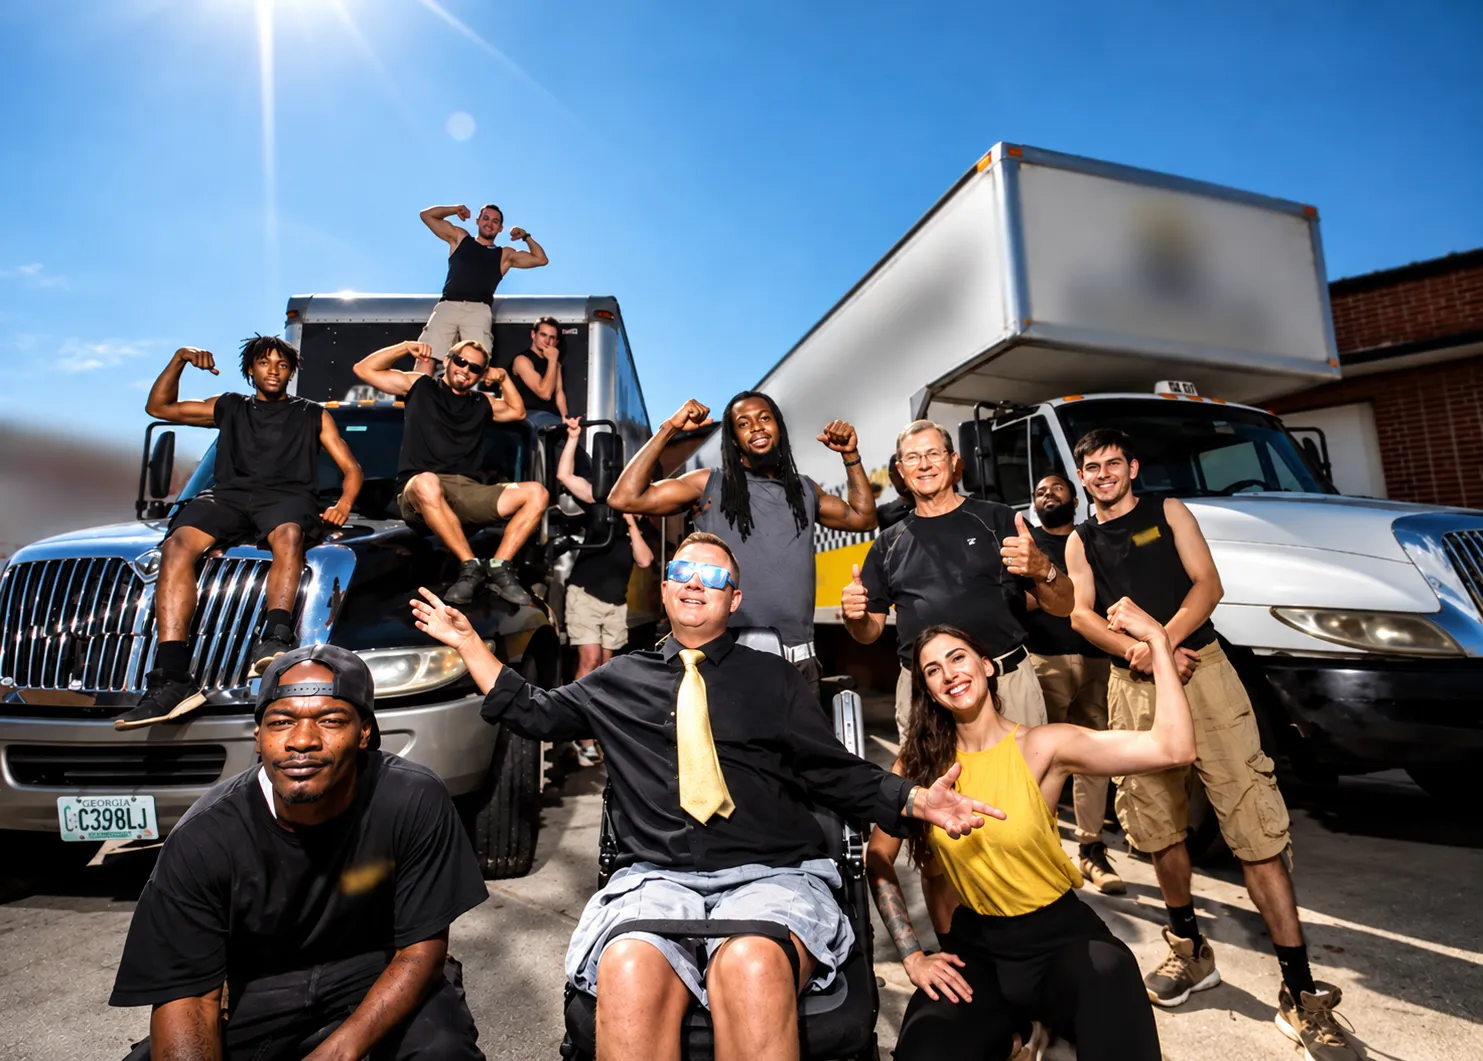
We work with small business owners, sole proprietors, and LLC owners of every kind, including contractors, roofers, HVAC owners, truck drivers and owner operators, movers, dumpster rental operators, hair stylists, dealers, and artists. Aaron Polk owned and staffed a moving company before founding Golden Shield Life Insurance, so he knows what happens when the owner is the business.
As an independent brokerage, our goal is to explain your options, compare eligible quotes, and help you select coverage that fits your business structure and budget.
How to Buy Life Insurance for Your Business
Identify the need. Decide whether the coverage protects family income, the business, or ownership interests. Many owners need more than one policy.
Estimate the obligations. Add up the income, debts, payroll, and ownership value the policy needs to cover.
Choose the owner and beneficiary. Decide who should own the policy and who should receive the death benefit.
Compare quotes. Compare term and permanent options from multiple insurance companies.
Apply and coordinate. Complete the application and underwriting, then line the policy up with your buy-sell, operating, or loan agreements.
Talk With a Licensed Agent or Book a Free Consultation.
Pick your shield today. Have a question? Call us at (678) 884-4653.
Compare different types of coverage depending on your business needs, debts, or liabilities.
AdvantagesLimitation
Key Person Insurance
Best for: Businesses that depend heavily on an owner or essential employee.
Advantages
May replace lost revenue and maintain operations.
Can help fund recruiting and replacement costs.
Limitation
Coverage should be reviewed as the business changes.
Buy-Sell Funding
Best for: Businesses with multiple owners who want a funded ownership transfer.
Advantages
Provides money for a planned partner buyout.
May reduce the need to sell business assets.
Limitation
Requires an appropriate written agreement and updated business valuation.
Business Loan Protection
Best for: Owners with business financing or personally guaranteed debts.
Advantages
May help repay outstanding loans.
Can provide liquidity when a business owner dies.
Limitation
Collateral assignments may give lenders priority over some policy proceeds.
Succession Planning
Best for: Owners preparing to transfer their business.
Advantages
May fund an ownership transition.
Can provide financial support during the transfer.
Limitation
Insurance does not replace a written succession plan.
Partnerships
Best for: Businesses with two or more owners.
Advantages
Can fund cross-purchase or entity-purchase agreements.
May reduce financial disputes after a partner dies.
Limitation
Coverage must reflect current ownership values and agreements.
LLC Owners
Best for: LLC members protecting income, business obligations, or ownership interests.
Advantages
May help fund partner buyouts.
Can provide funds for certain business liabilities.
Limitation
Ownership and tax arrangements require careful coordination.
Sole Proprietors
Best for: Independent owners whose income supports their families.
Advantages
May replace lost household income.
Can help pay debts and wind down operations.
Limitation
Coverage does not replace a plan for closing or transferring the business.
Small Business Owners
Best for: Owners balancing business growth, debt, employees, and family needs.
Advantages
Can address several financial risks through coordinated policies.
Coverage may be adjusted as business needs change.
Limitation
Multiple policies increase costs and require periodic review.
Common Questions
Life Insurance for Business Owners FAQ
Do I need both personal and business life insurance?
Many business owners do. Personal coverage protects your family's income and personal debts, while business coverage, such as key person insurance or a funded buy-sell agreement, protects the company and your partners. One policy rarely does both jobs, because the owner and beneficiary determine who receives the money.
Can an LLC get a life insurance policy?
Yes. An LLC can own a life insurance policy on a member or key employee when it has an insurable interest, such as for key person coverage or to fund a buy-sell agreement. The insured person generally has to receive notice and give written consent before the policy is issued. Whether premiums are deductible depends on who owns the policy, who benefits, and how the LLC is taxed.
Can a business pay for life insurance?
Yes. A business can pay premiums on policies it owns, such as key person or entity-purchase buy-sell coverage, and it can pay for group life insurance for employees. Premiums are generally not deductible when the business is the beneficiary. Premiums a business pays on an owner's or employee's personal policy may be treated as taxable compensation. Coordinate the setup with your CPA.
How much is a $1,000,000 life insurance policy a month?
The cost depends on age, health, tobacco use, policy type, and coverage length. A $1 million term policy generally costs less initially than whole life insurance. Compare actual quotes for your circumstances before choosing coverage.
Can you get life insurance on a business?
A business can own life insurance on an owner or qualifying key employee when insurable interest and other applicable requirements are satisfied. The business may receive the death benefit to help cover financial losses or obligations.
What happens to my business loan if I die?
The debt does not disappear. The business still owes it, and if you personally guaranteed the loan, the lender may make a claim against your estate. Life insurance can provide money to pay the balance, and some lenders require a policy with a collateral assignment so they are repaid first.
Do you pay taxes on company-provided life insurance over $50,000?
Employer-provided group term life insurance generally receives favorable treatment for the first $50,000 of coverage. The cost of coverage above that amount may create taxable imputed income, subject to applicable rules and exceptions.
What is the 7 year rule for life insurance?
In the U.S., the "7-year rule" usually refers to the 7-pay test. If you pay more into a permanent life insurance policy during its first seven years than federal limits allow, the policy becomes a modified endowment contract, or MEC.4 The death benefit is generally still income-tax-free, but loans and withdrawals from a MEC are taxed differently and may face a 10% penalty before age 59½. Business owners who put large amounts into a cash value policy should ask how close it is to the MEC limit.
Summer's Story
Mortgage Lender & Business Owner
Summer is a mortgage lender and business owner who has learned how whole life insurance can fit into her business model, both for current financial security and future legacy plans.
Building a business takes years of work. Protecting it means thinking beyond your own paycheck. Loans, employees, partners, and family members may all depend on what you've built.
I've learned that the right coverage depends on how a business operates, who owns it, and what needs protection. My advice is simple: review your obligations, compare your options, and put a plan in place that your business and family can depend on.
Aaron Polk
Founder, Golden Shield Life Insurance
Your shield is ready. Are you?
Something went wrong sending your request. Please try again, or call or text us at (678) 884-4653.
Page Overview
Life Insurance for Business Owners: What They Don't Tell You
Short on time? This video walks through what actually happens to a business, its debts, and its people if an owner dies or becomes seriously ill, and why planning ahead matters.
Educational overview. Policy details vary by carrier, state, and underwriting.
Video Transcript
Welcome to the explainer. Today we're diving into something that is absolutely crucial. Safeguarding your life's work. If you run a company, you already know firsthand that your business is way more than just a paycheck, right? It's your legacy. It's your family's financial engine. And it's often the anchor for your employees and your partners. So today, we're taking a really close look at strategic life insurance specifically for business owners. We'll be using some fantastic insights from Golden Shield Life Insurance to figure out exactly how the right coverage acts as this giant safety net for literally everything you've worked so hard to build.
Okay, let's quickly look at our road map for today. We're going to start with a costly wakeup call, then compare employee versus owner needs. After that, we'll talk about shielding your operations and partners, compare term and permanent coverage, and finally, we'll navigate the nuts and bolts of ownership and tax basics.
So section one, a costly wakeup call. Because business planning isn't just theory or numbers on a spreadsheet. It's about real people and how incredibly fast life can change. To really establish the stakes here right out of the gate, we have to talk about a pretty vulnerable story from Aaron Polk, the founder of Golden Shield Life Insurance. Back in 2007, he was running a moving and storage business when a sudden vacation accident left him a quadriplegic. He was just 27 years old. And at the time he had actually turned down life, disability, and key person coverage. You know, he figured he'd just get it later. Well, 30 days later, everything changed. That single decision to delay coverage came with immense costs. It's just a perfect illustration of why we absolutely must plan for our companies and our families before an emergency actually strikes.
So, to prevent your business from becoming a cautionary tale, you need a really solid three-step survival plan. Step one, identify the specific events that could financially disrupt your family or your business. Think unexpected death or severe illness. Step two, estimate the actual financial gap. You've got to put a hard number on household income needs, business debt, payroll, and ownership transfer. And then step three, build a concrete written plan detailing exactly who is going to operate, buy, sell, or transition the business if you suddenly can't.
Moving right along to section two, employee versus owner needs. It's really vital to understand that owning a company fundamentally changes the strategic math you might be used to.
There is a stark contrast in responsibilities here. If you're a standard employee, your life insurance has one simple job, right? Replace your paycheck so your family's covered. Boom. Done. But as a business owner, you are literally performing a three-part balancing act. Your passing doesn't just end a salary. It can put the entire business at risk. You don't have an employer group plan to fall back on because well, you're the employer. You have to protect your family, the business entity itself, and your partners if you have them.
But hey, what if you don't have partners? What if you're riding solo? Well, even sole proprietors face completely unique risks because personal and business liabilities are usually deeply intertwined. If you run a single member LLC, you're the HR department, the CEO, and the top revenue driver, all rolled into one person. If you pass away, operations might just instantly stop. That means your coverage needs to replace that lost income for your dependents, cover any outstanding business debt, because that doesn't just magically disappear, and provide the funds necessary to wind down the business in an orderly way without leaving a huge financial mess for your family to clean up.
And that leads us naturally into section three, shielding operations and partners. Let's look at the actual day-to-day operational applications of this insurance. I really want you to ask yourself this guiding question. What happens to your family if the business income just stops? For so many owners, the company is both the primary income source and one of the family's largest financial assets. Losing the owner means the household could instantly lose salary, distributions, benefits, and all of future income from the business.
This right here is exactly why your personal life insurance and your business life insurance need to live in two completely separate buckets.
Now, looking at the business side of things, let's talk about key person coverage. Imagine your top revenue driver or your brilliant tech lead just doesn't come in on Monday. A business owned policy on a crucial employee isn't just about covering their salary. It's really about their total financial impact on the company's survival. Key person coverage is what gives you the breathing room to replace lost revenue, recruit and train a replacement, maintain your working capital, pay obligations, and smoothly manage what is bound to be a really stressful leadership transition.
Now, let's factor in your partners. Here is some simple but absolutely crucial math regarding partner buyouts. A buy-sell agreement dictates what happens. Sure, but it doesn't magically print the money to actually make it happen. Let's say you and a partner own a business valued at $2 million. Each of you takes out a $1 million policy on the other's life. If your partner passes away, you receive the death benefit. This creates instant liquidity to execute the buyout without draining company cash, taking on massive debt, or worst of all, forcing your partner's grieving family to step in and run an operation they probably don't want any part of.
We also have to talk about business debt. Sadly, death doesn't eliminate commercial mortgages or equipment loans, especially the ones you've personally co-signed. So, think of collateral assignment as a protective wall between your commercial lender and your family's inheritance. It's this essential legal arrangement where a lender gets rights to a portion of your death benefit to cover that specific outstanding debt. Once the lender is paid off, the remaining proceeds go safely to your designated beneficiaries just as intended.
Which leads us to pivot to another really bold question. Who takes over when you can no longer run the business? Succession planning is all about having a clear strategy for whether the successor is a family member, a co-owner, an employee, or maybe even an outside buyer.
Check out this staggering number, 44%. According to PwC's 2025 US Family Business Survey, almost half of all US family firms wrestled with succession planning in the past year alone. It's a huge issue. A will or an operating agreement might outline the transfer on paper, but life insurance provides the actual liquidity to fund the transfer, buy out an estate, or equalize inheritances. It gives the company that much needed financial flexibility during a major transition.
Let's shift gears and move into section four, term versus permanent coverage. These are the two main vehicles you're going to use to actually fund these business strategies. It really all comes down to balancing your coverage against your operational cash flow.
Term life is basically your temporary shield for timebound obligations. Think like a 10-year bank loan or a defined buyout timeline. It has a much lower premium impact which leaves more cash in the business, but it accumulates zero cash value. Permanent life, on the other hand, like whole or universal life, is best for ongoing needs with no clear end date, like legacy goals or lifelong buy-sell agreements. It definitely requires a larger ongoing premium commitment, but it builds a cash reserve that acts as a true business or personal asset. Honestly, a lot of owners use a combination of both just to keep the business covered without straining their operating cash.
And finally, we arrive at section five, ownership and tax basics. Now, I know taxes aren't the most thrilling topic, but stick with me because they are absolutely crucial. In business insurance, how a policy is structured matters just as much as the coverage amount itself.
Who owns the policy dictates three major things: who controls it, who gets the money, and probably most importantly, how the IRS treats it. So, making sure it's set up right from day one is critical. If the purpose is family income, the owner should typically be you personally or a trust. For key person coverage, the business usually owns it. If we're talking a partner buyout, it's either the business or the co-owners depending on your specific agreement. And for business debt, it depends entirely on whether the obligation is personal or corporate.
So, the million-dollar question, can your business just expense the premiums? Man, if only the IRS made it that easy. Generally, the answer is no. A company paying the premium doesn't automatically mean a tax deduction. For a sole proprietorship, personal family coverage isn't deductible. For an LLC or an S-Corp, if the business owns a policy and benefits from it, the premiums are generally not deductible either. There are some special IRS rules for the first $50,000 of group life coverage. But the real rule of thumb to remember is this. While death benefits are usually received tax-free, the premiums aren't deductions. Because of all these little complexities, you absolutely must coordinate this with your CPA.
One last logistical point before we wrap up. Carrier shopping. Look, insurance carriers do not all view the exact same health profile the same way. A condition that one carrier rates as standard might be rated significantly higher at another one, which ends up costing you way more in premiums. This is exactly why comparing options across the entire market like Golden Shield does with over 130 companies is such a vital step. Moving just one single rating class isn't some minor detail. It can save you thousands of dollars over the entire life of that policy. You want your profile shopped across multiple carriers before you apply rather than just rolling the dice with one company.
Wow. Okay, we've covered a ton of ground in this explainer today. From identifying financial gaps all the way to structuring ownership and dealing with taxes, but I really want to leave you with this final provocative thought. Your business took years of sweat, stress, and total sacrifice to build. Does your current coverage actually match that effort? It's time to stop viewing coverage solely through a family lens and start looking at the full financial picture of your operations, your partners, and your obligations.
Planning for your company is just like planning for your family. You do it because you care deeply about the people who depend on you. Take the action required today to ensure your life's work remains totally secure tomorrow.
Founder, Golden Shield Life Insurance Former National Medical Underwriter and Licensed Life Insurance Broker · Georgia License 3710928 · NPN 21216745 · Georgia Agency License 242517
Aaron Polk was running a moving and storage business in 2007 when a vacation accident left him a quadriplegic. At 27, he had turned down life, disability, and key-person coverage, figuring he could get it later. About a month later, everything changed. Today he helps business owners protect their companies, income, and families, comparing more than 130 insurance companies rated A- or better by AM Best.
How this guide was made: Written by a licensed agent from first-hand casework, not compiled from other insurance websites. Tax points are checked against the numbered references in the disclaimer below, each of which is linked. Terms are confirmed again at the time of quoting. Read our editorial standards. Questions about this page? Contact us.
Disclaimer
Updated November 2026
This page is educational information, not tax, legal, or financial advice. Consult your CPA, attorney, or financial advisor about your specific situation.
Tax treatment of premiums and death benefits depends on who owns the policy, who is insured, who pays the premium, and who receives the proceeds. The tax points on this page are general and based on the IRS sources below.
Coverage, pricing, and product availability vary by carrier and state. Approval, pricing, and benefit eligibility are determined by underwriting and policy terms.
Client stories are shared with each client's permission. Individual results vary.
Golden Shield Life Insurance does not promise approval, pricing, or benefit eligibility. The policy contract controls.
2IRS. Group-Term Life Insurance guidance. Supports the special rules for the first $50,000 of employer-provided group-term coverage. Accessed August 2026.
3InsuranceNewsNet. Key Person Life Insurance Keeps Small Businesses Afloat. Supports how key person coverage may help businesses maintain continuity, settle obligations, and stabilize operations after the loss of a critical leader or owner. Accessed August 2026.
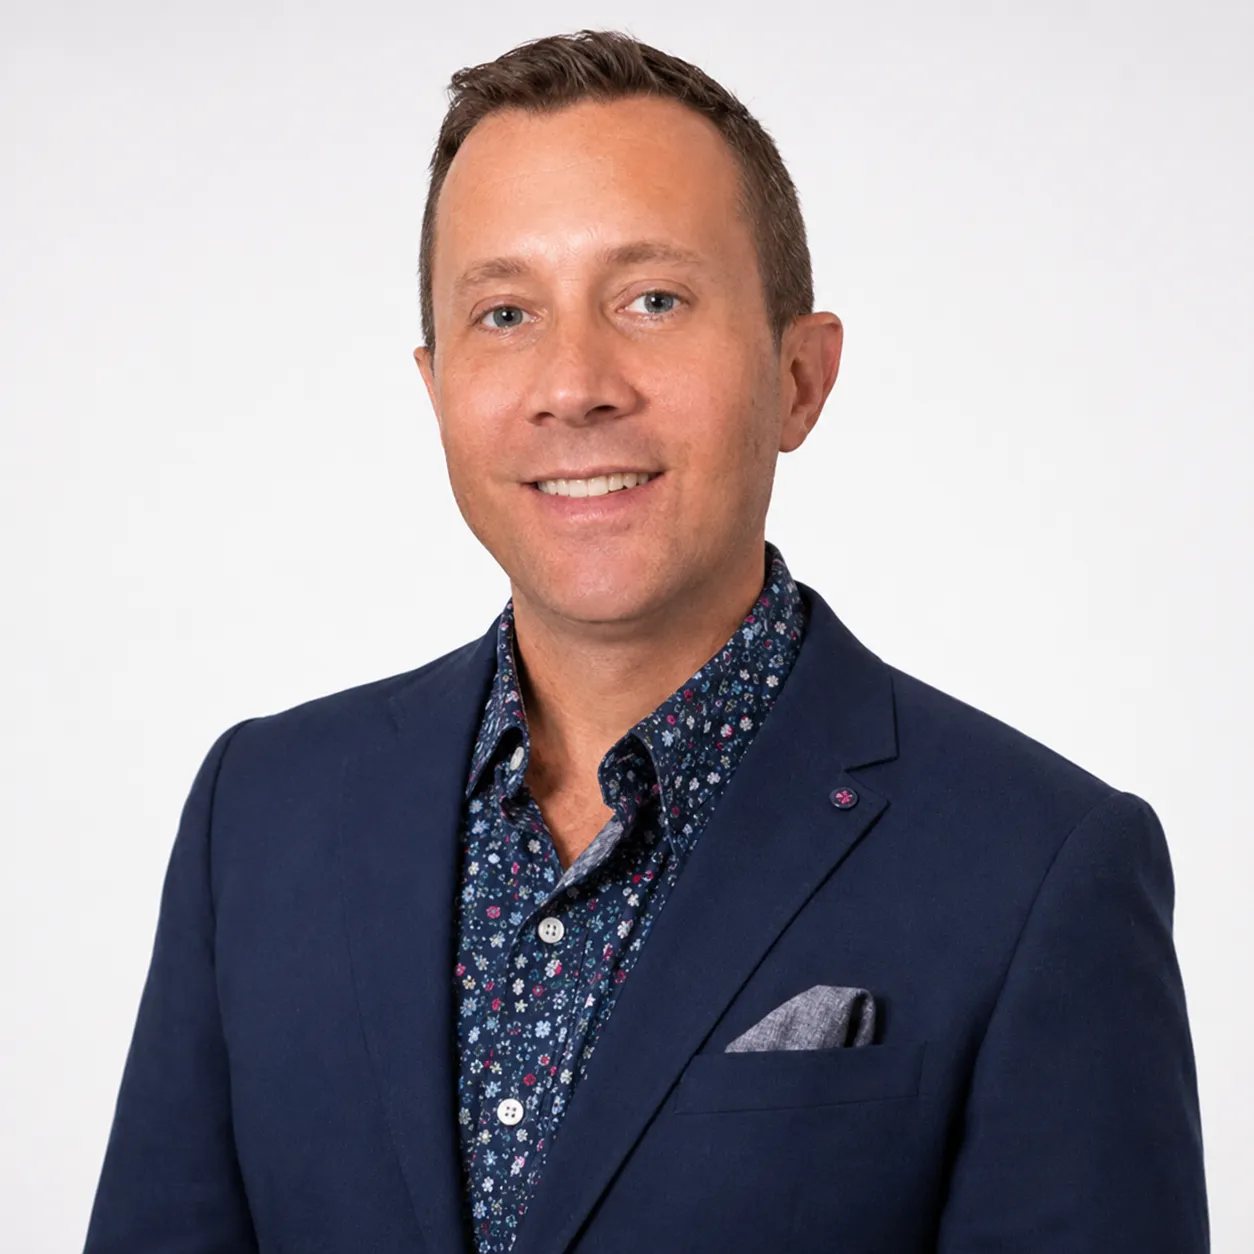 Aaron Polk
, CEO and founder of Golden Shield Life Insurance, helps individuals and business owners secure custom life insurance, business continuity plans, and retirement income strategies.
Connect on LinkedIn
 Start by identifying the need, estimating the financial gap, and building a plan for what happens if you die, become ill, or can no longer run the business.

 Talk With a Licensed Agent or Book a Free Consultation.