Supplemental Insurance

Cancer Insurance

Last Updated 4 minute read

Cancer insurance is supplemental coverage designed to provide cash benefits when a covered cancer diagnosis or treatment occurs. Depending on the policy, benefits may help with medical expenses, treatment-related costs, travel, household bills, or other expenses while you focus on recovery. Benefit amounts, covered diagnoses, waiting periods, and pricing vary by carrier and policy, and coverage is subject to policy terms and underwriting.

Golden Shield Life Insurance can help you compare cancer insurance options across carriers to find coverage that may fit your health history, family, and budget.

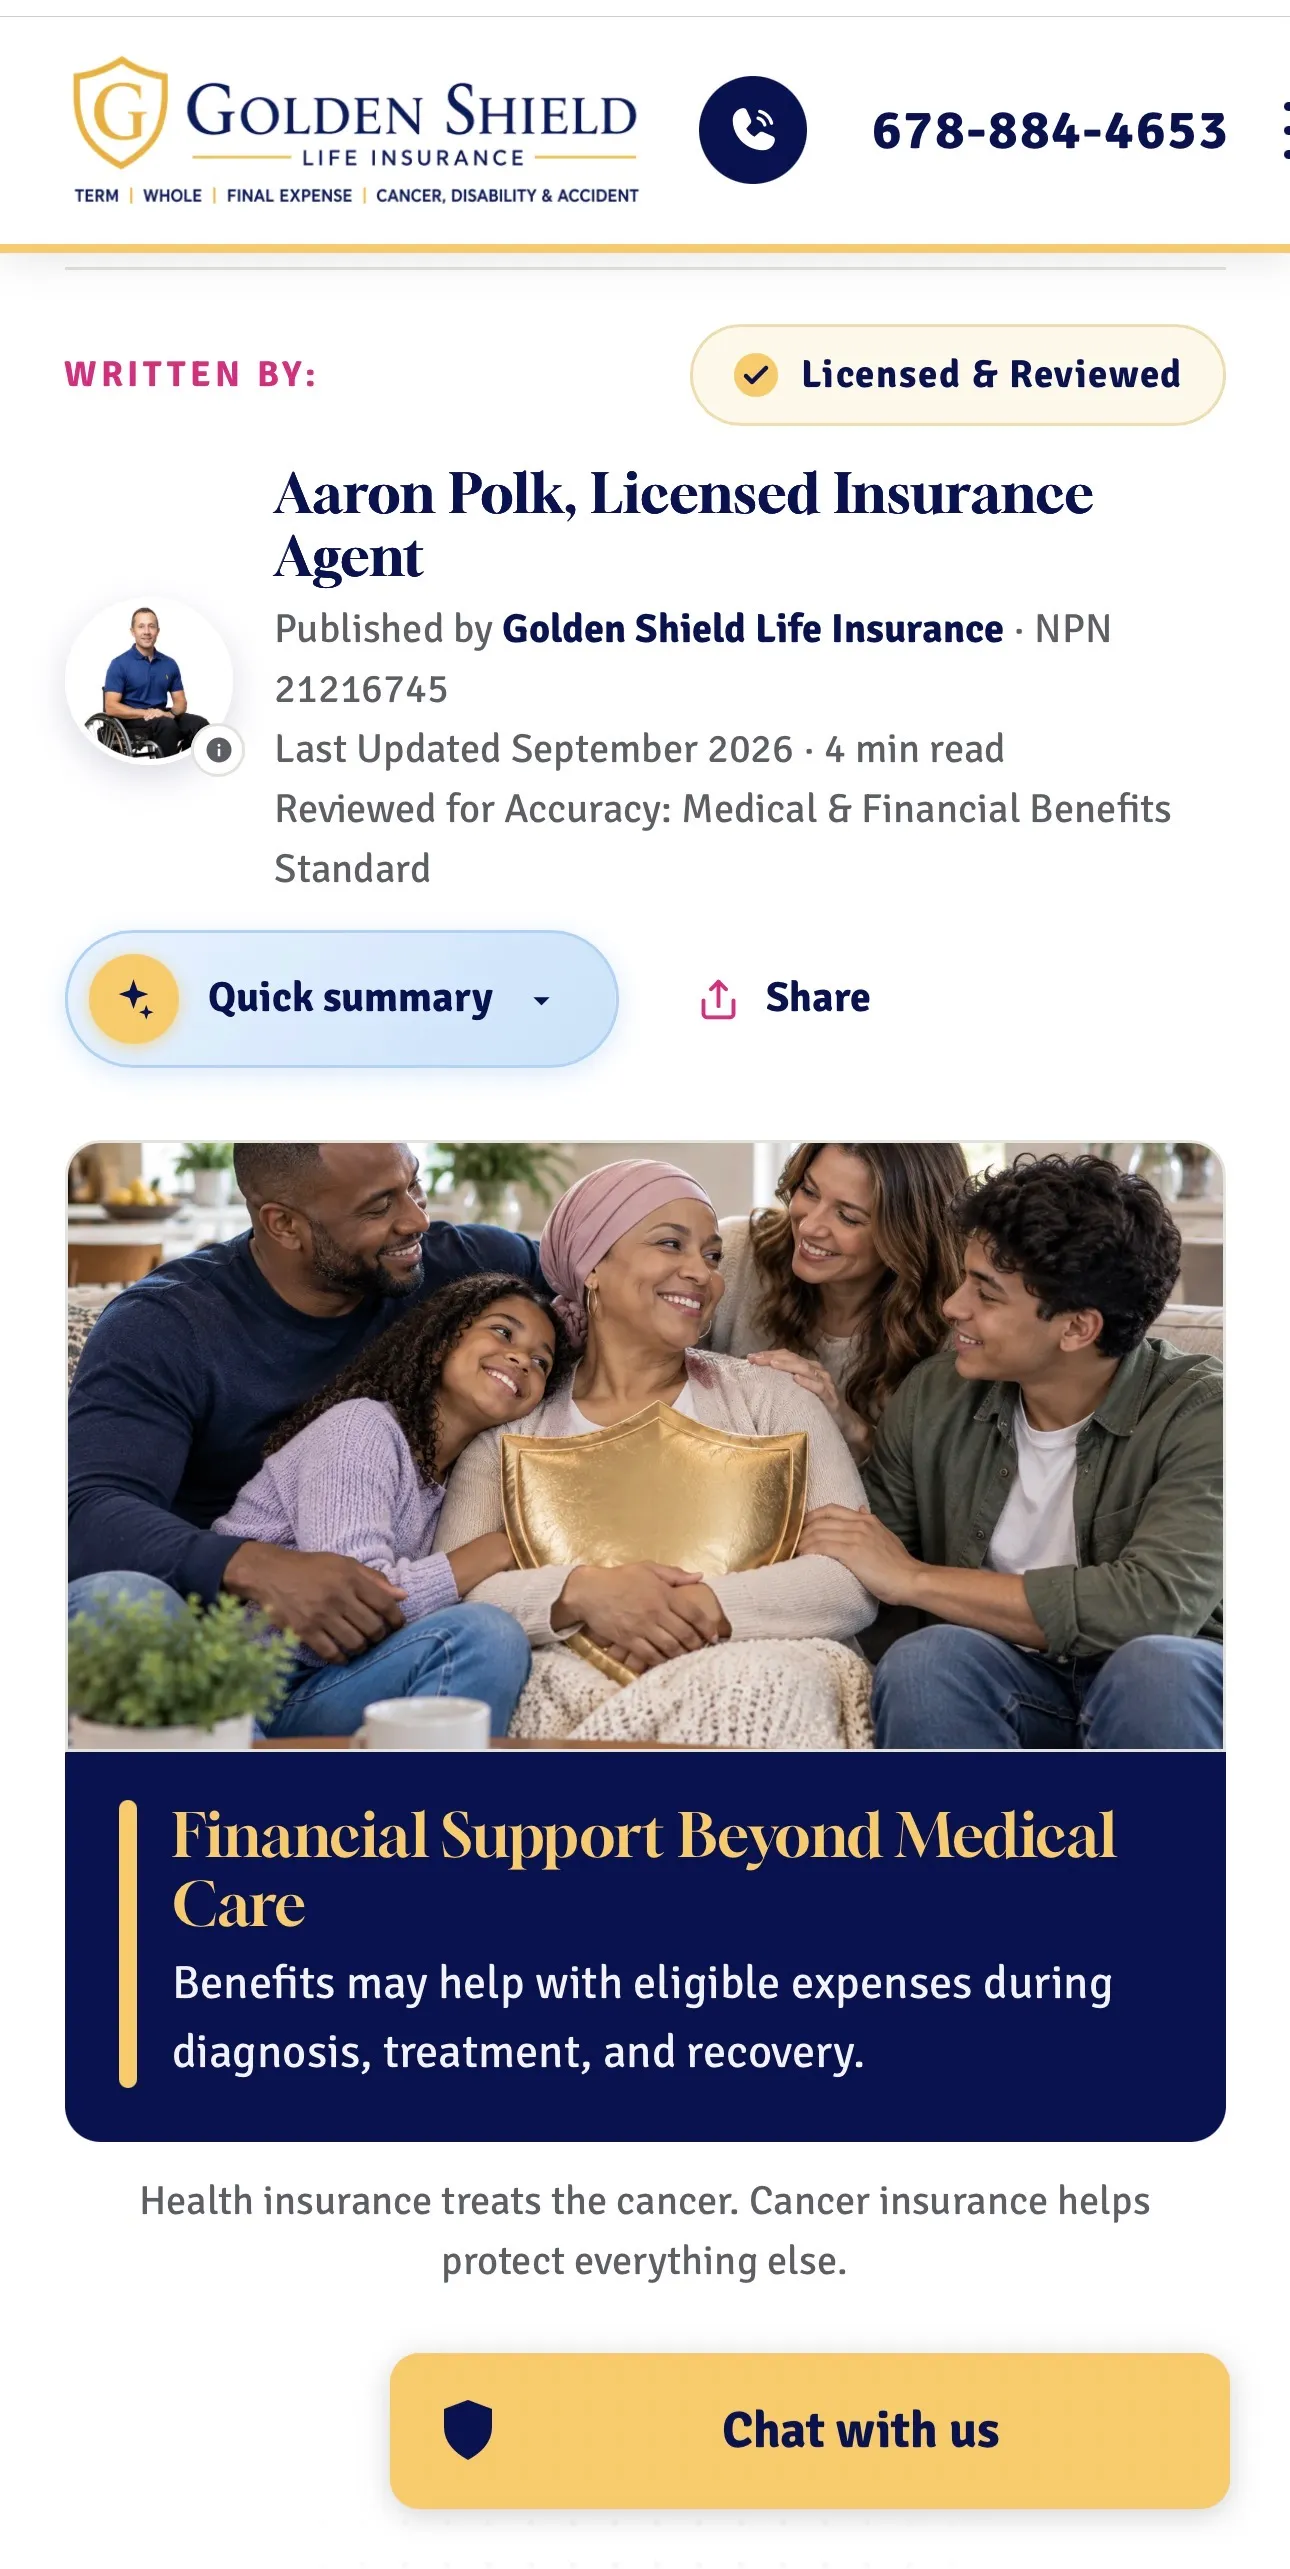
A woman recovering from cancer treatment holding a gold shield, surrounded by her smiling family at home

Financial Support Beyond Medical Care

Benefits may help with eligible expenses during diagnosis, treatment, and recovery.

Health insurance treats the cancer. Cancer insurance helps protect everything else.

LIFE & SUPPLEMENTAL INSURANCE AGENCY

3 Ways to Protect Your Finances Against Cancer Risk

A cancer insurance policy may help you focus on what matters most: getting well. More than 1 in 3 Americans are expected to face cancer in their lifetime. Most people survive it. The five-year survival rate is about 69 percent, but fighting cancer is expensive.3

Cancer-Focused

Individual Policy

  • Focuses specifically on covered cancer
  • Diagnosis and treatment benefit options
  • May include screening, travel, or recurrence features
Triggered by A qualifying cancer diagnosis, treatment, or covered service
Benefit structure Lump sum, scheduled benefits, or both
Broader Conditions

Critical Illness Policy

  • Covers several contract-defined illnesses
  • May include qualifying cancer, heart attack, and stroke
  • One policy can address multiple serious conditions
Triggered by A named illness meeting the contract definition
Benefit structure A contract-defined lump-sum benefit
Hospital-Based

Hospital Indemnity Insurance Policy

  • Triggered by covered hospital care
  • Admission and daily-confinement benefit options
  • May pay for covered hospital stays from cancer treatment, surgery, or other illness
Triggered by A covered hospital admission, confinement, or service
Benefit structure Admission, daily, or scheduled benefits

Cancer Policy Pays 14 Covered Costs

  1. Preventive cancer screenings
  2. Hospital rooms and intensive care
  3. Radiation therapy, chemotherapy, and immunotherapy
  4. Covered surgical procedures
  5. Doctor visits during hospital confinement
  6. Follow-up doctor visits
  7. Covered prescription drugs and medications
  8. Diagnostic X-rays and laboratory procedures
  9. Anesthesia
  10. Home health care
  11. Hospice care
  12. Skilled nursing or rehabilitation care
  13. Blood and blood plasma
  14. Ambulance transportation

This list is drawn from the Mutual of Omaha supplemental cancer insurance brochure,1 one of the carriers Golden Shield Life Insurance represents. Covered costs, benefit amounts, and limits vary by carrier, policy, and state. We compare cancer insurance and riders from multiple carriers so you can see which options you qualify for.

Get Quote

Free Coverage Review

Already Have Coverage at Work? Let’s Look at It Together.

Many people have cancer insurance through their job and are not sure what it pays or whether they can keep it if they leave. Others have nothing at all. Tell us what you have, or send your benefits summary, and a licensed agent will walk through it with you. If your current coverage is enough, we will tell you.

“If you want to talk about this, we are available, free, licensed, and ready to talk.”

Aaron Polk, Founder, Golden Shield Life Insurance

No cost, no obligation.

Cancer Insurance Buyer's Guide

Before choosing cancer insurance, review what you already have, identify the financial pressure a diagnosis could create, understand how each policy pays, and compare the contract rather than looking only at the monthly price.

  • Review your current coverage. Examine your health insurance deductible, copayments, coinsurance, out-of-pocket limit, paid leave, disability benefits, savings, and workplace supplemental coverage.
  • Identify the financial gap. Consider income interruption, treatment travel, caregiver time away from work, childcare, lodging, groceries, and regular household expenses.
  • Choose how benefits should be paid. Determine whether a lump-sum benefit, scheduled treatment benefits, broader critical-illness coverage, hospital benefits, or an eligible rider may better address the concern.
  • Compare more than price. Review the covered diagnosis, benefit amount, waiting period, exclusions, recurrence rules, renewal terms, portability, and state availability.

Key Takeaways

  • Cancer insurance is supplemental coverage and does not replace major medical insurance.
  • Depending on the contract, benefits may be paid as a lump sum, scheduled amounts for covered services, or a combination of both.
  • The right option depends on existing coverage, household expenses, savings, income exposure, health history, budget, and policy availability.
Expert Advice

I have been through a skin cancer diagnosis myself. We also lost Max, our Golden Doodle and the agency’s operations manager, to cancer. Going through my own diagnosis, and then walking with Max through his, gave me a deep desire to help families understand this coverage before they ever need it.

Years ago, I declined supplemental coverage. Twenty-eight days later, an accident left me completely paralyzed, and I could not reconsider that decision after my life had changed.

That experience shaped Golden Shield Life Insurance. I do not believe every person needs every policy. I believe people deserve to understand what coverage may do, what it does not do, and what must happen before a benefit becomes payable. Compare the contract, not only the price.

Search any agent or agency through the national producer license lookup.6 Run that check on us too. Golden Shield Life Insurance, Georgia Agency License 242517, NPN 21216745.

Aaron Polk, founder of Golden Shield Life Insurance, with his Golden Doodle, Max
Aaron Polk with Max, in loving memory.

What Is Cancer Insurance?

Cancer insurance is extra coverage that may pay you money if you are diagnosed with a covered cancer. You can buy it on its own or add it as a rider to a plan you already have.

Regular health insurance pays doctors and hospitals directly. Cancer insurance is different. It pays cash to you. Depending on the policy, you may get the money all at once in one lump sum or in smaller scheduled payments. You can use the cash for what you need most, such as medical bills, travel to see specialists, or everyday expenses if you have to miss work. It helps with extra costs, but it does not replace your main health insurance.

At Golden Shield Life Insurance, we are independent brokers. We are not tied to one insurance company. We shop and compare qualifying plans from 130+ carriers rated A- or better by AM Best9 to find the fit for your needs, instead of presenting only one company’s option.

Why Is Cancer Insurance Important?

A cancer diagnosis can affect both health and household finances. Even with medical insurance, deductibles, cost sharing, travel, missed work, and caregiving responsibilities may create additional pressure. When the contract requirements are met, supplemental benefits may help a household manage part of that financial gap.

The American Cancer Society reports that about 70 percent of people diagnosed with cancer now survive, which means more families live with the cost of treatment for years.3 The National Cancer Institute notes that patients may spend a large share of their income on care, in some cases around 20 percent.4

The financial strain can be severe. A study published in Health Affairs found that people diagnosed with cancer in Washington state were 2.65 times more likely to file for bankruptcy than people without cancer, and younger patients faced the highest risk.10 The researchers suggested that supplemental policies paying fixed sums could help families cover household and out-of-pocket costs in the first year after a diagnosis.

If treatment affected your income tomorrow, how long could your household continue paying its regular expenses?

  • Illustration of household income interrupted during cancer treatment

    Income Does Not Pause Gracefully

    Treatment may interrupt the income a household still depends on.

  • Illustration of a caregiver reducing work hours to support a family member in treatment

    Caregiving Can Affect Two Incomes

    A caregiver may also reduce work hours to provide transportation and support.

  • Illustration of travel, lodging, and parking costs for specialized cancer care far from home

    Specialized Care May Be Far From Home

    Transportation, lodging, meals, and parking may become part of the cost.

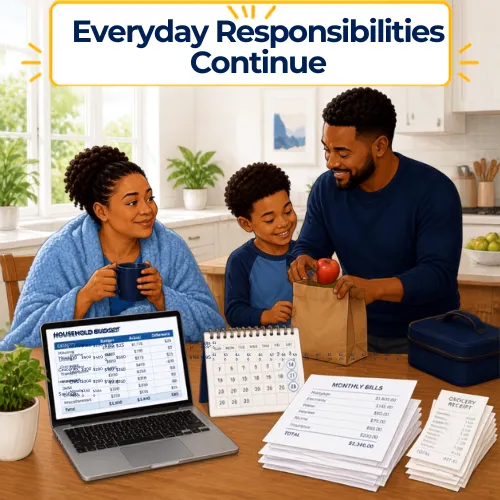
  • Illustration of everyday household responsibilities continuing during cancer treatment

    Everyday Responsibilities Continue

    Groceries, childcare, pet care, utilities, and housing expenses continue during treatment.

How Cancer Insurance Works

Cancer insurance is designed to provide supplemental financial support during different stages of a cancer-related experience.

Depending on the policy, benefits may be available for preventive screenings, a covered diagnosis, treatment, recovery, or other qualifying events. Some policies pay fixed benefits directly to the policyholder. Others pay scheduled or expense-based benefits according to the policy terms.

The exact benefits, eligibility rules, waiting periods, exclusions, and claim requirements vary by insurer, policy, state, and applicant health history.

Here is how the process may work.

Some cancer coverage plans pay a stated wellness or screening benefit when the insured completes a covered test. This benefit is not necessarily reimbursement for the full cost of the screening, and not every test qualifies.

Depending on the policy, eligible screenings may include:5

  • Mammograms
  • Colonoscopies
  • Prostate and cervical exams
  • Skin cancer checks

What to keep in mind: Screening benefits vary by plan. Check your policy for covered tests, frequency limits, waiting periods, and payout amounts.

Preventive care illustration

Read the transcript

Hey everyone and welcome to today's explainer. We're jumping right into something that is absolutely crucial. Yet honestly, it's something most of us don't really think about until it's right in front of us. Today, our focus is squarely on how a medical diagnosis impacts everyday family finances. We all know health insurance is there to fight the disease, right? But what happens to the mortgage, the groceries, or the electric bill when your world suddenly just turns upside down? In this explainer, we're going to look really closely at the role of cancer insurance, breaking down exactly how it works as a financial shield for your family finances.

Okay, let's dive into this 70%. According to the American Cancer Society, more than 1 in three Americans are expected to face cancer at some point in their lifetime. But here is the genuinely encouraging part of that statistic. About 70% of people diagnosed with cancer now survive it. Medical advancements are absolutely incredible and people are living longer. But, you know, from a financial perspective, this incredible survival rate means that more families are living for months or even years with the ongoing mounting costs of treatment and recovery. Surviving is obviously the goal, but it certainly isn't cheap. I want you to take a second and honestly ask yourself this. If treatment interrupted your income tomorrow, how long could your household continue paying its regular expenses? It's a pretty heavy question, isn't it? It strips away all the abstract ideas of health and zeros right in on the reality of your family finances. Most of us plan for a rainy day, sure, but a serious medical diagnosis can sometimes feel like a financial monsoon.

Moving into section one, the cost of survival. We really need to acknowledge the staggering non-medical financial toll that getting better can take on a family. When we think of medical expenses, we usually just picture hospital bills and doctor co-pays. But the true cost of survival goes way beyond the clinic walls. It spills over into almost every single aspect of your daily life. Now, what's really interesting is the data from the National Cancer Institute. They note that patients may spend a massive share of their income on care. In some cases, we're talking up to 20%. Imagine instantly losing a fifth of your household income to treatment costs, exactly when you need your resources the most. This is what experts call financial toxicity and it really underscores the incredibly heavy economic burden that treatment places directly on family finances.

Let's look at section two, protecting family finances. We are going to examine the specific financial gap that opens up the moment your traditional health coverage reaches its absolute limits. Because look, no matter how great your major medical insurance is, it's designed to fix your body, not your bank account. There are all these hidden costs of getting well. First, income interruption. Your paycheck might stop or shrink if you just can't work. Second, caregiver time away. Often, a spouse or family member has to reduce their own work hours to drive you to appointments or help around the house, hitting the family with a double loss of income. Then there's travel for specialized care. Think gas, hotels, parking, meals away from home. And finally, everyday responsibilities. Things like groceries, child care, pet care, the mortgage. Those bills do not gracefully pause just because someone is sick. Your household expenses keep rolling right alongside your treatment. And this brilliantly illustrates the solution to that gap. Think of your financial defense in terms of two separate pockets. On the left, you have your traditional health insurance. Its job is to pay the doctors and hospitals directly to treat the disease. But on the right, you have supplemental cancer insurance. This is an entirely different beast. It pays cash directly to you, not the hospital. And that cash can be used for what you need to protect everything else in your life, from covering your deductibles all the way down to your grocery bill.

Up next is section three, how the shield works. Let's break down the actual mechanics of supplemental coverage so you can see exactly how families use these policies as an active shield when things get really tough. There are generally three distinct structures of supplemental insurance out there, and they are definitely not interchangeable. First, standalone cancer insurance focuses specifically on covered cancer. It's triggered by a diagnosis or treatment and can pay out in a lump sum, scheduled benefits, or sometimes both. Next, critical illness insurance is broader. It might cover cancer, sure, but also heart attacks and strokes, paying out a contract defined lump sum when an illness occurs. Finally, hospital indemnity insurance is based strictly on hospital care. It's triggered by an admission and pays daily or scheduled benefits regardless of what the illness actually is. Understanding these specific triggers is the very first step in building the right shield for your family. Now, if you opt for a standalone cancer policy, the breadth of what it can cover is actually pretty impressive. Just to ground our explainer in a real world example, we can look at a 14-point list from a Mutual of Omaha policy. It ranges from preventative screenings, hospital rooms, and intensive care, all the way up to heavy treatments like radiation, chemotherapy, and immunotherapy. But it also includes covered surgeries, follow-up visits, home health, and hospice care, and even the cost of an ambulance ride. It's essentially designed to provide financial support across the entire timeline of the illness.

Moving right along to section four, claiming your benefits. Having a shield on paper is one thing, but we need to shift our narrative to the practical reality of how this money actually works. Like how does a family access these funds when tragedy strikes and they need cash fast? Let's see how this builds into a logical step-by-step process. First, you contact the insurer or your licensed agent to request the forms. Step two, you gather your documentation, things like your pathology report and physician statement. Step three, the insurer reviews the claim against the terms of your policy. And finally, step four, if approved, the benefit is paid directly to you according to your policy's payment provisions. Basically, you keep records of your expenses and the insurance company provides the supplemental cash to help cover them. Naturally, you're probably wondering right now, okay, how much does a shield like this actually cost? Well, according to industry guides, average cancer insurance rates generally fall between 20 and 90 dollars a month. Now, keep in mind that is a general benchmark, not a guaranteed quote. Your exact premium is going to depend on things like your age, your health history, the benefit amount you choose, and the specific design of the policy. But for a lot of families, protecting their finances falls comfortably within the cost of just a couple of takeout dinners a month.

And that brings us to section five. Is it right for you? We've learned what cancer insurance is and how it functions, but you need to determine if taking out this specific financial shield makes logical sense for your unique household and your budget. I really want to share an incredibly sobering story from Aaron Polk, the founder of Golden Shield Life Insurance, who provided our source material today. He wrote, "Years ago, I declined supplemental coverage. 28 days later, an accident left me completely paralyzed, and I could not reconsider that decision after my life had changed." While Aaron's specific crisis wasn't cancer, his experience completely grounds this explainer in reality. It is just such a powerful reminder of how incredibly fast a steady, predictable life can change without any warning whatsoever. So, if you fall into any of these vulnerability categories, you should strongly consider looking into coverage. Do you have a high deductible health plan? Do you have limited emergency savings to weather a sudden storm? Are you self-employed, meaning if you stop working, the money literally stops completely? Do you rely on a family caregiver whose income would also be impacted? Or would you likely face out of town travel for specialized treatment? If you're nodding along to any of these points, your family finances might be exposed. So, the crucial point is this. If you decide to explore coverage, you absolutely must compare the fine print of the contract, not just look at the monthly price tag. You need to know the exact covered diagnosis and the rules on cancer recurrence. You've got to understand your benefit limits, any waiting or probationary periods before coverage kicks in, and exclusions for pre-existing conditions. And hey, don't forget portability. Can you actually take this policy with you if you leave your current job? The details matter deeply when you're protecting your family finances.

I want to leave you with this powerful final thought, a question posed by Aaron Polk himself. Your shield is ready. Are you? It's a provocative question meant to inspire you to evaluate your own family's financial preparedness. Look, we all hope we never need to face a major illness, but hope is not a financial strategy. Understanding your tools, reviewing your household's exposure, and making informed choices is how you truly protect what matters most. Thank you so much for joining me for this explainer, and I highly encourage you to take a close look at your own financial shield today.
Hi, I am Aaron. Click to call Golden Shield Life Insurance at 678-884-4653

What Happens After You File a Claim?

If you believe you have experienced a covered event, contact the insurer or your licensed agent and request the claim instructions. The steps below show how the process generally moves.

People helping families through cancer treatment and diagnosis
Benefits are paid to you, not the hospital.
  1. Contact the insurer or your agent

    Request the claim form and instructions for your policy. Your licensed agent can help you confirm what the carrier expects and where to send it.

  2. Gather the documentation

    You may need to provide:

    1. Your policy number
    2. The date of the diagnosis or treatment
    3. A physician’s statement
    4. Pathology or laboratory records
    5. Treatment records
    6. Proof of eligible expenses, if required
    7. Any additional documentation requested by the insurer

    Tip: Keep copies of all documents you submit and record your communications with the insurer.

  3. The insurer reviews the claim

    The insurer reviews the claim against the policy’s terms. A policy does not guarantee that every claim will be approved.

  4. The benefit is paid according to the policy

    If the carrier approves the claim, it pays the applicable benefit according to the policy’s payment provisions. Documentation requirements and payment timing vary by carrier and contract.

How Can You Use the Benefits?

If the policy pays benefits directly to you without restricting how the money is used, the benefit may help with financial needs such as:

  • Medical deductibles and copayments
  • Transportation and lodging
  • Groceries and household bills
  • Mortgage or rent payments
  • Expenses during time away from work
  • Childcare, eldercare, or pet care
  • Home modifications
  • Recovery-related expenses

The permitted use of benefits depends on the policy structure. Some benefits may be unrestricted cash, while others may be tied to specific covered services or documented expenses.

This coverage does not replace health insurance. It is designed to provide an additional layer of financial support when a covered diagnosis or treatment event affects your household.

How Much Does Cancer Insurance Cost?

Cancer insurance may cost about $20 per month in your 30s, $40 in your 40s, $60 in your 50s, and $90 in your 60s. Your actual premium depends on your age, health and tobacco history, location, benefit amount, policy type, optional riders, and whether rates remain level or increase over time.2

Choosing the Right Coverage Amount

Your benefit amount or coverage should cover the financial gap that health insurance, savings, and workplace benefits leave out.

Estimate Your Gap Exposures by Examining:

  • Your remaining deductible, copays, coinsurance, prescriptions, and other eligible expenses.
  • Household expenses, such as mortgage or rent, utilities, groceries, childcare, pet care, and help at home.
  • Income interruption from time away from work for the patient or a family caregiver.
  • Treatment-related travel, including transportation, lodging, meals, and extended stays near a specialized treatment center.

Pros and Cons of Cancer Insurance

Advantages and disadvantages of cancer insurance
AdvantagesDisadvantages
Use the money where you need it. Benefits paid directly to you can help with medical bills, groceries, childcare, travel, lodging, or other everyday expenses.It only covers cancer. It does not provide benefits for heart attacks, strokes, or other unrelated illnesses.
Keep more of your savings intact. The extra money can reduce the need to rely on savings, credit cards, retirement accounts, or personal loans.Coverage has rules and limits. Waiting periods, maximum benefits, exclusions, and covered treatments vary by policy.
Help with the cost of treatment. Depending on the plan, benefits can be available for screenings, chemotherapy, radiation, surgery, hospital stays, and follow-up care.Not everyone will qualify. A previous cancer diagnosis or certain health conditions can affect eligibility.
Extra support beyond health insurance. Cancer insurance can help fill financial gaps left by deductibles, copays, missed work, and nonmedical expenses.You may already have some coverage. Health, critical illness, disability, or workplace insurance could cover part of the same financial need.

Cancer insurance is not designed to replace health insurance. It provides an additional layer of financial support when cancer treatment affects more than medical bills.

Who Should Consider Cancer Insurance?

Standard health insurance pays hospitals. Cancer insurance pays you cash to help cover hidden costs like lost paychecks, high deductibles, and travel.

You should consider coverage if you:

  • Have a high deductible. Benefits can help cover $3,000 to $8,000 or more in out-of-pocket health costs.
  • Are self-employed. Benefits can help replace missed paychecks during treatment and recovery.
  • Travel for care. Benefits can help pay for lodging, gas, and out-of-network specialists.
  • Rely on a family caregiver. Benefits can help offset a spouse’s reduced work hours.

Note: Approval is based on your individual medical history, not your family history.

How to Get Covered

Through Your Workplace

Some employers offer cancer insurance as an optional benefit paid through payroll deductions. It can be convenient, but find out whether you can keep the coverage if you leave your job or retire.

With Your Own Policy

Recommended for portability

An individual policy is purchased outside of work and stays with you when you change jobs, as long as the policy remains active and premiums are paid.

Health Insurance Does Not Cover Every Cost

Health insurance may help pay for treatment, but life at home does not stop during cancer care. Your mortgage, groceries, utilities, childcare, travel expenses, and other household bills still have to be paid. Time away from work can also affect your income, or the income of the person caring for you.

Cancer insurance may provide cash benefits that can be used for these expenses, subject to the policy’s terms. Before buying a policy, make sure you understand:

  • What diagnosis or treatment activates the benefit
  • Whether benefits are paid as a lump sum or by individual service
  • Any waiting periods, exclusions, or payout limits
  • Whether you can keep the policy after changing jobs

Get a Free Cancer Coverage Review

Cancer insurance is not necessary for everyone. The right decision depends on your health coverage, savings, workplace benefits, household expenses, and budget.

Golden Shield Life Insurance will help you review what you already have, compare available options, and understand what each policy actually pays. If your existing coverage is enough, we will tell you. If there is a meaningful gap, we will explain your choices without pressure.

Aaron Polk, founder of Golden Shield Life Insurance

Expert Advice

I know how quickly an unexpected medical event can change your health, your work, and your responsibilities at home. You do not get to test-drive insurance after something happens. My goal is simply to help you understand your options while you still have them.

Aaron Polk, Founder, Golden Shield Life Insurance
Cancer Policies

Ready to experience Golden Shield Life Insurance?

Compare cancer insurance quotes and get a complimentary policy review from home, online or by phone. No cost, no obligation.

GET QUOTE
Common Questions

Cancer Insurance FAQs

What does cancer insurance cover?

This coverage pays benefits when a diagnosis, treatment, or service meets the policy’s requirements. Depending on the contract, benefits may include a lump sum after an eligible diagnosis or scheduled amounts for covered screenings, chemotherapy, radiation, surgery, hospital stays, and follow-up care. If the benefit is paid directly to you without spending restrictions, you may use it for deductibles, copayments, travel, household bills, or expenses during time away from work. Coverage and payment amounts vary by policy. It supplements health insurance; it does not replace it.

What are the eligibility requirements for cancer insurance?

Eligibility depends on the carrier, policy, applicant’s age and health history, state, and answers to the application questions. A prior diagnosis, recent treatment, follow-up testing, or other medical history may affect approval, exclusions, waiting periods, or available benefits. Some policies ask about specific time periods, while others use different underwriting rules. Do not assume that every company evaluates the same history the same way. A licensed agent can help you review available options, but only the insurer can determine eligibility and issue coverage.

What are the benefits of cancer insurance?

The primary benefit is additional financial support after a covered event. Depending on the policy, benefits may be paid as one lump sum, scheduled amounts for covered treatments and services, or a combination of payments. Money paid directly to the insured without expense restrictions may help with medical cost-sharing, housing, groceries, childcare, treatment-related travel, or expenses during time away from work. These benefits may reduce reliance on savings or credit, but the contract determines what triggers payment, how much is paid, and when benefits end.

How do you choose a cancer insurance policy?

Start with your health plan’s deductible and out-of-pocket limit, paid leave, emergency savings, and any workplace cancer or critical-illness coverage. Then estimate the financial gap a diagnosis could create. Compare each policy’s definition of covered cancer, benefit trigger, payment structure, waiting period, recurrence rules, exclusions, maximums, renewal terms, and workplace portability. Family history may be a reason to review coverage early, but it does not determine eligibility. Golden Shield Life Insurance can compare available policies and riders from multiple carriers and explain how they differ.

What are the limitations of cancer insurance?

Cancer insurance is limited-benefit coverage for specified conditions or events. It generally does not pay for unrelated illnesses and is not a substitute for comprehensive health insurance. Policies may include waiting periods, pre-existing-condition provisions, exclusions, recurrence rules, treatment-specific limits, and total benefit maximums. Certain skin cancers, precancerous conditions, early-stage diagnoses, or related conditions may be defined or paid differently. Fixed benefits may not cover every expense. Read the outline of coverage and policy carefully before applying, because definitions, limitations, and availability vary by carrier and state.7

What Our
Clients Say

Atlanta SkyView Ferris wheel Georgia State Capitol gold dome in Atlanta
“
I was searching for term life insurance in Atlanta and found Golden Shield Life Insurance. Aaron explained term versus whole life clearly and gave me multiple quotes. The rates were affordable and I left feeling confident.
MICHAEL BLASCO
Read More Reviews

Reviews reflect individual experiences with Golden Shield Life Insurance and may involve other insurance products. They do not guarantee eligibility, pricing, coverage, or claim outcomes.

Aaron's Closing Thoughts

We believe every family deserves a shield.

This coverage cannot change a diagnosis, but the right policy may provide financial support when treatment affects your health, income, savings, and daily life.

My hope is that this guide helps you understand your options, ask better questions, and decide whether cancer insurance belongs in your financial plan.

Aaron Polk

Founder, Golden Shield Life Insurance

Your shield is ready. Are you?

Request a complimentary cancer insurance quote and coverage review. No cost, no obligation.

Thank you. Your request is in. A licensed agent at Golden Shield Life Insurance will reach out shortly to review your coverage and share available supplemental options for which you may qualify.

Disclaimers

Aaron Polk, founder and licensed agent at Golden Shield Life Insurance

Aaron Polk

Founder and Licensed Life Insurance Agent and Broker, Golden Shield Life Insurance · NPN 21216745 · Georgia Agency License 242517

Aaron founded Golden Shield Life Insurance because he believes every family deserves a shield from financial hardship. He built an agency and brokerage that gives clients choices and options that can be taught and quoted from the comfort of home, online and by video. He shows clients everything they qualify for and helps them compare rates, benefits, and coverage options in person, online, or over the phone.

Why we wrote this guide. We wish more people knew about cancer insurance before a diagnosis, not after. Once cancer is diagnosed, it is usually too late to buy a new policy that covers it. We believe that if more families understood this coverage in advance, fewer would face bankruptcy or foreclosure while fighting for their health. One study found that people diagnosed with cancer in Washington state were 2.65 times more likely to file for bankruptcy than people without cancer.10

Last reviewed: November 2026. This page is reviewed and updated as products, state rules, and carrier practices change.

Disclaimers View

Facts on This Page Are Supported By

  • Mutual of Omaha Insurance Company. Supplemental Cancer Insurance consumer brochure, form 463530, policy form CL10-22900 or state equivalent, with state-specific benefit pages. Supports the 14 covered costs listed on this page and this is a limited health benefit policy that supplements health insurance and is not a substitute for major medical coverage; that eligibility is determined by the answers on the application and coverage begins on the policy date after the premium is received and the application is approved; that cancer first diagnosed within 30 days of the effective date is not covered, with state exceptions such as New Jersey; that the policy definition of cancer excludes precancerous conditions such as leukoplakia, hyperplasia, polycythemia, benign moles, and similar lesions; that benefits are not paid for diagnoses or expenses while the person is not insured under the policy; that applicants must be free of internal cancer, leukemia, or melanoma for five years and other skin cancer for three years; that premiums are intended to remain level and change only by class; that not all benefits and riders are available in all states; and that an insured may hold only one cancer plan from that company. Accessed September 2026. Brochure 463530 (PDF) · mutualofomaha.com
  • Mutual of Omaha. "Is a Cancer Insurance Policy Worth It?" Reviewed by Dr. Manoj Pawar, Chief Medical Officer. Published August 14, 2025. Supports the $20 to $90 monthly cost benchmark, that rates rise with age, and the distinction between benefits paid at diagnosis and benefits paid for treatment. mutualofomaha.com/advice
  • American Cancer Society. Cancer Facts and Figures 2026. Supports the statements on this page that more than 1 in 3 Americans are expected to face cancer in their lifetime, that the five-year relative survival rate is about 69 to 70 percent, and that more people are living longer after diagnosis. Atlanta: American Cancer Society; 2026. cancer.org
  • National Cancer Institute. "Financial Toxicity (Financial Distress) and Cancer Treatment." Supports the non-medical financial impact of a diagnosis, including lost income, travel, and household costs, and the statement that patients may spend a large share of their income on care. Accessed September 2026. cancer.gov
  • American Cancer Society. Cancer Screening Guidelines. Supports the screening examples on this page, including mammograms, colonoscopies, prostate and cervical exams, and skin checks. Whether a screening pays a policy benefit depends on the contract. Accessed September 2026. cancer.org/cancer/screening
  • National Insurance Producer Registry and Georgia Office of Insurance and Safety Fire Commissioner. Producer and agency license lookup. Supports verification of Golden Shield Life Insurance, Georgia Agency License 242517, and Aaron Polk, NPN 21216745. Accessed September 2026. nipr.com · oci.georgia.gov
  • NAIC, National Association of Insurance Commissioners. Consumer resources on supplemental and specified-disease coverage and the directory of state insurance departments. Supports that policy rules and availability are regulated state by state. Accessed September 2026. content.naic.org
  • Internal Revenue Service. Publication 525, Taxable and Nontaxable Income. Supports the general rule that benefits from accident or health coverage you paid for with after-tax dollars are generally not taxable, while employer-paid coverage may be treated differently. Accessed September 2026. irs.gov/publications/p525
  • AM Best. Insurer financial-strength rating lookup. Supports the carrier rating standard referenced on this page and checking a carrier's ability to pay claims. Accessed September 2026. ambest.com
  • Health Affairs. Ramsey SD, et al. "Washington State Cancer Patients Found To Be At Greater Risk For Bankruptcy Than People Without A Cancer Diagnosis." Health Affairs 2013;32(6):1143-1152. Supports the statement that people diagnosed with cancer were 2.65 times more likely to file for bankruptcy than people without cancer, that younger patients had the highest rates, and that the authors pointed to supplemental policies paying fixed sums as one way to help with first-year household and out-of-pocket costs. Accessed November 2026. healthaffairs.org

Disclaimers

  • Cancer insurance, critical illness insurance, and hospital indemnity insurance use different benefit triggers and are not interchangeable. They supplement rather than replace comprehensive health insurance. Benefits, definitions, exclusions, waiting periods, underwriting, premiums, and availability vary by policy, carrier, and state.
  • This page is educational and is not medical, financial, legal, or tax advice.
  • Cancer insurance is limited-benefit supplemental coverage. It is not major medical insurance, Medicare Supplement insurance, or disability insurance, and it does not satisfy the federal minimum essential coverage requirement.
  • Benefits are paid only when a diagnosis, treatment, or service meets the definitions and requirements in the issued policy. Precancerous conditions, certain skin cancers, early-stage diagnoses, and recurrences may be paid differently or excluded.
  • Waiting or probationary periods, pre-existing-condition provisions, benefit limits, and availability vary by carrier, policy, and state. A diagnosis before the effective date or during a probationary period may not qualify.
  • Golden Shield Life Insurance is an independent agency and broker. It does not underwrite or issue policies and does not guarantee approval, pricing, or benefit eligibility. The issuing insurance company is solely responsible for its policy obligations and approved claims.
  • Not all benefits and riders are available in all states. Carrier-specific rules, such as a limit of one cancer policy per insured, apply only to that carrier. Cost figures cited are published benchmarks, not quotes.
  • Tax treatment of benefits depends on how premiums were paid and may change. Consult a qualified tax professional.
  • This page is a solicitation of insurance. By requesting information, you may be contacted by a licensed agent or producer. If information on this page differs from the issued policy, the policy controls.