Life Insurance Agency
No cost, no obligation. No-exam options may be available for qualified applicants.
Compare life insurance options from multiple carriers for death benefits, living benefits, cash value, and long-term financial needs. Golden Shield Life Insurance is an independent life insurance agency and broker. We help you decide what you want the coverage to do, compare available insurance companies and policy types, and work through the application and underwriting process.
No cost, no obligation. No-exam options may be available for qualified applicants.
Aaron Polk
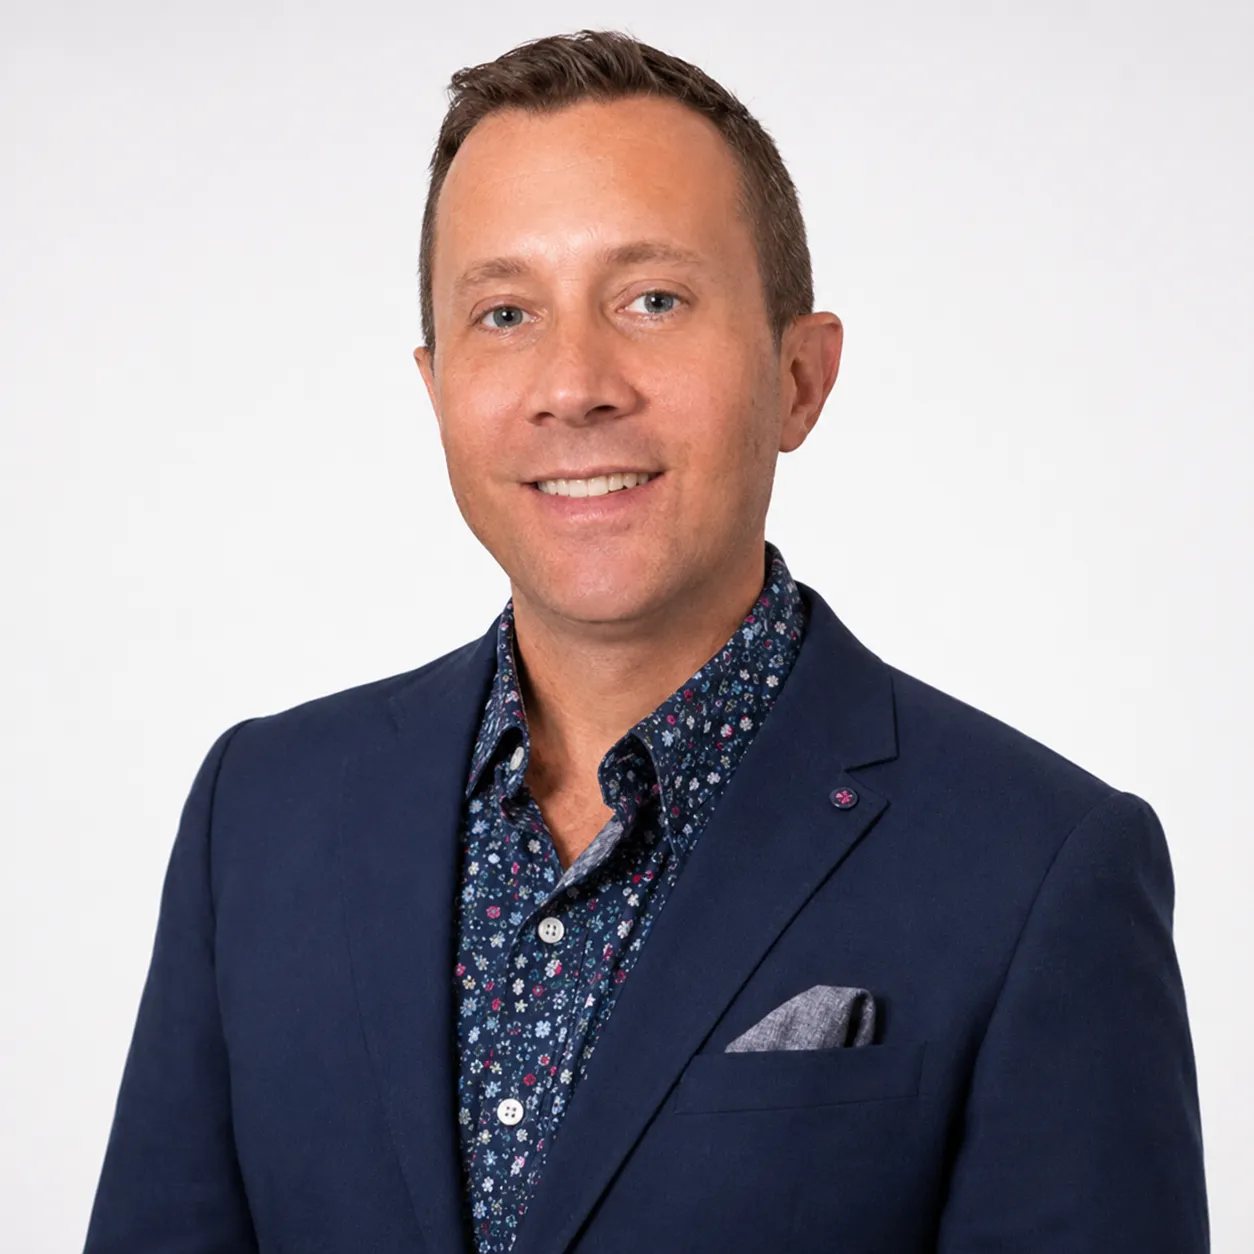
Aaron Polk, CEO and founder of Golden Shield Life Insurance, helps individuals and business owners secure custom life insurance, mortgage protection, and income replacement strategies.
Connect on LinkedIn
Compare life insurance companies in Georgia with Aaron Polk, in person at our Atlanta office on Airport Rd or by phone and video anywhere in the state.
Short term disability insurance in Arizona can replace part of your paycheck while you recover from a covered illness or injury. Aaron Polk compares benefit amounts and waiting periods for you.
Life insurance in California, from term coverage for young families to permanent policies for retirement and legacy planning, compared across top-rated carriers by phone or video.
Mortgage protection insurance in Florida helps your family keep the home if you pass away. Aaron Polk compares term and permanent options sized to your mortgage balance.
Life insurance in Michigan for families, seniors and business owners. Aaron Polk compares term, whole life and no-exam options so you can choose with confidence.
Short term disability insurance in Missouri can pay a weekly benefit when a covered illness or injury keeps you off work. Compare benefit amounts, waiting periods and costs.
Life insurance in Ohio, compared across more than 130 carriers rated A- or better by AM Best, so you can find the right coverage amount for your budget.
Short term disability insurance in South Carolina helps cover your bills while you recover from a covered illness, injury or surgery. Aaron Polk helps you compare plans.
Burial insurance in South Dakota helps your family pay for funeral costs and final bills. Compare small whole life policies, most with premiums that stay level for life.
Life insurance in Tennessee for every stage of life, from term coverage while your children are young to whole life and final expense coverage later on.
Term life insurance in Texas covers you for 10, 20 or 30 years at a level premium. Aaron Polk compares rates and no-exam options from top-rated carriers.
Life insurance in West Virginia, including term, whole life and guaranteed issue options, explained in plain language by phone or video.
Golden Shield Life Insurance is nationwide, with licensed agents in every part of the USA. Call or text (678) 884-4653 and we will connect you with a licensed agent in your state.
.webp)
Aaron Polk, NPN 21216745. Verify any license through the NIPR license lookup.
Policy type definitions on this page follow consumer guidance from the National Association of Insurance Commissioners.1 Numbered references link to the full source list at the bottom of this page.
Life Insurance can provide a death benefit and help with income replacement, debt, final expenses, mortgages, legacy planning, and other financial needs.
See How Life Insurance WorksTerm Life Insurance provides coverage for a set period and is often used for income replacement, mortgages, debt, education costs, and other temporary needs.
Commonly used for: Income replacement, mortgages, debt, education, and other temporary needs.
Compare Term LengthsWhole Life Insurance provides permanent coverage with level premiums and cash value that grows according to the policy.
Commonly used for: Final expenses, permanent coverage, legacy planning, and long-term cash-value needs.
How Whole Life Builds ValueFinal Expense Insurance is smaller permanent coverage designed to help with funeral costs, burial or cremation, medical bills, and other final expenses.
Commonly used for: Funeral costs, burial or cremation, medical bills, and other final expenses.
Plan for Final ExpensesBurial Insurance is a common name for smaller permanent policies designed mainly for funeral, burial, cremation, and related expenses. The death benefit is generally paid to the named beneficiary rather than directly to a funeral home.1
Commonly used for: Burial or cremation, funeral costs, final medical bills, and small remaining debts.
What Burial Coverage Pays ForCash Value Life Insurance refers to permanent policies that may build value inside the policy over time. Growth is usually slow in the early years, and loans or withdrawals may reduce the death benefit.1
Commonly used for: Permanent coverage, long-term planning, policy loans, and legacy goals.
Price a Cash Value PolicyIndexed Universal Life Insurance is permanent coverage with flexible features and cash-value interest crediting tied in part to an external market index.
Commonly used for: Permanent coverage, cash-value planning, legacy goals, and certain long-term financial strategies.
How IUL Interest Crediting WorksGuaranteed Universal Life Insurance focuses mainly on providing a long-term death benefit with less focus on building cash value.
Commonly used for: Long-duration death-benefit needs with less emphasis on cash-value growth.
Request a Guaranteed Universal Life QuoteMortgage Protection Insurance uses life insurance to help with a mortgage, monthly housing costs, income replacement, or related household debt.
Commonly used for: Mortgage payoff, housing payments, income replacement, and related household debt.
Protect Your Home and MortgageNo Exam Term Life Insurance may allow qualified applicants to apply without a traditional medical exam. The insurance company may still review health questions, prescriptions, medical records, or other underwriting information.8
Check No Exam Term Eligibility
Return of Premium Term Life Insurance may return eligible premiums if you outlive the policy term and the policy requirements are met.
Same Day Life Insurance refers to faster underwriting options that may give some qualified applicants a quick decision. The actual timing depends on the insurance company, policy, and application.8
Guaranteed Issue Whole Life Insurance may be available without a traditional medical exam or full medical underwriting. Some policies may include a graded death benefit during the early policy years.1
How Guaranteed Acceptance Works
Limited Pay Whole Life Insurance lets you pay premiums over a shorter period while keeping permanent coverage if the policy requirements are met.
Children's Whole Life Insurance provides permanent coverage for a child and may include level premiums, cash value, and future coverage options.
Coverage for Families and Children
Life Insurance With Living Benefits may allow you to access part of your death benefit while you are still alive after certain qualifying health events.
Depending on the policy, living benefits may be available for a qualifying terminal illness, chronic illness, or critical illness. These benefits are not included with every policy and can vary by insurance company.1
See Which Illnesses May Qualify
Accidental Death and Dismemberment Insurance provides benefits after certain qualifying accidental deaths or serious accidental injuries.
Group Life Insurance provides coverage to eligible people in a group, such as employees or members of an organization.
Customized Life Insurance Policies allow coverage to be built around different policy types, benefit amounts, riders, term lengths, and underwriting options.
Life insurance can be sized around personal loans, credit cards, business debt, and other financial obligations that may remain after death.
Key Person Life Insurance is coverage a business owns on an owner, partner, or employee whose loss would create a financial strain. The business is generally the owner and beneficiary, and the benefit may help cover lost revenue, recruiting costs, or debt while the company recovers.
A buy-sell agreement sets out what happens to an owner's share of a business if that owner dies. Life insurance is commonly used to fund it, so the remaining owners may have money available to purchase the departing owner's interest rather than selling assets or taking on debt.
A policy review looks at coverage you already own. We go through the coverage amount, policy type, premium, riders, and beneficiaries, and compare what you have with what is currently available. There is no cost and no obligation, and sometimes the answer is that the policy you have still fits. We also follow the guidance from the Georgia Office of Insurance and Safety Fire Commissioner not to cancel existing coverage until a new policy has been issued and reviewed.2
Credit Life Insurance is designed to pay a specific debt after the insured person dies.
Golden Shield Life Insurance helps clients compare life insurance options across the United States through our licensed team and carrier network, drawing on more than 130 carriers rated A- or better by AM Best.6
GeorgiaHeadquarters
Agency License #242517
Florida
License #G256256 View License
Texas
License #3344114
South Carolina
License #21216745 View License
Arizona
License #21216745 View License
California
License #4423192
Ohio
License #1663225 View License
Michigan
License #21216745
West Virginia
License #21216745 View License
South Dakota
License #21216745 View License
Missouri
License #3004531756 View License
Tennessee
License #3004531734 View License
Additional states served through our licensed team
Insurance availability and licensing vary by state, carrier, product, and agent. You can confirm that anyone offering you a policy is licensed in your state before sharing personal or financial information.3
Looking for a policy a relative may have left behind? The NAIC Life Insurance Policy Locator is a free national search tool. There is no cost to use it and no need to contact us first.11
“Aaron Polk is the best. He listens, explains everything clearly, and truly cares about helping his clients. I highly recommend him.”
Priscilla Stephens
Verified Google Review
A walkthrough of the main policy types, what drives cost, and how to use the DIME method to size your coverage.
Let's just be real for a second. A cookie-cutter approach to protecting your family does not work, because life insurance needs can differ massively from one person to another.
Today we are diving straight into the often overwhelming world of life insurance, using insights provided by Golden Shield Life Insurance so you can walk away with much more clarity. Here is the roadmap. First, why life insurance is not just a death benefit. Second, how to pinpoint your specific need. Third, how to figure out how much coverage you may need. Fourth, how to match different types of policies to those needs. And finally, how to choose the right life insurance agency.
Life insurance is more than a death benefit. Most people think of life insurance as a payout that happens when someone dies. Replacing income, paying off a mortgage, covering debts, and leaving money behind for family are certainly important reasons people buy coverage. But depending on the policy, life insurance may also provide benefits while you are still alive.
Certain policies include living benefits, which may allow you to access a portion of the death benefit after a qualifying critical, chronic, or terminal illness. Some permanent life insurance policies can also build cash value. Depending on the policy and how it is structured, that cash value may be accessed through withdrawals or policy loans and potentially used as supplemental retirement income later in life. That means life insurance can serve more than one purpose.
Start with your specific need. If you remember one thing from this explainer, remember this. Start with the need. Before comparing policies, decide what you actually want the coverage to accomplish.
Consider a 30-year-old homeowner with a large mortgage and young children. That person may need a significant amount of temporary coverage designed to replace income and help cover a mortgage for the next 20 or 30 years. Now compare that with a 75-year-old homeowner who has already paid off the house and primarily wants money available for funeral, burial, and other final expenses. Those are two completely different needs. Trying to fit both people into the same type of life insurance policy would not make much sense.
How much life insurance do you need? Once you understand the purpose of the coverage, the next step is putting an actual number behind it. One common starting point is the DIME method. DIME stands for debt, income, mortgage, and education.
Start by adding your outstanding debts. Then consider how much income your household may need to replace and for how many years. Add your remaining mortgage balance. Then include future expenses such as education or childcare. Once you have that total, subtract savings, investments, and any existing life insurance coverage that would already be available. What remains can help identify your potential life insurance coverage gap. It is not a perfect formula for every situation, but it gives you a much stronger starting point than simply guessing at a coverage amount.
Matching policies to your needs. Once you know what the insurance needs to accomplish, you can begin looking at different policy types. Term life insurance provides coverage for a specific period, such as 10, 20, or 30 years. It is commonly used for temporary financial obligations such as mortgages, income replacement, raising children, or business debt. Whole life insurance is designed to provide permanent coverage and may build cash value over time. It can be used for permanent needs such as estate planning, legacy planning, final expenses, or other long-term goals. Final expense insurance is generally a smaller permanent life insurance policy designed primarily to help cover funeral, burial, medical, and other end-of-life expenses.
There are also different underwriting options available. Depending on your age, health, coverage amount, and the insurance company, you may qualify for accelerated underwriting or no-medical-exam coverage. In other situations, completing a medical exam and going through full underwriting may actually result in more competitive pricing, particularly for larger policies and healthier applicants. Another option available from certain carriers is return-of-premium term life insurance. With these policies, eligible premiums may be returned if you outlive the specified term, subject to the policy's terms and conditions.
Choosing the right life insurance agency. The life insurance industry uses a lot of terms that can sound similar, including agency, carrier, broker, and agent. Here is a simple way to understand the difference. The life insurance company, also called the carrier, creates and issues the insurance policy. The carrier handles underwriting, manages the policy, and is responsible for paying eligible claims according to the contract. A life insurance agency helps consumers understand coverage, compare available policies, complete applications, and navigate the underwriting process.
However, not every agency works the same way. A captive agency generally represents one insurance company and primarily offers that company's products. An independent life insurance agency can work with multiple insurance companies and compare available options across different carriers. Golden Shield Life Insurance operates as an independent life insurance agency.
That matters because underwriting guidelines and pricing can vary significantly between insurance companies. One carrier may view a particular medical condition differently than another. The same person can potentially receive different rates, underwriting decisions, and policy options depending on the carrier.
Golden Shield founder Aaron Polk is a former medical underwriter, and his approach is based on understanding the person first rather than starting with a particular policy. The goal is not to push one product. It is to help you understand the available options and make a decision that fits your needs, health history, age, budget, and long-term goals.
The life insurance process. Golden Shield Life Insurance breaks the process into four straightforward steps. Step one, identify your goal. Step two, compare available carrier and policy options. Step three, complete the application and underwriting process. Step four, review the final offer before accepting the policy. This needs-first approach is designed to avoid forcing every person into the same one-size-fits-all life insurance solution.
Final thoughts. Life insurance can be much more than a simple death benefit. It can help replace income, address mortgage obligations, provide money for education or final expenses, and, depending on the policy, provide access to living benefits or cash value during your lifetime. The important part is determining what you need the policy to accomplish before choosing the product.
Try running your own DIME calculation. Add your debts, income replacement needs, mortgage, and education costs. Then subtract the financial resources you already have. What is your actual coverage gap? Once you know that number, you are in a much better position to compare policies and determine what type of life insurance may make sense for you.
More Ways We Can Help
These are the coverage types, riders, and planning services Golden Shield Life Insurance can compare for you across our carrier network. If you are not sure which one fits, that is what the first call is for.
Availability, pricing, underwriting, riders, and exclusions vary by carrier, state, product, and applicant. No-exam options may be available for qualified applicants.
Level term generally holds the same death benefit and the same premium for the term you choose. Contract terms and renewal options vary by carrier.
A 10-year term may fit a shorter obligation such as a business loan, the last stretch of a mortgage, or a defined income need.
A 15-year term may fit a set debt, a remaining mortgage period, or an education timeline that ends on a known date.
A 20-year term is often used for a mortgage, the child-rearing years, debt repayment, or income replacement during peak earning years.
A 30-year term may fit a long mortgage, young children, or an income need that runs well into the future.
A 40-year term may fit a longer mortgage or a younger family. Availability, issue ages, and pricing vary by carrier.
Some term policies allow eligible coverage to be converted to permanent coverage without new medical evidence, subject to carrier deadlines and policy rules.
Renewal may allow coverage to continue after the initial term. The renewal premium, how long it can run, and your available choices depend on the contract.
Simplified issue uses health questions and other underwriting information in place of a paramedical exam. Available coverage amounts and eligibility vary.
Accelerated underwriting may use health questions, prescription history, and other data to reach a decision without a traditional exam for qualified applicants.
Universal life is permanent coverage with flexible premiums and an adjustable death benefit. Policy charges, funding, and lapse provisions should be reviewed closely.
Participating whole life may be eligible for dividends based on carrier results. Dividends are not promised and can change from year to year.
A 20-pay design calls for premiums over 20 years rather than for life. Premiums are generally higher because payment happens over fewer years.
Some whole life policies allow a loan against available cash value. Loans accrue interest and may reduce the cash value and the death benefit.
This rider may let an eligible insured person access part of the death benefit after a qualifying condition. Any amount used generally reduces what beneficiaries receive.
Some policies offer riders tied to qualifying critical illnesses. Covered conditions, benefit amounts, cost, and claim rules vary by contract.
Standalone critical illness coverage pays on a covered diagnosis. Compare covered conditions, waiting periods, benefit amounts, exclusions, and state availability.
Disability coverage replaces part of your income if you cannot work. Compare the definition of disability, monthly benefit, waiting period, benefit period, and occupation class.
Mortgage life insurance is built around a loan balance. Some versions pay the lender directly and the death benefit may decline as the balance drops, which is worth comparing against a policy your beneficiaries control.
A standard policy gives your beneficiaries money they can use to pay off or reduce the mortgage, or to keep making the monthly payment instead.
Parents often size coverage around income, childcare, the mortgage, education costs, and household debt during the years a family depends on them most.
Couples may review shared income, the mortgage, joint debts, childcare, and what the surviving spouse would need to keep the household running.
Buying young generally locks in a lower rate while health is at its best. It can matter if you carry debt, co-signed a loan, or expect a family later.
Union or association coverage is worth comparing against an individually owned policy, since group plans may end when membership or employment ends.
Seniors may look at coverage for final expenses, a surviving spouse, remaining debts, or a legacy. Available options depend on age, health, and carrier issue ages.
Veterans can compare individual coverage against VGLI, VALife, and other programs. Eligibility windows and benefit amounts vary by program.
Owners may use life insurance for household income, business debt, key-person planning, buy-sell funding, or succession discussions.
Funeral insurance is another common name for final expense or burial coverage. Compare benefit amounts, waiting periods, and premiums before you apply.
A smaller permanent policy that may help beneficiaries handle funeral, cremation, burial, medical bills, or other final costs.
No-exam options may be available for qualified seniors. Coverage amounts, health questions, waiting periods, and premiums vary by carrier.
Coverage sized to create funds for a funeral, burial or cremation, medical bills, and small debts, so the cost does not fall on family.
No-exam coverage may be available for qualified applicants. Carriers may still review health questions, prescription records, medical records, and application history.
High blood pressure does not automatically rule out coverage. Carriers weigh readings, medications, and overall health differently, which is why comparing them matters.
Compare quotes across available carriers based on your coverage need, age, health, state, and policy type. Final pricing is subject to carrier underwriting.
What you pay depends on coverage amount, policy type and duration, age, health history, tobacco use, riders, state, and underwriting class.
A calculator is a starting point for estimating coverage against debt, income, the mortgage, and education costs. It is not a quote.
Work through income replacement, the mortgage balance, other debts, education goals, existing coverage, and savings to land on a number that holds up.
Compare by purpose, duration, premium, death benefit, cash value, underwriting, riders, exclusions, and beneficiary options rather than by price alone.
The choice usually comes down to how long the need lasts, what you can fund consistently, and whether cash value matters to your plan.
An independent broker compares options across many carriers rather than selling from one company, which matters most when your health history is not straightforward. Premiums are generally the same whether you buy through an agent or directly from the insurance company.
Not seeing what you need? Golden Shield Life Insurance compares more than 130 carriers rated A- or better by AM Best. Call or text (678) 884-4653 and we can tell you what is available for your age, health, and state. No cost and no obligation.
Updated November 2026
Written and Reviewed By
Aaron Polk
Founder, Licensed Life Insurance Agent and Broker, and Former Medical Underwriter, Golden Shield Life Insurance · NPN 21216745 · Georgia Agency License 242517 · Verify this license with the State of Georgia
Aaron founded Golden Shield Life Insurance after someone posing as a representative of the Department of Veterans Affairs nearly talked his father, a retired U.S. Army Green Beret, out of money he had earned. That call is why this agency leads with plain answers and sources you can check yourself. Aaron worked in medical underwriting before becoming an agent, so he reads an application the way a carrier reads it. Golden Shield Life Insurance compares more than 130 carriers rated A- or better by AM Best, with a focus on older applicants and people other agents pass over.
How this page was made: Written by a licensed agent from first-hand casework, not compiled from other insurance websites. Definitions, tax treatment, government benefits, and consumer rights are checked against public guidance from state and federal agencies. Carrier-specific details such as issue ages, riders, underwriting rules, and rates come from current carrier materials and are confirmed at the time of quoting rather than stated as fixed on this page.
Updated: November 2026. This page is reviewed and updated as products, tax rules, licensing, and carrier practices change.