Disability Income Insurance

Disability Insurance: Protect Your Income if You Can't Work

10 min read

Your income pays the bills. Disability insurance helps protect your paycheck when a covered illness or injury keeps you from working. Also called disability income insurance, it may replace part of your earnings with a monthly benefit after a waiting period. It is not the same as Social Security disability, workers' compensation, or supplemental policies such as hospital or critical illness insurance. Your benefit amount, waiting period, length of coverage, and premium depend on the policy, the carrier, your occupation, and underwriting.

Golden Shield Life Insurance can help you compare disability insurance quotes from multiple carriers to find coverage that may fit your income, occupation, and budget.

Licensed & Reviewed Updated · Reviewed by Aaron Polk, Former National Medical Underwriter and Licensed Life Insurance Broker
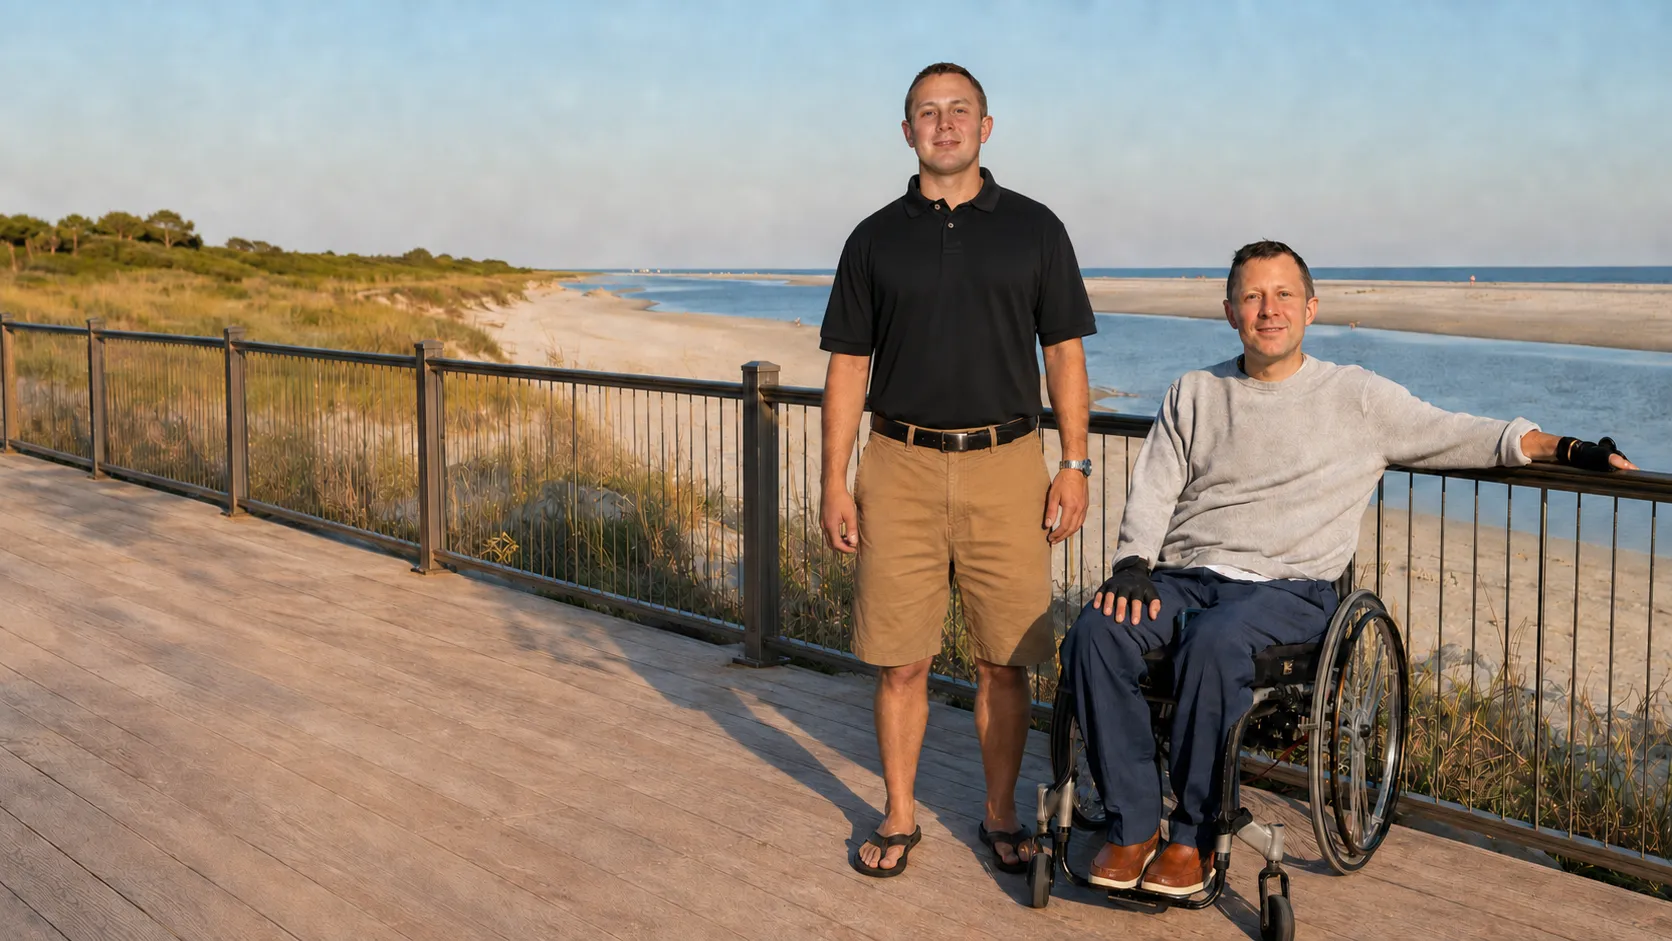
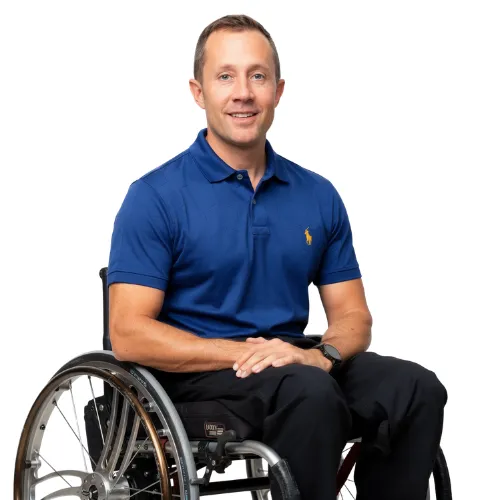
Aaron Polk, founder of Golden Shield Life Insurance, before and after.

Key Takeaways

  • Disability insurance helps protect your income. A qualifying illness or injury can interrupt your paycheck. Disability income insurance can replace part of those lost earnings.
  • Short-term and long-term policies protect you differently. Short-term coverage generally pays for temporary disabilities, while long-term coverage may pay for several years or until a stated retirement age.
  • Your occupation, income, and policy terms matter. The monthly benefit, waiting period, definition of disability, and length of coverage shape both your protection and your premium.
Expert Advice

About 30 days before a life-changing accident, I declined disability coverage because I did not understand its value. Then my paycheck stopped, but my bills did not. Compare more than price by reviewing the disability definition, monthly benefit, waiting period, payment duration, exclusions, and the agent's license before applying.

Search any agent or agency at the national producer license lookup. Run that check on us too. Golden Shield Life Insurance, Georgia Agency License 242517, NPN 21216745.

Hi, I am Aaron. Click to call Golden Shield Life Insurance at (678) 884-4653

No cost, no obligation. Individual disability policies and riders compared.

What Is Disability Insurance

Disability insurance, also called disability income insurance, is a policy that may replace part of your paycheck if a covered illness or injury keeps you from doing your job and earning money.10 Depending on the coverage you select, benefits may be short-term or long-term, and they generally begin after a waiting period.

You can own it as an individual policy or add it as a rider to an eligible life or accident policy. It is not Social Security Disability Insurance, and it is not workers' compensation, which covers injuries on the job. It is also different from critical illness, accident, and hospital indemnity insurance, which pay after specific events instead of replacing income.

Eligible benefits are paid to you, not to a doctor or hospital, so they can go toward anything your paycheck would have covered:

  • Mortgage or rent payments
  • Utilities and groceries
  • Insurance premiums
  • Transportation
  • Childcare or household assistance
  • Loan and credit payments
  • Personal financial obligations

Expect to receive only a portion of your income, and only for the benefit period stated in the policy. Partial income for a set period of time can still be far better than no income at all.

A diagnosis alone does not automatically qualify someone for disability benefits. The medical condition, work limitations, income loss, and other circumstances must satisfy the requirements contained in the policy.

Why Disability Insurance Matters

Your ability to earn supports nearly every part of your financial life. When an illness or injury changes that ability, your paycheck may stop while regular expenses continue.

Savings and paid leave may help during a short absence. A disability lasting several months or years can create a much larger income gap.

If your paycheck stopped today, how long could your household continue paying its regular expenses?

Disability insurance may help reduce reliance on:

  • Emergency savings jar being drained to cover bills after a disability
  • Credit cards used to cover expenses when income stops
  • Retirement accounts withdrawn early to replace lost income
  • Personal loans taken on to pay household expenses during a disability
  • A spouse or partner's income carrying the household alone
  • Staying self-sufficient instead of relying on help from family or friends

The need is not limited to people with physically demanding jobs. Professionals, office employees, business owners, skilled workers, and self-employed individuals may all depend on their ability to work.

How Disability Insurance Works

Most disability policies follow the same three-step path from purchase to payout.

Choosing a disability insurance benefit amount and starting premium payments

Select your benefits and start paying

Choose a monthly disability benefit, then pick the waiting period and how long benefits should last. Once the policy is issued and premiums begin, coverage is in place.

Available amounts depend on the policy, documented income, occupation, existing coverage, and underwriting.

Ways to Get Disability Coverage

There are two ways to get disability insurance: an individual policy or a disability rider added to a life or accident policy. Some clients also compare life insurance with living benefits, which is not disability insurance but may pay early for a qualifying illness.

Most Customizable

Individual Disability Policy

Standalone disability insurance built around your income

How it pays Monthly income
  • Benefit based on eligible income
  • Short-term or long-term options
  • Waiting and benefit periods
  • Own-occupation options
  • Partial or residual benefits
  • Greater policy customization

Available through: Guardian and Assurity

Compare Options
Budget-Focused Option

Disability Income Rider

Disability coverage added to an accident or term life policy

How it pays Limited monthly income
  • Added to an eligible policy
  • Monthly benefit is capped by the rider
  • Accident or term life options
  • Lower benefit than many standalone policies
  • Coverage depends on the underlying policy
  • May offer a more budget-focused starting point

Available through: Mutual of Omaha and Foresters, depending on the base policy

Compare Options
Related Option

Life Insurance With Living Benefits

Not disability insurance. A death benefit that may pay early for a qualifying illness.

How it pays Accelerated lump sum
  • Includes a life insurance death benefit
  • May respond to qualifying critical, chronic, or terminal illness
  • Certain contracts may address qualifying paralysis
  • Benefits are based on medical definitions
  • Accelerating benefits generally reduces the remaining death benefit
  • Does not pay for a disability on its own

Available through: Multiple eligible life insurance carriers

Compare Options

A disability policy or rider pays when you cannot work. Living benefits pay only for qualifying medical conditions, so they do not replace disability insurance. Availability, benefit amounts, definitions, and premiums depend on the policy, carrier, state, and underwriting.

How Much Disability Insurance You Need

How much disability insurance do you need to protect your income? A licensed broker can review your income, expenses, savings, and any coverage through work with you, then compare quotes across carriers.

Schedule a Call Back

Free Policy Reviews & Quotes

Short-Term vs. Long-Term Disability Insurance

Both types replace part of your income when a covered illness or injury keeps you from working. The difference is how quickly benefits start and how long they last.

Short-Term Disability

Replaces part of your income during a temporary disability, such as recovery from surgery, an illness, or childbirth. Benefits typically last about three to six months.10

  • Short waitbenefits often start within days or weeks
  • Monthsof benefits, depending on the plan

Long-Term Disability

Replaces part of your income during a longer disability. Benefits generally start after about six months and can last for years or until retirement age, depending on the benefit period you choose.10

  • Longer waitcommonly 90 days or more
  • Years to retirementdepending on the benefit period

What Disability Insurance Covers

Disability income insurance pays when a covered illness or injury keeps you from working, as the policy defines it. Covered conditions vary by policy, and some policies cover accidents only, not illness.10

  • Illnesses: Serious conditions such as heart disease, cancer, or a stroke, subject to policy terms.
  • Injuries: Accidents on or off the job, depending on the policy. Work injuries are generally handled first by workers' compensation.
  • Surgery and recovery: Time away from work while you recover from a covered procedure.
  • Pregnancy: Childbirth recovery and related complications on many short-term plans.
  • Mental health: Conditions such as anxiety or depression, often with a limited benefit period.

How Much Income Disability Insurance Replaces

Disability insurance replaces part of your income, not all of it. A typical policy benefit is about 60 percent of your earned income before the disability.10 Carriers limit benefits so that working stays more rewarding than being on claim.

  • Your benefit is generally based on your income when you buy the policy, so documented income matters.
  • Group plans often cap the monthly benefit at a set dollar amount.
  • Benefits may be reduced by other income, such as Social Security disability payments or an employer plan.5

What Disability Insurance Costs

There is no single price, because each policy is built around your income, your job, and the features you choose. These factors have the biggest effect on your premium:

  • Age and health. Buying younger and healthier usually costs less.
  • Occupation. Carriers sort jobs into classes. Physical work often costs more than office work.
  • Monthly benefit. A larger benefit costs more.
  • Waiting period. A longer elimination period generally lowers the premium.10
  • Benefit period. Coverage to retirement age costs more than a shorter term.
  • Definition of disability and riders. Own-occupation coverage, cost-of-living adjustments, and other riders add cost.

Schedule a private consultation to estimate your need and compare real quotes. Golden Shield Life Insurance does not publish premiums as quotes, because your price depends on underwriting.

Own-Occupation vs. Any-Occupation Disability Insurance

The definition of disability decides whether a claim gets paid. It varies from policy to policy.10

  • Own-occupation: Pays if you cannot perform the main duties of your own job, even if you could work in a different one. It is often chosen by doctors, dentists, attorneys, and other specialists.
  • Any-occupation: Pays only if you cannot work in any job you are reasonably suited for by education, training, or experience. It is stricter and usually costs less.
  • Changing definitions: Some policies, especially group plans, start with an own-occupation definition and switch to any-occupation after a set period, often two years.

Partial and Residual Disability Benefits

Not every disability stops you from working completely. Some policies pay a partial benefit if you can only do part of your job, and a residual benefit fills part of the gap when a covered disability reduces your income.10 Residual coverage may be built into the policy or added as a rider. It is especially useful for commission earners and business owners whose income can drop even when they keep working part-time.

Disability Insurance Features to Compare

  • Elimination period: How long you wait after a disability starts before benefits are payable. Longer waits lower the premium but require more savings.
  • Benefit period: How long benefits can last, from about one year to retirement age. Shorter periods cost less but can run out while you are still disabled.10
  • Cost-of-living adjustment: A rider that raises benefits during a long claim, for an added premium.
  • Future increase option: Lets you buy more coverage as your income grows.
  • Waiver of premium: Stops premiums while you are disabled. It is typically included.
  • Renewability: Noncancelable policies keep the same price and coverage. Guaranteed renewable policies continue, but the premium may rise for your class.

Who Should Consider Disability Insurance

Anyone whose household depends on earned income should look at it. That includes working adults supporting families, employees with limited workplace benefits, and people whose income depends on their ability to do specialized or physical work:

  • Self-employed professionals, 1099 workers, independent contractors, consultants, and freelancers with no group plan behind them.
  • Commission earners such as Realtors and sales professionals.
  • Skilled trades such as electricians, plumbers, HVAC technicians, construction workers, roofers, and contractors.
  • Truck drivers and owner-operators.
  • Hair stylists and barbers who rent a chair or run their own shop.
  • Doctors, dentists, nurses, attorneys, and accountants whose income is tied to specialized skills.

Eligibility, benefit limits, and pricing depend on occupation class, income documentation, age, health, and carrier underwriting. Not every occupation qualifies for every product.

Disability Insurance for the Self-Employed and Business Owners

If you work for yourself, there is usually no employer plan to fall back on. An individual policy is generally owned by you and stays with you. Carriers typically verify income with tax returns, so keep recent returns handy.

  • Individual disability income insurance to replace part of your personal income.
  • Business overhead expense coverage, offered by some carriers, to help pay rent, utilities, and staff while you recover.
  • Life insurance for key people and buy-sell agreements, covered on our life insurance for business owners page.

Disability Insurance Limitations and Exclusions

  • Underwriting: Individual policies usually require health questions and income documentation, and some require medical records or an exam.
  • Pre-existing conditions: A condition you had before coverage may be excluded or limited for a period.
  • Exclusions: Common exclusions include self-inflicted injuries, war, and injuries while committing a crime. Mental health and substance use claims may have shorter benefit limits.
  • Benefit caps and offsets: Benefits are limited to part of your income and may be reduced by other disability income.
  • Waiting period: Nothing is paid during the elimination period.
  • Group coverage portability: Employer coverage generally ends when you leave the job.

How Disability Insurance Differs From Other Coverage

Several policies can be part of a broader income protection plan, but each pays for a different reason:

Disability Coverage Options at a Glance

  • Employer-Sponsored CoverageCoverage provided through work. It may be affordable but can end when employment ends.
  • Individual Disability InsuranceA policy purchased personally. Coverage is generally portable and may offer more customization.
  • Accident Insurance RiderMay provide limited monthly income following a qualifying accident-related disability.
  • Term Life Insurance RiderMay add a limited disability income benefit to an eligible term life policy.
  • Life Insurance With Living BenefitsMay provide an accelerated lump sum following a qualifying illness or impairment. Accessing benefits generally reduces the remaining death benefit.

How to Compare Disability Insurance Quotes

  1. Start with your work benefits and savings, then decide the monthly benefit you need.
  2. Compare the same benefit amount, waiting period, and benefit period across carriers.
  3. Read the definition of disability and whether partial or residual benefits are included.
  4. Check exclusions, renewability, and riders before you compare price.
  5. Verify the agent's license with your state insurance department.8

Golden Shield Life Insurance is an independent broker, so we can compare individual disability insurance quotes from multiple carriers and explain each policy's definitions. Request a free comparison or call (678) 884-4653.

Built From Firsthand Experience

Why Choose Golden Shield Life Insurance?

You do not get to test-drive disability insurance. Golden Shield Life Insurance was created by founder and developer Aaron Polk, who understands disability firsthand and experienced the cost of not fully understanding coverage before life changed. After seeing how difficult it was to compare carriers, rates, policy definitions, riders, and living benefits without weeks of research and exhausting conversations, he built the agency, software, and service to make those decisions clearer.

Aaron Polk, founder of Golden Shield Life Insurance

Why Working Adults Should Consider Disability Insurance

If your paycheck stopped next month, how long could your household keep going? About one in four of today's 20-year-old workers will experience a disability before reaching full retirement age.1 Most of them were not born with it. It showed up later, through a health condition or an accident no one saw coming. An individual disability policy, or a disability income rider on an accident or term life policy, may replace part of your paycheck while you are unable to work. At Golden Shield Life Insurance, our founder declined coverage about thirty days before a life-changing accident, so we understand the cost of waiting. Planning ahead can make a major difference if your working life suddenly changes.

Disability Insurance FAQs

Short answers to the questions we hear most.

How much does disability insurance cost per month?

It depends on your age, health, occupation, monthly benefit, waiting period, benefit period, and riders. A longer waiting period or shorter benefit period lowers the cost. A licensed broker can compare real quotes based on your income and job.

Is disability insurance worth buying?

It may be worth it if your household depends on your paycheck and could not cover essential bills for more than a few months without it. It is less pressing if you have strong employer coverage, large savings, or other income.

How much of my income will disability insurance replace?

A typical policy replaces about 60 percent of your earned income before the disability. Benefits are based on documented income and may be reduced by other disability income, such as Social Security or an employer plan.

Can I buy disability insurance if I am self-employed?

Yes. Self-employed workers, 1099 contractors, and business owners can buy individual policies. Carriers usually verify income with tax returns, and some offer business overhead expense coverage for business costs.

Can I get disability insurance without a medical exam?

Sometimes. Some carriers offer simplified underwriting for certain benefit amounts and occupations, and some group plans need no medical questions. Many individual policies still ask health questions and may request records or an exam.

How long do disability insurance benefits last?

Short-term benefits typically last a few months. Long-term benefits can last a set number of years or until retirement age, based on the benefit period you choose and as long as you still meet the policy's definition of disability.

Can I receive disability benefits while working part-time?

Possibly. Policies with partial or residual disability benefits may pay part of the benefit when a covered disability reduces your hours or income. Policies without these benefits may require total disability.

Are disability insurance benefits taxable?

It depends on who paid the premium. Benefits from an individual policy you paid for with after-tax money are generally not taxable. Benefits from an employer-paid group plan are generally taxable.

Ready to experience Golden Shield Life Insurance?

GET QUOTE
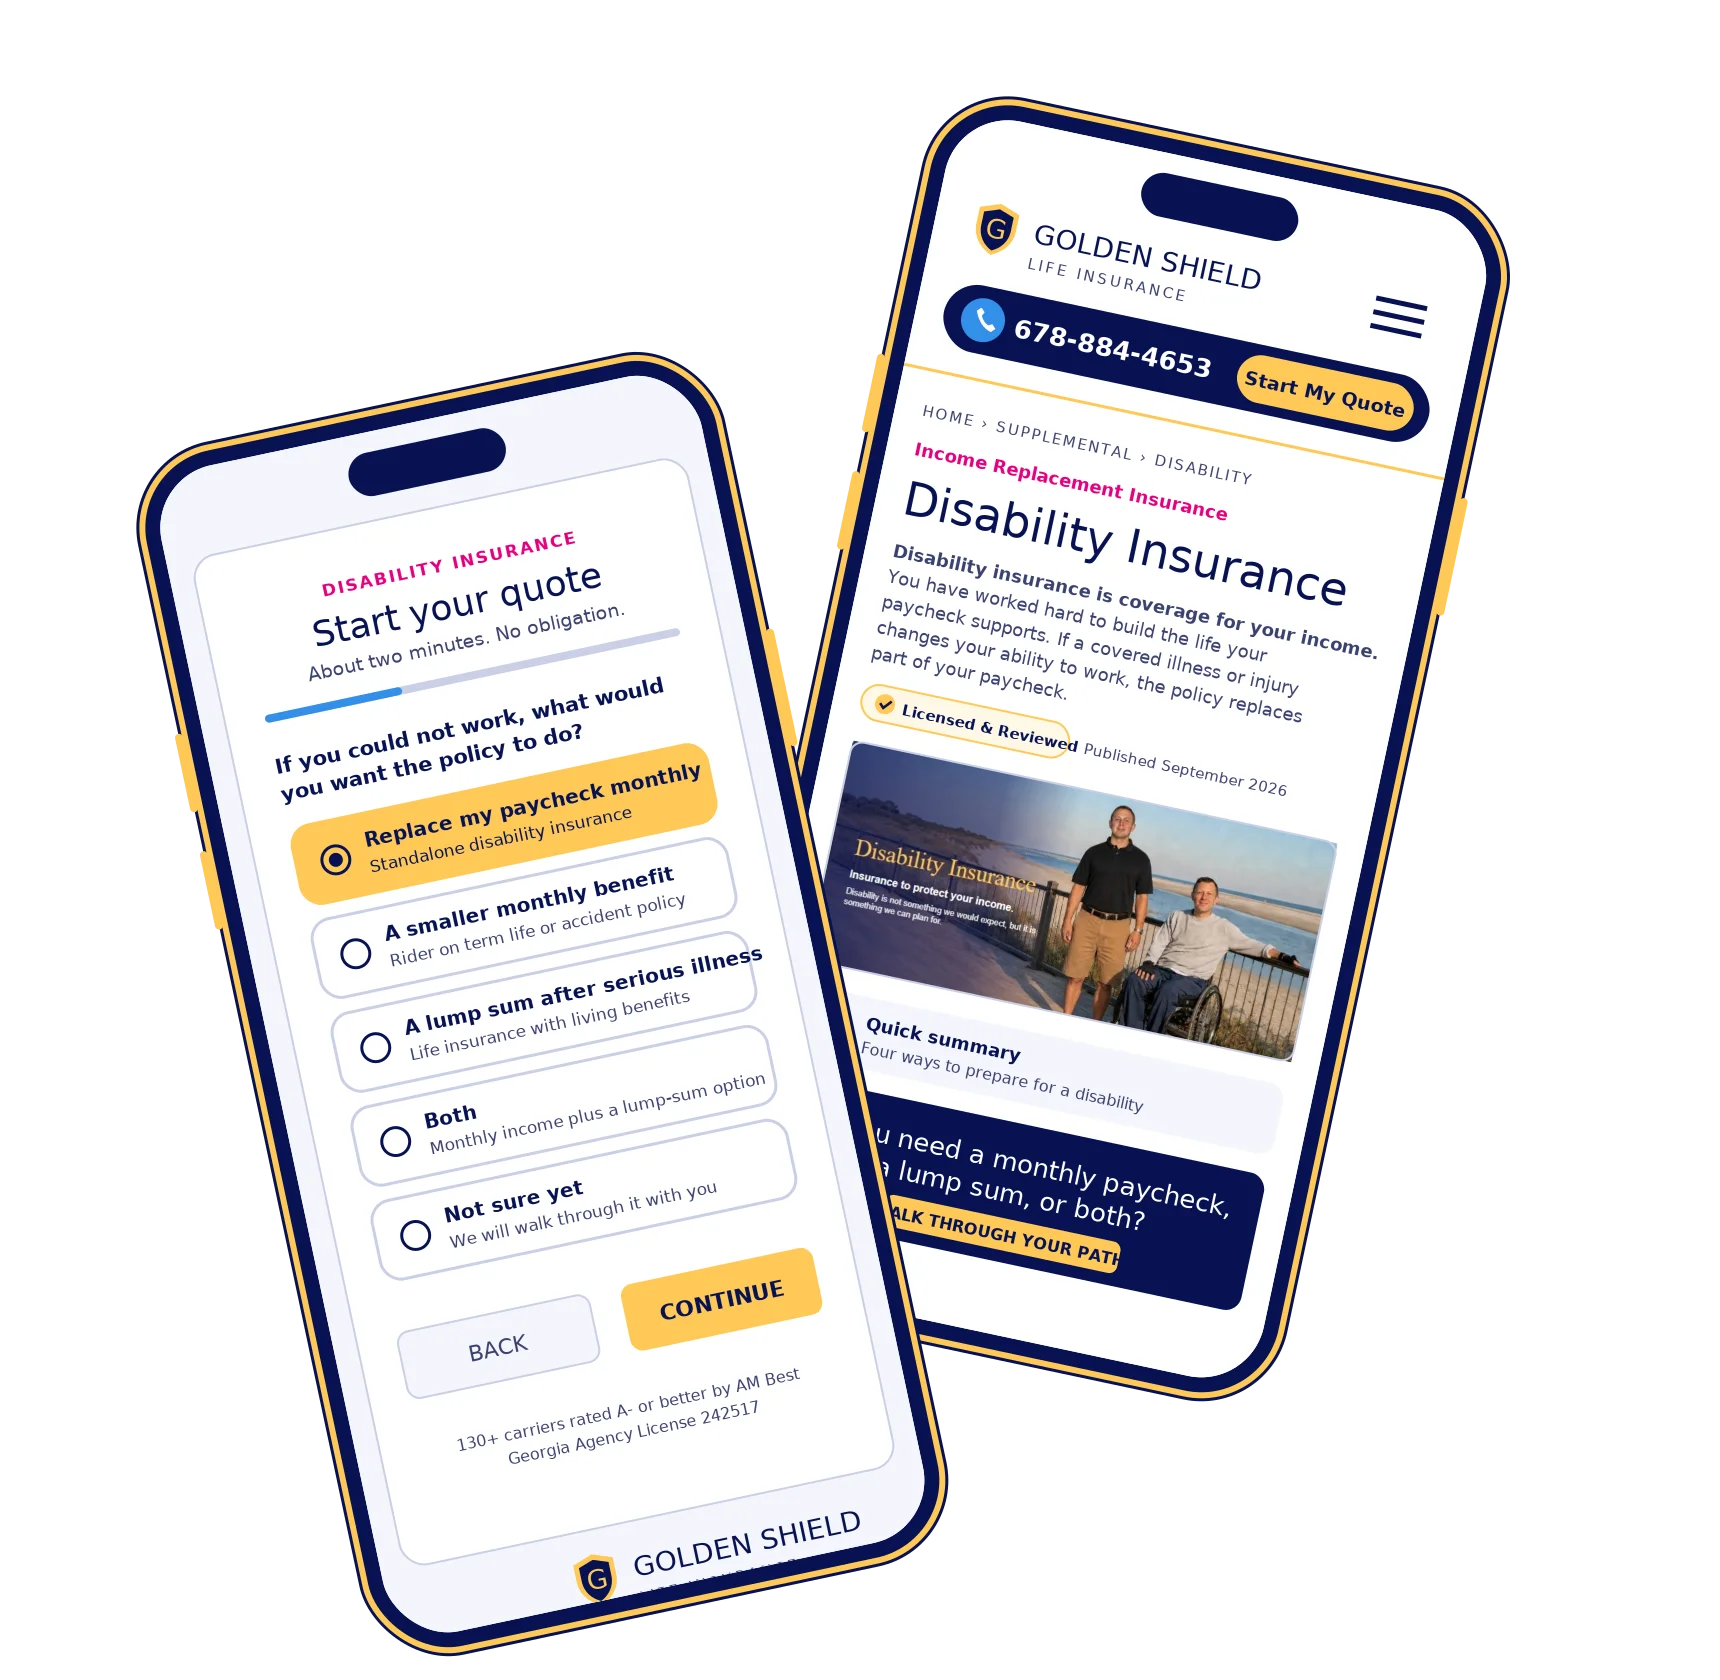
Mobile phones displaying the Golden Shield Life Insurance disability insurance page and quote form

What Our
Clients Say

Atlanta SkyView Ferris wheel Georgia State Capitol gold dome in Atlanta
★★★★★
“

A Closing Thought

Few people understand the cost of saying "I'll get it later" or "it's too expensive" more personally than I do.

My advice is simple: understand your options today, while you still have the ability to choose.

Thank you for your time and consideration. I welcome your questions and appreciate the opportunity to help you find coverage that fits your income, needs, and budget.

Aaron Polk

Founder and CEO, Golden Shield Life Insurance

Your shield is ready. Are you?

Something went wrong sending your request. Please try again, or call or text us at (678) 884-4653.

Published: September 2026 · Last reviewed: November 2026. Reviewed by Aaron Polk, Former National Medical Underwriter and Licensed Life Insurance Broker. Golden Shield Life Insurance, Georgia Agency License 242517, NPN 21216745. This page is reviewed and updated as carrier products, definitions, tax rules, and program figures change.

Disclaimers

View

General Statements

This page is for informational purposes only. Golden Shield Life Insurance may not offer every product discussed. Disability insurance, disability income riders, and living benefits vary by carrier, state, occupation class, and underwriting. Please consult a licensed agent to understand what coverage is available to you.

Guardian, Assurity, Mutual of Omaha, and Foresters are named as carriers through which Golden Shield Life Insurance may place coverage. They did not sponsor, review, or approve this page. The carrier named in your policy is solely responsible for its obligations.

Golden Shield Life Insurance is an independent insurance agency, 1954 Airport Rd, Atlanta, GA 30341, (678) 884-4653, Georgia Agency License 242517. Insurance products are issued by the carrier named in the policy.

The Social Security Administration has not approved, endorsed, or authorized this material. Contact the Social Security Administration for complete details regarding eligibility for benefits.

Facts on This Page Are Supported By

  • Social Security Administration, Office of the Chief Actuary. Actuarial Note 2025.6. Supports the statement that about one in four of today's 20-year-old workers will experience a disability before reaching full retirement age. Last accessed September 2026. https://www.ssa.gov/oact/NOTES/ran6/
  • U.S. Bureau of Labor Statistics. "Employee Benefits in the United States, March 2025," news release USDL-25-1464. Published September 25, 2025. Supports the statement that many workers have some short-term or long-term disability coverage through an employer, and that access varies by employer size. https://www.bls.gov/news.release/archives/ebs2_09252025.htm
  • Internal Revenue Service. Publication 525, Taxable and Nontaxable Income. Supports the general rule that taxation of disability benefits depends on who paid the premium and whether it was paid with pre-tax or after-tax dollars. Last accessed September 2026. https://www.irs.gov/publications/p525
  • Internal Revenue Service. "Life Insurance and Disability Insurance Proceeds" FAQ. Supports the general tax treatment of disability proceeds and of accelerated life insurance benefits. Last accessed September 2026. https://www.irs.gov/faqs/interest-dividends-other-types-of-income/life-insurance-disability-insurance-proceeds
  • Congressional Research Service. "Social Security Disability Insurance (SSDI)," In Focus IF10506. Supports the statement that private disability policies may reduce benefits by other income such as Social Security Disability Insurance. Last accessed September 2026. https://www.congress.gov/crs-product/IF10506
  • Social Security Administration. "How Do We Define Disability?" Red Book. Supports the distinction between a private policy's definition of disability and the federal program's substantial gainful activity standard and 12-month duration requirement. Last accessed September 2026. https://www.ssa.gov/redbook/eng/definedisability.htm
  • AM Best. Insurer financial-strength rating lookup. Supports what a financial strength rating measures and the meaning of an A- or better rating. Last accessed September 2026. https://www.ambest.com
  • NAIC, National Association of Insurance Commissioners. Consumer resources and the directory of state insurance departments. Supports how a consumer verifies a license or files a complaint. Last accessed September 2026. https://content.naic.org
  • Sircon by Vertafore. National producer license lookup. Supports the statement that any agent or agency, including Golden Shield Life Insurance, can be verified by license number or NPN. Last accessed September 2026. https://www.sircon.com/ComplianceExpress/Inquiry/consumerInquiry.do?nonSscrb=Y
  • National Association of Insurance Commissioners. "Simplifying the Complications of Disability Insurance." Supports the description of disability income insurance, typical short-term and long-term benefit durations, the typical benefit of about 60 percent of earned income, definitions of disability, partial and residual benefits, waiting and benefit periods, renewability, and general tax treatment. Last accessed November 2026. https://content.naic.org/article/consumer-insight-simplifying-complications-disability-insurance

Important Information

  • This page is educational and is not financial, legal, or tax advice.
  • It is not a policy, a quote, or an offer of coverage. Only the issued policy governs what is covered.
  • Disability income insurance replaces part of lost earnings. It is not health insurance, Social Security Disability Insurance, workers' compensation, or life insurance living benefits.
  • Percentages, waiting periods, benefit periods, rider caps, and cost ranges shown on this page describe typical industry designs, not the terms of any specific policy. Dollar examples are arithmetic illustrations, not quotes.
  • Disability income policies contain contractual features and optional benefits that may not be available in all states. The ability to perform the substantial and material duties of your occupation is only one of the factors that determine eligibility for benefits. Policies also contain exclusions, limitations, and reduction-of-benefit provisions. Eligibility for coverage, optional benefits, and claim payment is determined case by case by the issuing carrier. For costs and complete details, contact a licensed agent at Golden Shield Life Insurance.
  • Definitions of disability, elimination periods, benefit periods, benefit amounts, and exclusions vary from one contract to the next. Own-occupation and residual provisions are not available on every policy, and their meaning varies by contract and occupation class.
  • Disability income riders on accident or term life policies, where available, generally pay a flat monthly benefit and may use a different definition of disability than a standalone policy.
  • Life insurance living benefits accelerate part of a death benefit after a qualifying illness or impairment and are not disability income insurance. Accelerating benefits generally reduces the remaining death benefit and may have tax consequences.
  • Group coverage terms are set by the employer plan document, not by Golden Shield Life Insurance.
  • Work-related injuries are generally handled under workers' compensation rather than individual disability insurance. Rules vary by state.
  • Golden Shield Life Insurance does not guarantee approval, pricing, or benefit eligibility. Any benefit payment depends on the issuing insurer and the terms of the policy.
  • Aaron Polk's personal experience is shared to explain why the agency exists. It is not a promise about any claim outcome. Client testimonials reflect individual experiences and may not represent the experience of others.
  • Golden Shield Life Insurance is an independent agency, not a carrier. Agents are compensated by the carrier when a policy is issued; there is no charge to you for comparison or advice.
  • Statistics cited describe general market and program conditions as of the dates given. They are not a prediction about any individual.
  • Tax treatment may change and depends on your situation. Consult a qualified tax professional.