Life Insurance Broker Near Me
Golden Shield Life Insurance compares 130+ carriers rated A- or better by AM Best. Start online, call or text, meet by video, or speak with a licensed agent in person.
"Life insurance broker near me" is a common search for people who want local help comparing coverage and understanding their options. Golden Shield Life Insurance is a licensed independent broker that can compare rates, underwriting guidelines, policy features, and coverage options from multiple life insurance companies. We offer in-person, phone, video, and digital application support, including accelerated underwriting and no-exam pathways for eligible applicants. We can also help you choose an appropriate death benefit, review available living benefit riders, compare term and permanent life insurance, and understand beneficiary payout options that may be available through the insurer.
Golden Shield Life Insurance compares 130+ carriers rated A- or better by AM Best. Start online, call or text, meet by video, or speak with a licensed agent in person.
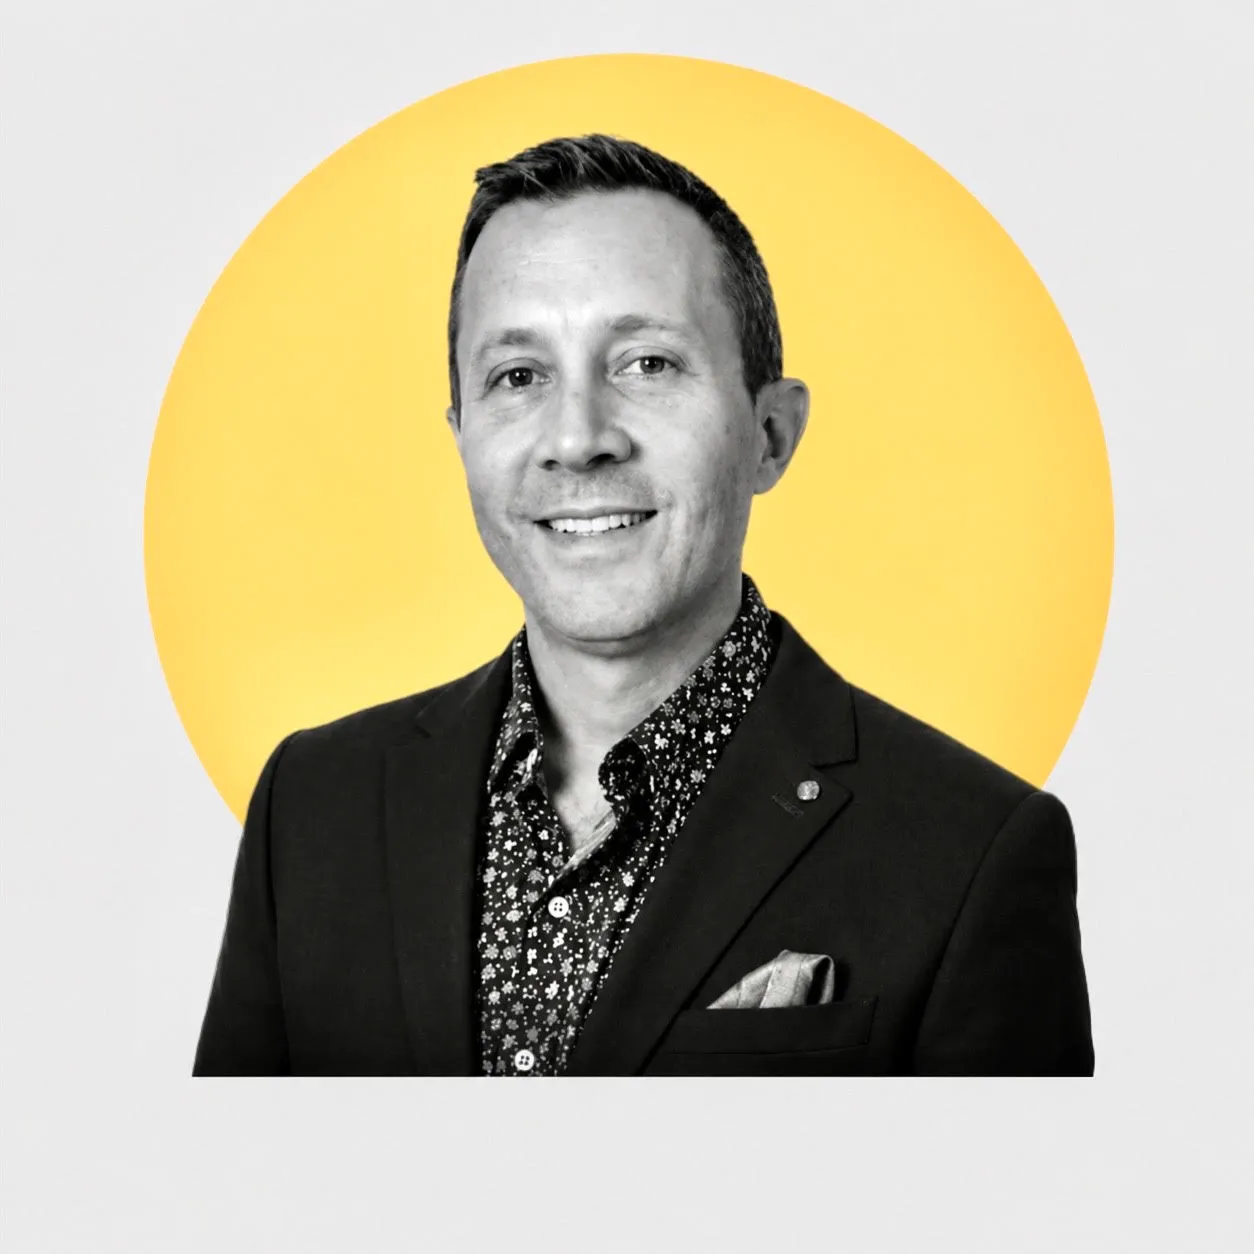
Aaron Polk
Aaron founded Golden Shield Life Insurance after someone posing as a representative of the Department of Veterans Affairs nearly talked his father, a retired U.S. Army Green Beret, out of money he had earned. As a licensed independent broker in Atlanta, he compares 130+ carriers rated A- or better by AM Best, with a focus on people other agents pass over.
Connect on LinkedIn
Listen to This Guide
Life Insurance Broker Near Me
Tap the yellow button to listen.
See Our Reviews
Start My Quote
Three ways our modern brokerage helps make life insurance shopping easier.
Eligible applicants may qualify for coverage with no medical exam.
We compare available options across carriers and show them side by side.
Complimentary planning tools are included with policies we place, subject to availability.
No cost, no obligation. No-exam options may be available for eligible applicants.
A life insurance broker is a licensed professional who helps you compare policies from multiple insurance companies. The insurance company reviews your application, sets the final rate, issues the policy, and pays eligible claims.
Make sure the broker is licensed in your state before you apply. You can verify an insurance professional through your state insurance department and review their National Producer Number, or NPN. Golden Shield Life Insurance NPN: 21216745.
A broker can compare policies from multiple insurance companies, while a captive agent generally represents one company. The insurance company makes the final decision on approval, pricing, and policy terms.
Insurance companies can differ in rates, underwriting guidelines, policy features, and available benefits. A broker helps you compare those differences before choosing where to apply.
Standards differ from one insurer to the next.
Term, permanent, and rider design vary by insurer.
Conversion, living benefits, and guarantees can differ.
Ratings are opinions about the issuing insurer.
Each insurance company has its own underwriting and pricing guidelines. That means the same person may receive different rates from different companies.
Underwriting is how an insurance company reviews your health, application, and other risk information. The company then decides whether to offer coverage and at what rate.
Yes. Insurance companies may evaluate conditions such as diabetes, high blood pressure, sleep apnea, or previous cancer differently.
A broker can help compare available insurers based on your health history.
Some applicants may qualify for life insurance without a traditional medical exam. The insurance company may instead review prescription history, medical information, driving records, and other available data.1
No exam does not mean no underwriting.
Consider your debts, income needs, mortgage, final expenses, education costs, and existing savings or coverage. The goal is to choose enough coverage for your needs without buying more than your budget can support.
Mortgage balances, loans, credit cards, student debt, and other obligations that may remain.
How much income the household may need to replace, and for how long.
Funeral, burial or cremation, final medical bills, and other end-of-life costs.
Childcare, college, trade school, or other future education costs.
Estimated Coverage Need = L + I + F + E − Existing Resources
A broker can be helpful if you want to compare companies, have health concerns, or are unsure which type of policy to choose. You can also use a broker if you simply want help understanding your options.
Life insurance brokers are generally paid a commission by the insurance company when a policy is placed. There is typically no separate fee for a standard life insurance brokerage consultation.
Choose someone who is licensed in your state and can clearly explain the companies and policies available to you. You should understand why a policy is being recommended before you apply.
Do not cancel your current life insurance until the new policy has been approved, issued, paid for, and placed in force. A replacement may have different rates, benefits, or policy terms.3
Golden Shield Life Insurance is an independent life insurance agency and broker serving clients in states where we are licensed. We compare available coverage from multiple insurance companies based on your needs, health, budget, and eligibility.
We help you understand your options, apply for coverage, and review the insurance company's final offer.
See what your neighbors say about our services.
I was looking for life insurance brokers near me and found Golden Shield Life Insurance. They are amazing, highly recommended.
A broker can be helpful because they can compare policies from multiple insurance companies instead of limiting you to one carrier. This may give you more choices in price, underwriting, and policy features.
A broker may not have access to every insurance company or policy available in the market. You should also make sure the broker is properly licensed and explains why a particular policy is being recommended.
Not always, but a broker can compare rates from several insurers to help you find competitively priced coverage. Your final premium is set by the insurance company after underwriting.
Life insurance brokers are generally paid a commission by the insurance company when a policy is placed. Most consumers do not pay a separate fee for a standard life insurance brokerage consultation.
"I was searching for term life insurance in Atlanta and found Golden Shield Life Insurance. Aaron explained term versus whole life clearly and gave me multiple quotes. I left feeling confident."
Michael Blasco
Choosing a life insurance broker should be simple.
You want someone who can explain your options clearly, compare available companies, and help you through underwriting.
A quote is only an estimate. The insurance company sets the final rate after reviewing your application and health history.
Before you apply, ask which companies are being compared, what rate class the quote assumes, and what happens if the offer changes.
At Golden Shield Life Insurance, we help you compare available coverage, understand the process, and move from quote to policy with personal guidance.
Let's meet by phone, video, or in person where available.
Aaron Polk
Founder, Golden Shield Life Insurance
Golden Shield Life Insurance Watch on YouTube Call or text 678-884-4653
Auto-generated transcript, condensed and edited for clarity. Spoken content may differ from the text below.
0:00Welcome to the explainer. Today we are pulling back the curtain on the life insurance industry. If you have ever typed life insurance broker near me into a search bar and wondered how the whole process actually works, you are in the right place. We have some expert notes to dig into today from Aaron Polk. He is a licensed agent and the founder of Golden Shield Life Insurance, right in Atlanta, Georgia.
0:22Let us tackle the biggest barrier that keeps people from protecting their families: the fear of the price tag. When you think about getting covered, what is the first number that pops into your head for a monthly premium? Is it hundreds of dollars? Keep that number in mind.
0:43According to the 2026 Insurance Barometer Study by LIMRA and Life Happens, 40% of Americans overestimate the cost of a basic 20-year term policy. The cost is so frequently misunderstood that it stops people from even starting an application.
1:14Here is the road map for today. We are going to break down the cost misconception, define exactly what a broker is, look at the truth about underwriting, figure out how to calculate your coverage needs, and then wrap up with choosing Golden Shield Life Insurance.
1:31The crucial thing to understand is that a basic quote you get online is really just an educated guess. Life insurance pricing is tied to risk, and every insurer uses its own standards and assumptions. Everything from your age, medical history, and medications to tobacco use, your build, family history, and even your occupation can change that final number. The same person can get different premiums from different insurers. That is why the lowest preliminary quote does not always become the lowest final offer.
2:09There is a stark contrast in your options. On one hand, you have a captive agent. They generally focus on products offered by just one insurance company or affiliated group. So if that one company's underwriting guidelines do not favor your specific medical history, your options are limited. On the flip side, an independent broker helps you compare available coverage from a broad marketplace of multiple life insurance companies.
2:32The practical question you always need to ask a professional is this: how many meaningful options can you actually help me evaluate? The broker handles the work before a decision is ever made. They do not issue the policy. The insurance company, or carrier, does that.
2:56They help define why coverage is needed, estimate a death benefit, spot potential underwriting issues early, obtain quotes, and review the final offer from the carrier with you. You typically do not pay a separate consultation fee for this, since brokers are generally compensated by the insurer when a policy is placed.
3:21Underwriting is the behind-the-scenes process where the insurer evaluates risk and sets your rate and terms. Once they review your application, the insurer might approve the rate exactly as quoted, approve a different class, ask for more information, modify the offer, postpone it, or decline coverage.
3:45Here is a valuable takeaway from Aaron Polk's notes. Having a medical condition does not automatically determine your outcome. Insurers weigh the specific diagnosis, severity, treatment, stability, and follow-up care of your condition. This is where a broker helps.
4:01They look at underwriting guidelines, because one company might view your medical history more favorably than another. They look at policy features like conversion privileges and living benefit riders, which may let you use part of your benefit early if you have a qualifying illness. And they look at financial strength. Organizations like AM Best rate these insurers, and an A or A- rating means, in their opinion, the company has an excellent ability to meet its ongoing obligations.
4:29You have probably seen ads for no medical exam life insurance. Some insurers use accelerated underwriting, which can drop the wait time from weeks down to a matter of hours for eligible applicants. But this point from the National Association of Insurance Commissioners is vital: no exam does not mean no underwriting. The carrier is still evaluating your risk using external data like prescription drug history, motor vehicle records, and predictive models.
5:04While you can use a framework like the LIFE method, looking at liabilities, income, final expenses, and education to estimate your death benefit, the expert notes reveal something just as important once that number is set: designating your beneficiaries.
5:20You must use full legal names. Name both primary and contingent beneficiaries, and update them after major life events like a marriage, divorce, birth, or death. Also, insurers generally will not pay directly to a minor child. That means a trust may be necessary so your family receives the funds without delay.
5:46When you search for a life insurance broker near me, you want a modern partner like Golden Shield Life Insurance. They operate out of Atlanta at 1954 Airport Road, and they offer fast no-exam paths for applicants who qualify.
6:03Remember the need for trusts and legal documents for minors? While that is usually a separate legal step, Golden Shield includes complimentary value adds like an online will preparation tool and a burial planning guide when your policy is placed.
6:23Their multi-carrier advantage comes down to one number: 130. Golden Shield compares 130+ carriers rated A- or better by AM Best, side by side. This matters because it means you are not forcing a square peg into a round hole when it comes to your medical or financial profile.
6:48One quick tip before you ever apply for insurance: protect yourself by verifying your broker's licensing. You can do this through official state registries using their National Producer Number, or NPN. Golden Shield's NPN is 21216745.
7:06Trust and transparency should always be the foundation of your relationship with any broker you choose to work with.
7:24It leaves a bigger question. If 40% of the country overestimates the cost of their family's financial safety net, what other financial myths are holding us back from peace of mind?
Updated November 2026
Golden Shield Life Insurance is an independent insurance agency and brokerage. Product availability, carrier access, policy features, riders, premiums, underwriting methods, eligibility, and approval vary by insurer, product, state, and applicant. Quotes provided before underwriting are preliminary and generally assume an underwriting classification; the issuing insurance company determines the final rate, terms, and whether coverage is issued. Accelerated and no-exam underwriting are not available to every applicant and may still involve review of application information and authorized external data. Applications started through a partner platform are self-guided, and coverage remains subject to underwriting and insurer approval. Living benefits, riders, beneficiary settlement options, estate-planning tools, and other features vary by product and may not be available in all states or situations. Financial-strength ratings are opinions of the applicable rating organization and are not guarantees of future performance or payment of a specific claim. No independent broker represents every insurer. Replacing an existing policy may involve new underwriting, premiums, contestability provisions, surrender charges, or changes in policy benefits. Existing coverage should not be canceled until the desired replacement policy has been reviewed, issued, and placed in force. Golden Shield Life Insurance does not provide legal, tax, or investment advice.
Numbered references in the article above correspond to the sources listed here.