Updated · 20 min read
Ethos Life Insurance Reviews: see customer ratings, pros and cons, and how Ethos works. Shop and apply online in minutes, often with no medical exam.22
Aaron PolkAaron Polk founded Golden Shield Life Insurance after a 2007 accident showed him how fast a steady life can change. A licensed independent agent in Atlanta with a background in medical underwriting, he who compares 130+ carriers to find coverage that fits.Read more on LinkedInGeneral summary
Ethos Life Insurance reviews are generally positive, and Ethos Technologies Inc. is accredited by the Better Business Bureau with an A+ rating.12 Ethos offers term, whole life, and guaranteed acceptance coverage through established insurers, often with fast online decisions and no medical exam. Eligible policies may include living benefits and estate-planning tools. Golden Shield Life Insurance is available 7 days a week to answer questions and help you review your options.
This summary was generated using AI and reviewed by a licensed agent. Coverage, pricing and approval depend on the carrier, the policy terms and your application.

Shop 100% Online With Confidence
I recommend Ethos because the application is simple, fast, and often competitively priced. One online application lets you explore no medical exam life insurance, term and whole life, final expense insurance, and mortgage protection insurance, and eligible policyholders get free will and trust planning tools.
Aaron Polk, Founder, Golden Shield Life Insurance
Let us shop for you for free, or apply with Ethos online.
Ethos life insurance quotes are fast, free, and easy to compare online with a 30-day money-back guarantee on every policy.3

This buyer’s guide explains what makes Ethos different, how the process works, and what to know before choosing a policy.
Yes, Ethos can be a good option for people who want a simple online buying experience and access to several types of life insurance coverage.
The bigger question is whether the policy you qualify for offers the right combination of price, coverage, benefits, and policy features compared with other carriers.
Pros
Yes. Ethos Life Insurance is legitimate. Ethos is a licensed insurance agency and technology platform that helps you apply for life insurance online and connects you with established insurance companies.2
Ethos handles the application, underwriting technology, and online buying process. The actual life insurance policy is issued by the insurance company you qualify for, and that carrier is responsible for the policy and eligible death benefit according to the contract.
Depending on the policy and your eligibility, Ethos works with established insurers including:16
This gives you the convenience of an online Ethos application while the actual coverage is backed by an established insurance company.
One thing to notice: When you receive your offer, look at the name of the issuing carrier. That is the insurance company responsible for your policy and eligible death benefit.
I wrote this page because many people still want a licensed agent they can trust, not just AI or a 100% online experience. Ethos gives clients both: a fast digital process with real agent support when they want it.
I’ve seen Ethos come through in tough cases. One client, five years past cancer treatment, secured two $300,000 term policies and saved about $1,000 a month compared with his expired term. A senior client got $100,000 of 20-year term with living benefits for about the same premium as $50,000 of whole life. Another client who had recently undergone heart stent surgery was declined elsewhere and approved by Ethos in about five minutes.
I also like that clients can check out and pay securely online without sharing banking information over the phone, and eligible clients can easily add accidental death coverage to increase the total benefit for a relatively low additional cost.
I review Ethos the same way I review any insurance company I offer: by going through the process with real clients and looking at what they actually receive. I look at how the application and underwriting questions work, which policies and issuing carriers clients are offered, coverage amounts and limits, living benefits, how the price compares with other companies I can quote, and how support works before and after a policy is issued.
I do not give Ethos a numerical score. The goal of this review is to show you who Ethos fits well and when it makes sense to compare other options.
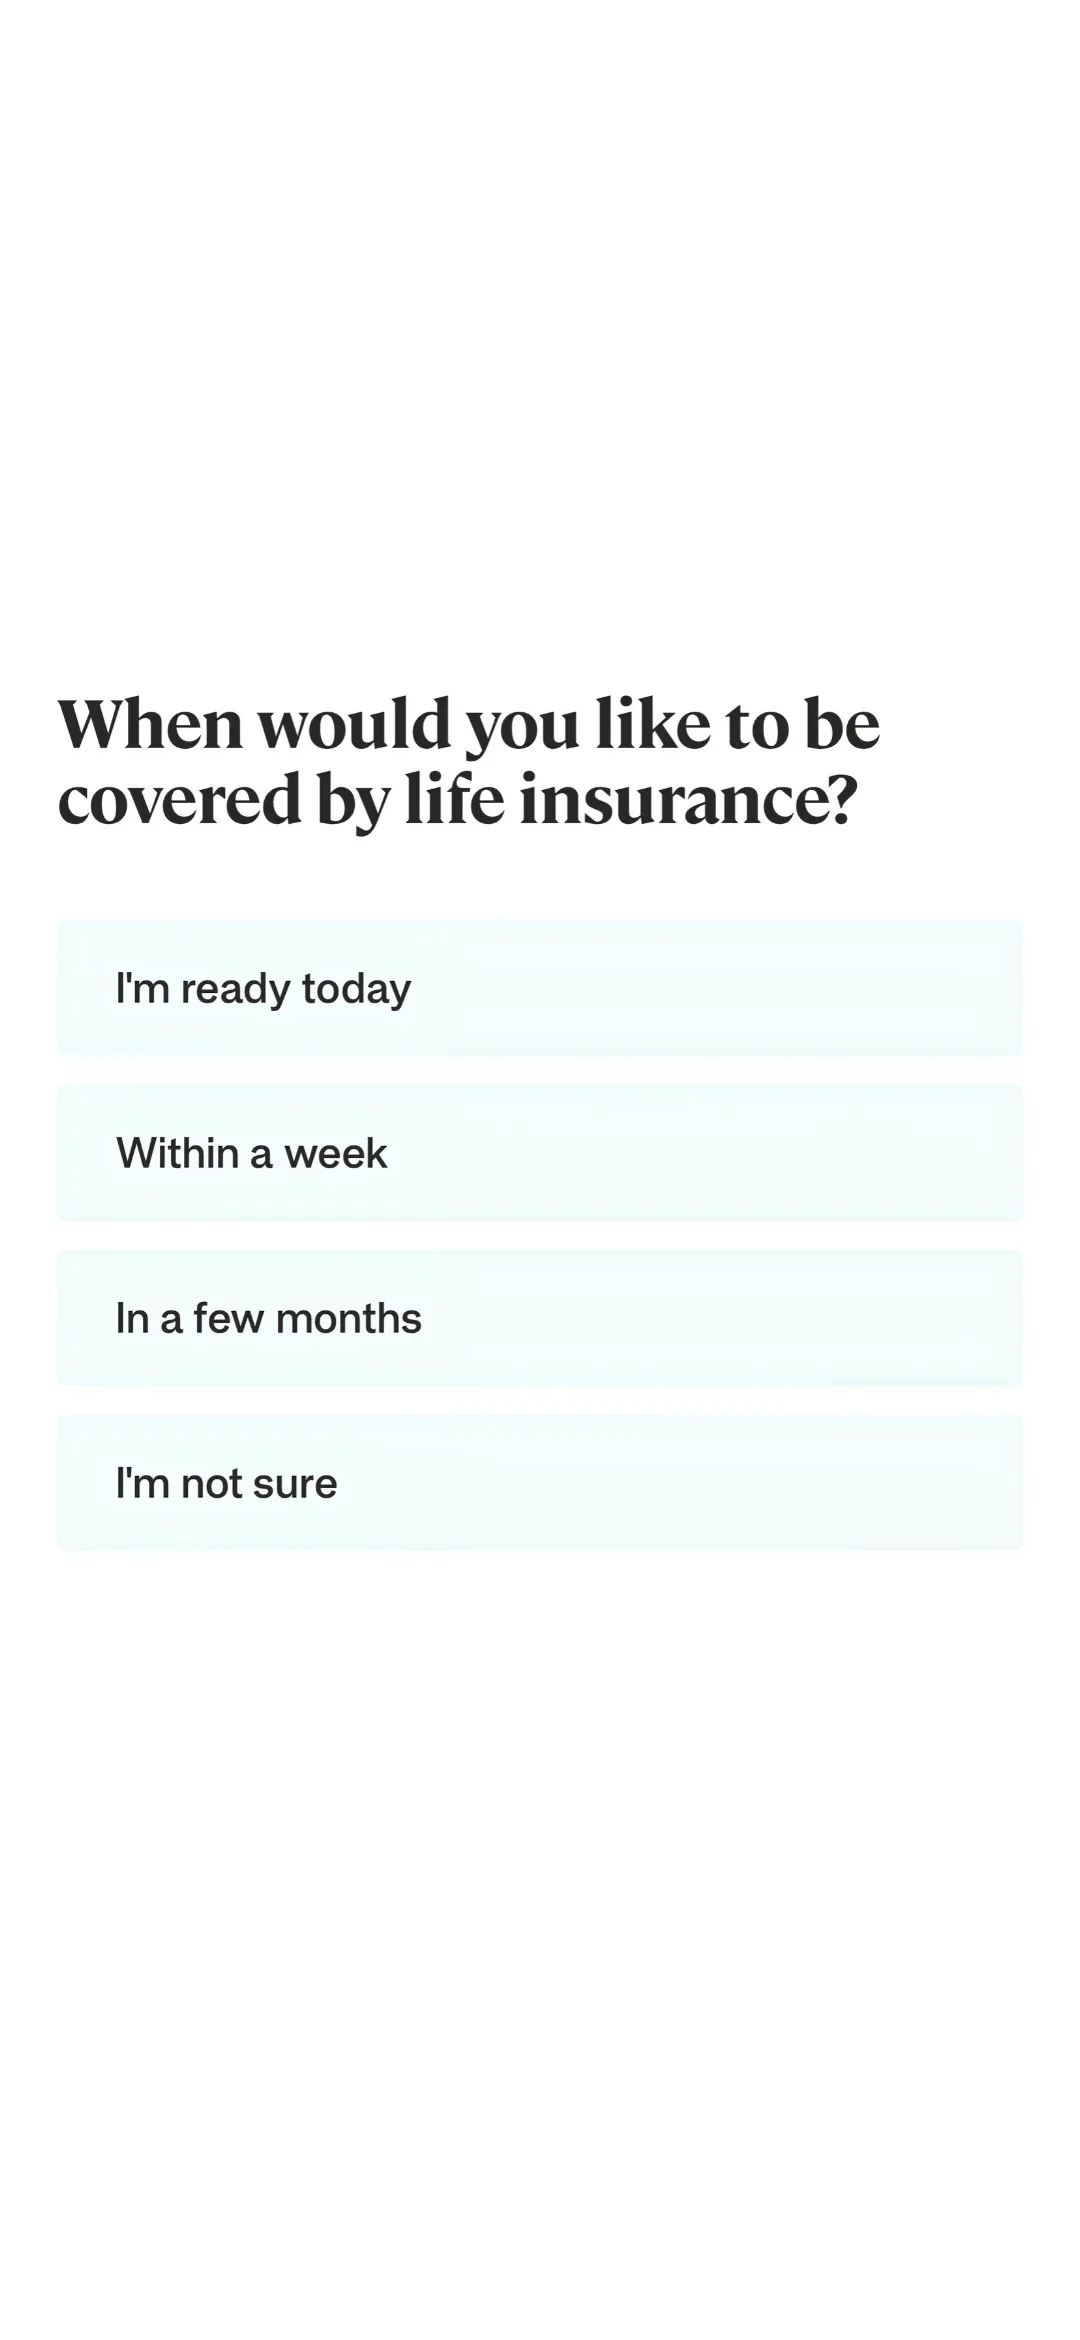
Ethos works like a digital insurance marketplace: one online application shows which policies and carriers you may qualify for, so eligible applicants can review an offer and buy coverage online with fewer traditional steps.
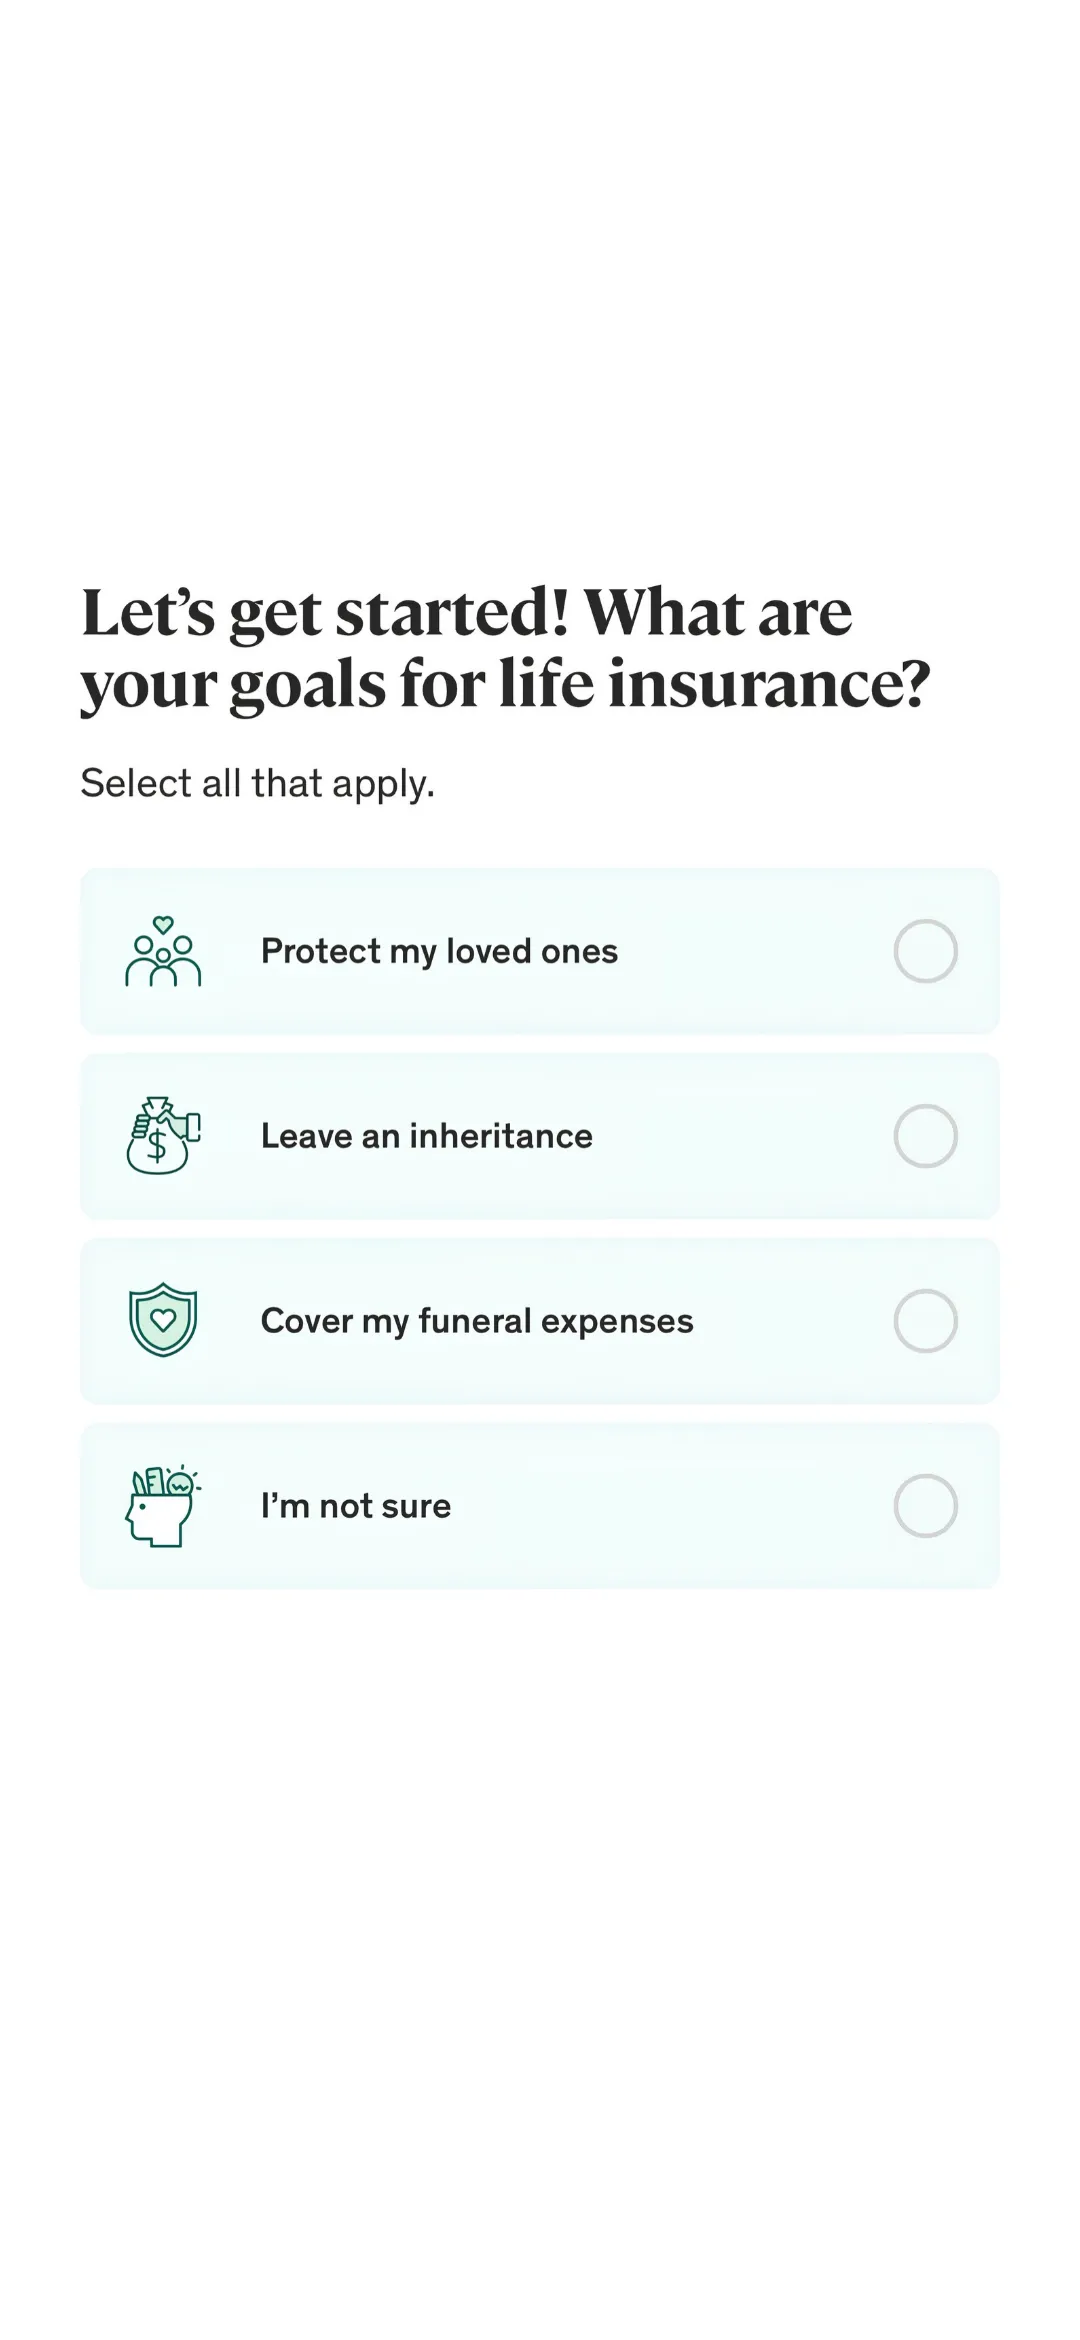


Ethos No-Exam Term Life
We calculate your rate live, so you can get coverage in 10 minutes or less, if approved.22
1/4: Tell us your goals for life insurance
Ethos uses automated underwriting, so many applicants can skip the traditional medical exam, bloodwork, urine testing, and nurse visit and get a decision quickly.922
Your health and prescription history still matter and can affect the rate, coverage amount, or policy you qualify for. If one product is not a fit, Ethos may be able to offer another option without making you start over.
No-exam options can include:
Ethos offers both term and permanent life insurance.58
Term life is generally used for larger temporary financial needs such as mortgage protection, income replacement, debt, and raising children.
Whole life is permanent coverage commonly used for burial expenses, final expenses, debts left behind, and money for beneficiaries.

Some people purchase both term and whole life for different purposes. For example, you may use a larger term policy to protect your mortgage and income during your working years while keeping a smaller whole life policy for permanent final expense coverage.
Using both can create a more complete life insurance plan by covering temporary financial responsibilities and permanent expenses at the same time.
Ethos term life insurance is designed for larger amounts of protection during the years you need it most. You choose coverage for a set period, and if you die while the policy is active, the issuing insurance company pays the death benefit to your beneficiaries.
People commonly use term life for income replacement, mortgage protection, debt, raising children, and other financial responsibilities that may not last forever.

Ethos uses its online application and underwriting system to determine which available term product, amount, and rate you may qualify for.
Ethos whole life insurance is designed for permanent coverage that can remain in force for your entire life, as long as required premiums are paid.
Unlike term life insurance, there is no 10-, 20-, or 30-year expiration date. The premium is level, so your monthly rate does not increase simply because you get older.
People often choose whole life for burial costs, funeral expenses, unpaid debts, money left to beneficiaries, and permanent coverage that will still be there after a term policy ends.

Issued by MEMBERS Life Insurance Company
Cash value is commonly misunderstood. It is not simply the total amount of premiums you have paid that you can later borrow back.
Your premiums pay for the life insurance contract itself. At the same time, the policy develops cash value according to the guarantees and schedule written into the contract.
As that cash value becomes large enough, you may be able to access it through a policy loan. Interest is charged on policy loans, and an outstanding balance can reduce the amount ultimately paid to your beneficiaries.8
One thing to notice: Many people use term life for mortgage and income replacement and keep whole life for permanent burial and final expense coverage. The two policies can work together for different financial needs rather than forcing you to choose only one.
Ethos Consumer Guide
View & Print the Ethos Whole Life Insurance Guide →A living benefit allows you to access part of your life insurance death benefit while you are still alive if you experience a qualifying illness or medical condition. These benefits are also commonly called accelerated death benefits because they let you receive part of the policy’s death benefit early.
Ethos Term Life – Choice can include Critical, Chronic and Terminal Illness Accelerated Benefits for eligible applicants. Depending on the qualifying condition, its severity, and its effect on life expectancy, eligible policyholders may be able to accelerate up to 90% of the policy’s death benefit.5
The money can be used for things such as:
Qualifying conditions can include major heart attack, stroke, invasive life-threatening cancer, organ transplant, paralysis, end-stage renal failure, and other listed conditions.
Generally includes being unable to perform at least two activities of daily living for at least 90 days or having a severe cognitive impairment.
Generally includes an illness or condition with a life expectancy of 12 months or less.
Ethos Term Life – Choice includes protection for 18 qualifying conditions through Ameritas for eligible applicants. Some applicants may receive only the Terminal Illness Rider.5
Ethos Consumer Guide
View & Print the Ethos Living Benefits Guide →If you are researching Ethos life insurance payout reviews, you are probably trying to answer a simple question before buying: what happens when the policy is actually needed?
The most important fact is that Ethos does not pay the death benefit itself. Ethos provides the application and digital buying experience, but the life insurance policy is issued by an insurance carrier. That carrier is responsible for reviewing the claim and paying the eligible death benefit according to the policy contract.1
After the insured dies, the beneficiary contacts the insurance company listed on the policy and starts a death claim. The carrier will usually ask for a completed claim form, a certified death certificate, proof of identity, and any additional documents needed to review the claim.4
The insurer then confirms that the policy was active, verifies the beneficiary information, and reviews any provisions that may apply. Once the claim is approved, the issuing carrier sends the death-benefit payment to the beneficiary.
Ethos explains that a life insurance claim usually takes about 14 to 60 days to process after the insurer receives a complete claim and the required documents.4
Some claims can move faster. Others may take longer if paperwork is missing, beneficiary information is unclear, the death occurs during the contestability period, or the carrier needs additional information before completing its review.
A claim being reviewed does not automatically mean it will be denied.
The most common payout is a lump sum, where the beneficiary receives the approved death benefit at one time.
Depending on the policy and insurance company, other options may also be available, including installment payments or an interest-bearing retained asset account. The options offered are determined by the issuing carrier.10
Life insurance payouts are governed by the terms of the policy. A lapsed policy, material misrepresentation on the original application, certain exclusions, outstanding policy loans, or a graded death-benefit period can affect the amount paid or whether a claim is payable.10
A contestability period is different from a waiting period. A death during the contestability period may result in additional review, but it does not automatically prevent the death benefit from being paid.10
Before activating an Ethos policy, confirm the issuing insurance company, coverage amount, beneficiary information, premium, and any waiting periods or policy limitations. Keep a copy of the policy somewhere your beneficiaries can easily find it and make sure they know which insurance company to contact when a claim needs to be filed.
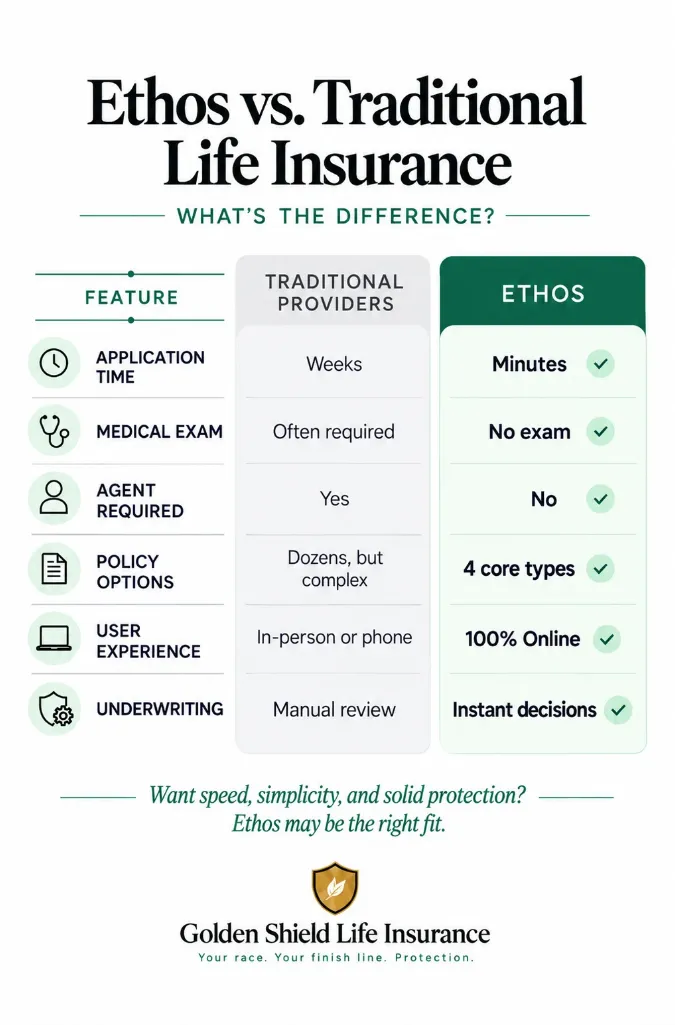
Compared with traditional life insurance companies such as State Farm, Northwestern Mutual, New York Life, and Globe Life, Ethos is built around a faster, more digital buying experience. Many Ethos applicants can apply online, answer health and lifestyle questions, receive an underwriting decision quickly, and activate coverage without scheduling a traditional medical exam.
Traditional companies may rely more heavily on agents, in-person meetings, longer underwriting, and medical exams depending on the policy. Ethos simplifies more of that process by keeping the application, underwriting, policy selection, and activation online.
Ethos also offers both term and whole life insurance, with eligible term applicants able to qualify for coverage up to $3 million.5 Eligible policies can also include living benefits, digital will and trust documents, and additional benefits through the Ethos Member Portal.
The biggest difference is the buying experience. Traditional life insurance may offer a more hands-on process, while Ethos is designed for people who want to apply online, see what they qualify for, choose their coverage, and get insured with fewer steps.
Ethos works well if you want to apply online and get a fast decision. It makes sense to compare other insurance companies when you want something Ethos may not offer, such as different riders, other term lengths, broader living benefits, or underwriting that treats your health history differently. Other companies may also price your age, health or tobacco use differently.
Compare your options if:
Because Golden Shield Life Insurance is an independent broker, we can show you an Ethos offer next to quotes from other companies. You can compare free life insurance quotes or book a call with a licensed broker.
Ethos Has Accomplished a Lot in 10 Years
Ethos has built a reputation for making life insurance faster and easier to buy online and has been recognized by Forbes Advisor, Money, CNBC Select, and NerdWallet, among others.
%20(1200%20x%20630%20px)%20(2).webp)
Families figure as of August 2026. Policy figures from Ethos’s 2025 annual report; the daily figure is the 2025 total averaged over 365 days.
Your Ethos policy can come with more than life insurance. Once your policy is active and your first payment has been made, you can log in to your Ethos Member Portal to access estate planning tools and additional policy perks.
Eligible Ethos policies include access to complimentary digital will and trust documents through Ethos Estate Planning, LLC. These tools can help you put important decisions in writing and organize your estate alongside your life insurance coverage. Availability varies by state.5
Your Ethos Member Portal can also include special offers for:5
When you purchase your policy through Golden Shield Life Insurance, we also provide access to our own private client resource library after your coverage is active.
Resources can include:
These Golden Shield Life Insurance resources are separate from the Ethos Member Portal. After your policy is activated, we provide you with the private link to access them.
Ethos Consumer Guide
View & Print the Ethos Policy Perks Guide →
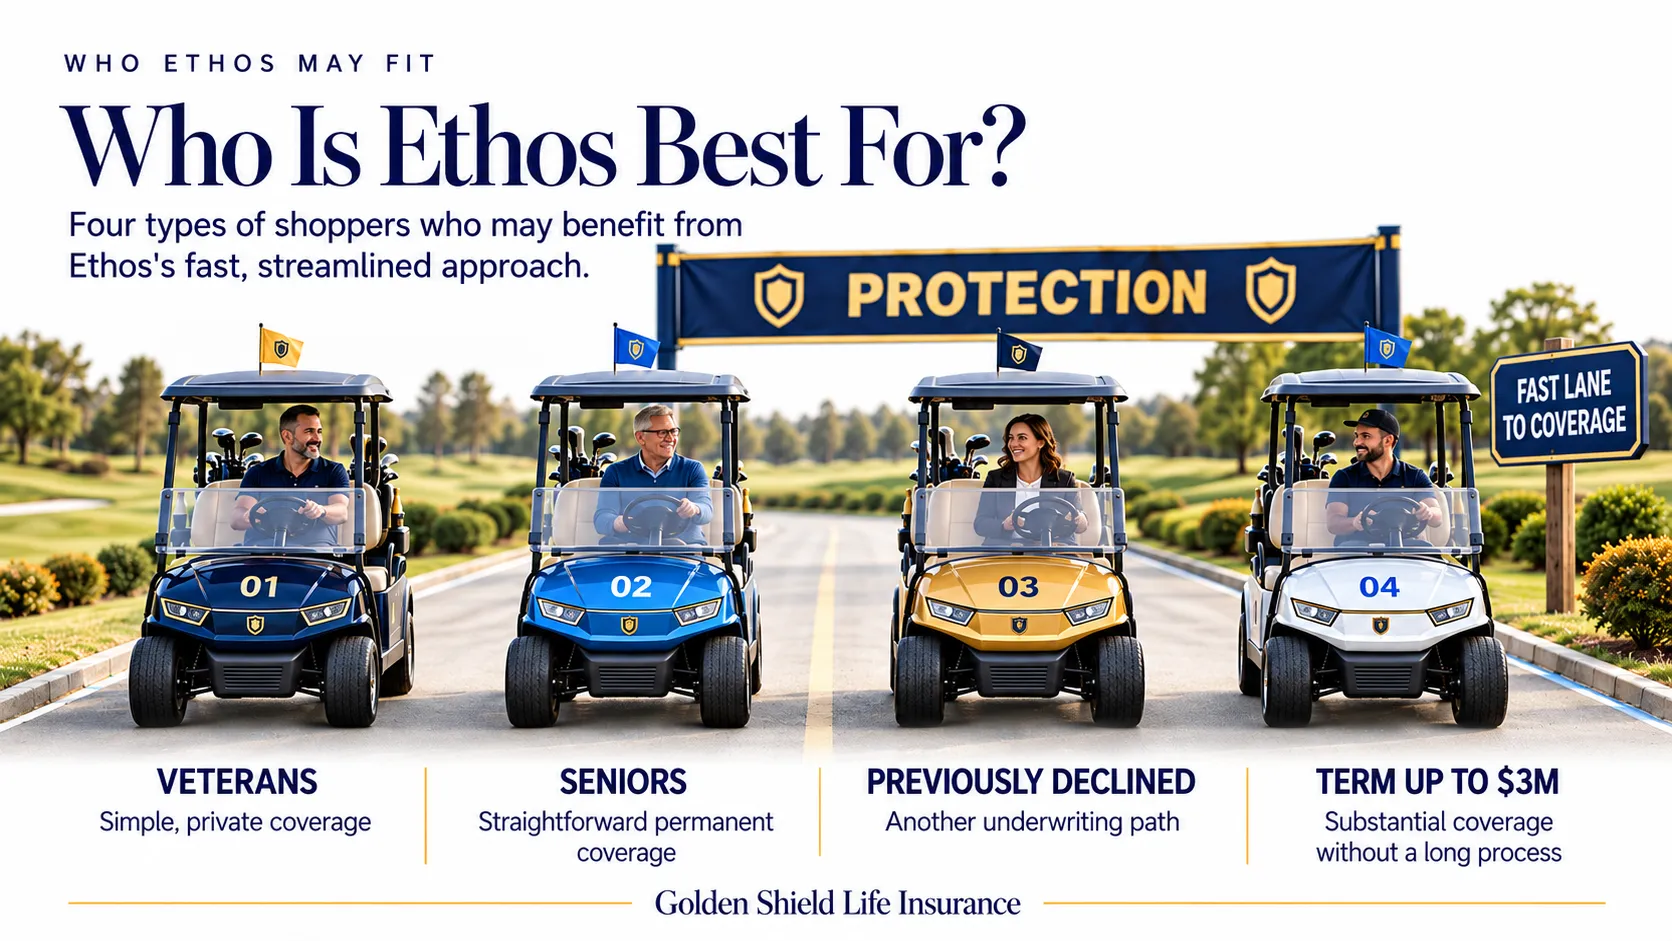
Ethos is a good fit for busy shoppers, healthy adults, seniors, and people who want a fast online life insurance process without scheduling a medical exam. It may also appeal to applicants who value privacy, digital convenience, and access to complimentary will and trust tools on eligible policies.
For the clients we work with, Ethos can be especially useful for veterans, seniors, people previously declined elsewhere, and term life shoppers who want a simpler path to coverage.
Ethos Guides for Your Stage of Life
Do I Need Life Insurance?In Your 30sIn Your 40sIn Your 50sNew ParentsNew MomsNewlywedsDual-Income FamiliesVeteransBusiness OwnersHomeownersSmokersWas this information enough to help you decide if Ethos Life Insurance is right for you and your family?
If you are comparing an Ethos policy or already have an offer, I can help you review the coverage, price, issuing carrier, living benefits, and policy features before you make your decision. I have firsthand experience working with Ethos products and helping clients through the application and underwriting process.
You can continue online and see what you qualify for, or schedule a call with a licensed agent for a second opinion.
Yes, Ethos can be a good option for seniors because it offers permanent whole life coverage for eligible applicants up to age 85, including guaranteed-acceptance options for certain ages.5
Ethos prices each policy individually. Your rate depends on your age, health, tobacco use, coverage amount, term length, policy type, the underwriting class you qualify for, the issuing insurance company and your state. Ethos shows your price during the online application, and we can compare it with quotes from other companies at no cost.
If Prime is not available to you, Ethos may consider you for other available products such as Term Life Choice or a whole life option based on your age, health, and eligibility. An alternative offer is not guaranteed.5
Ethos may decline, reprice or offer a different policy based on medical history, prescription history, current health conditions, age or coverage limits, tobacco use, driving history, financial details or the issuing carrier’s rules. A decline from Ethos does not mean you cannot get coverage elsewhere, because each insurance company sets its own underwriting rules.
Yes, you may be able to qualify for more than one Ethos policy, subject to underwriting, financial justification, and total coverage limits.
You will generally need basic personal and beneficiary information along with details about your health, medications, lifestyle, finances, and the amount of coverage you want.
Ethos may ask about your medical history, prescriptions, height and weight, nicotine use, lifestyle, driving history, and financial information used to determine eligibility and coverage.
Ethos does not pay claims itself. The insurance company that issued your policy reviews the claim and pays the eligible death benefit. Ethos says a claim usually takes about 14 to 60 days once the insurer receives a complete claim and the required documents.4
Yes. Every Ethos policy comes with a 30-day money-back guarantee, so you can cancel for a full refund of premiums during that time. After 30 days, Ethos says you can cancel anytime with no extra fees.3
The price is the same either way, because the premium is set by the insurance company. Buying through Golden Shield Life Insurance, an appointed Ethos agent, adds a licensed broker who can compare your Ethos offer with other companies, help if you are declined, and answer questions after your policy is active.
We work for you, not the insurance companies. We answer the phone 7 days a week and help with quotes, policy reviews, coverage questions, and underwriting concerns.
We explain the coverage, benefits, costs, limitations, and fine print so you understand exactly what you’re buying.
Ethos offers good life insurance options, but may not include every extra layer in riders, supplemental benefits, or retirement income options you possibly might need.
If you purchase an Ethos policy online through us, thank you for trusting me and my company. We will still call to introduce ourselves, review your coverage, and make sure all of your questions are answered.
Enter your information below to see your Ethos price.
Written and Reviewed By
I’m the founder of Golden Shield Life Insurance, a licensed agent and independent broker who works for you, not the insurance companies. I specialize in all types of life insurance coverage, from term to whole life insurance and mortgage protection, and I help individuals and families, seniors, veterans, and business owners protect themselves and their loved ones.
We serve clients across the country and were named a 2025 Best of Georgia Regional Winner in Insurance Agencies and received a 2026 honorable mention.20 You can read our client reviews to see what it is like to work with us online, by phone, or in person. If you have been declined before or have a complicated medical history, contact us.
Ethos in the News
Insurance Innovation Reporterhttps://iireporter.com › ethos-expands-banner-life-offering
Mar 26, 2026 · What this means for buyers: Ethos now offers two more ways to get permanent final expense coverage issued by Banner Life. Simplified Issue Whole Life uses a short set of health questions, and Guaranteed Issue Whole Life asks no health questions, giving more eligible families an option to cover burial and end-of-life costs.
Read the full article →Last reviewed: November 12, 2026. This page is reviewed and updated as Ethos products, carriers, ratings, and policy features change.
Facts on This Page Are Supported By
Ethos and Carrier Sources
Industry and Regulatory Sources
Ratings, Reviews, and Awards
Ethos Company Data
Ethos Consumer Guides
English
Español
Important Disclosures