Life insurance for veterans can protect your spouse, children, mortgage, or business after military service. Compare private term, whole life, final expense, and no-medical-exam options, including coverage that may supplement existing military benefits, and request veterans life insurance quotes with a licensed independent broker. Golden Shield Life Insurance is not affiliated with the U.S. Department of Veterans Affairs.
Written By:
Licensed & Reviewed
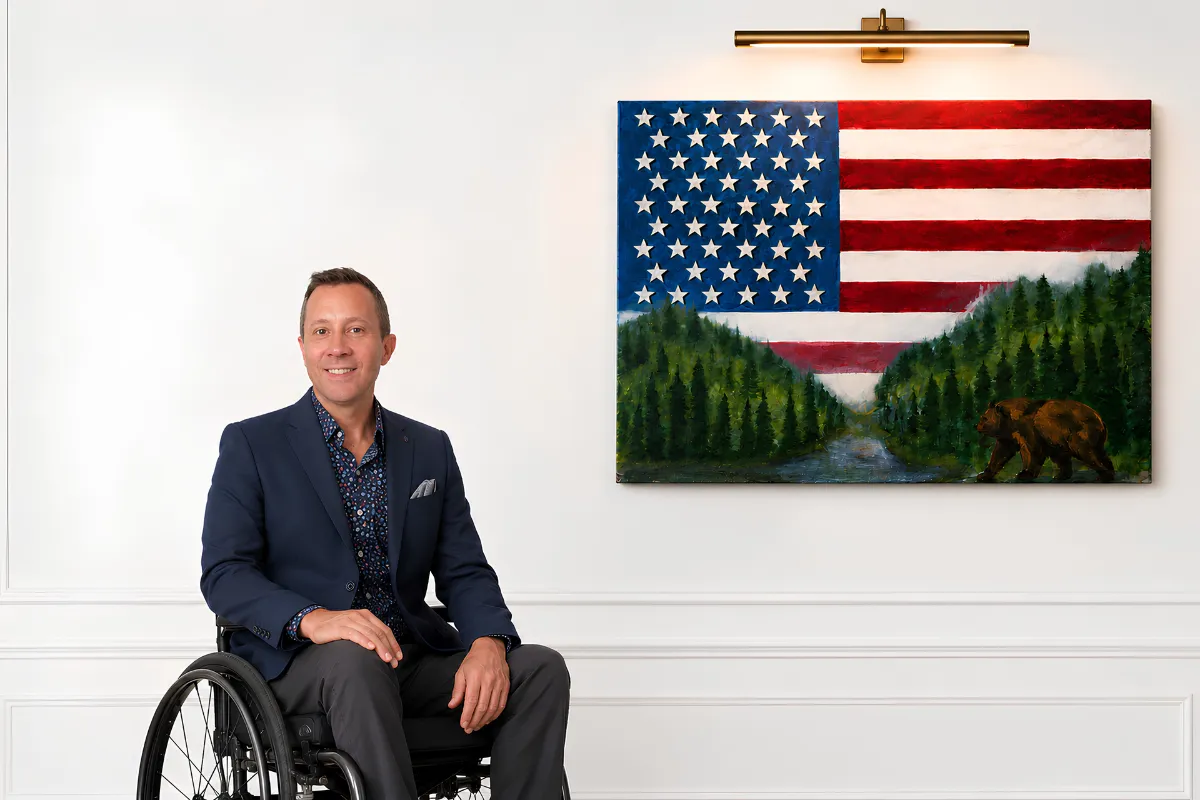
Aaron PolkAaron Polk founded Golden Shield Life Insurance after his father, a Green Beret, was nearly scammed while shopping for life insurance before moving to the Philippines. As a licensed independent agent in Atlanta, he compares 130+ carriers so veterans and their families can buy private coverage with confidence. Read more on LinkedIn
Private Life Insurance for Veterans: Buyer's Guide
Already have military or VA coverage? Start by checking your current death benefit, then compare private policies based on your family's needs and budget.
Key Takeaways
Term life generally costs less for a larger, temporary need.
Whole life offers lifetime coverage and cash value, subject to policy terms.
Final expense and some no-exam policies may suit smaller or harder-to-insure needs.
Coverage and prices depend on the insurer, your age and health, and the policy.
Editor's Note
My father served as a Green Beret, and my grandfather served as a tank driver during World War II. Before my father moved to the Philippines, he wanted to put life insurance in place, and he was nearly scammed in the process. It was a nightmare for our family, and it is the reason I built Golden Shield Life Insurance: so veterans can shop for and buy private life insurance for themselves and their family members with someone they can trust. I did not serve in the military myself. I want you to understand what you already own before you buy more.
A policy can help your beneficiaries replace income, pay a mortgage or VA home loan, cover funeral costs, support children, or settle business obligations. Whether you recently separated or are retired military, you can own private coverage alongside eligible military or VA benefits.
How Much Life Insurance Do Veterans Need?
Add up the income your family would need, your mortgage and other debts, education, and final expenses. Subtract savings and existing insurance. The difference is a starting point, not a required purchase amount.
No personal details needed. Helps veterans see gaps in their plans.
Example: A Family With Two Children
Here is an illustrative coverage calculation for a married 40-year-old veteran earning $60,000 a year.
Financial Need
Amount
Seven years of income replacement
$420,000
Mortgage balance
$250,000
Debt and final expenses
$25,000
Education funding
$100,000
Existing life insurance and savings
− $95,000
Estimated Coverage Gap
$700,000
Illustration only. Actual needs, existing benefits, and available policies differ.
Nate's Story
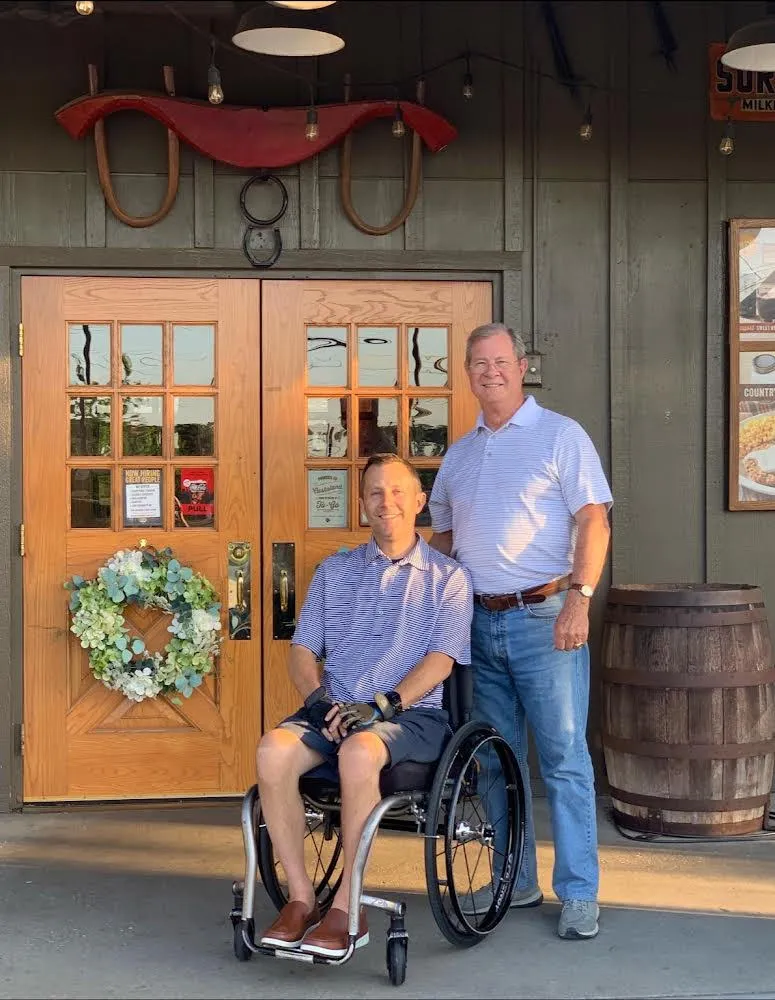
Golden Shield Life Insurance helped us with our two kids. My wife and mother get life insurance with benefits. They actually care and understand that people matter.
Golden Shield Life Insurance helped us with our two kids. My wife and mother get life insurance with benefits. They actually care and understand that people matter.
What Types of Private Life Insurance Can Veterans Buy?
Term life: Coverage for a set period, commonly 10, 20, or 30 years. Often useful for income replacement or a mortgage, and often the most budget-friendly way to buy a large amount of coverage.
Whole life: Permanent insurance with generally fixed premiums and cash value, provided required premiums are paid.
Final expense: Smaller permanent policies often used for funeral costs and remaining bills, sometimes called burial insurance for veterans. Older veterans can also read our guide to life insurance for seniors.
No-exam or guaranteed issue: Some policies, including life insurance with no medical exam, do not require an exam. Guaranteed issue life insurance asks no health questions at all. Guaranteed issue typically has lower coverage limits and an initial limited-benefit period.
Mortgage protection: Term coverage that may help surviving family members pay off a home loan.
Compare Private Policy Types
Policy Type
Good Fit For
How Long It Lasts
Cash Value
Medical Exam
Term Life
Income replacement, a mortgage, raising children
10 to 30 years
No
Often required; no-exam options may be available
Whole Life
Lifelong coverage, final expenses, legacy planning
Lifetime
Yes
Usually required, depending on the amount
Final Expense
Funeral costs and small remaining bills
Lifetime
Limited
Usually no exam, health questions only
Guaranteed Issue
Serious health conditions
Lifetime
Limited
No exam or health questions; benefits may be limited in early years
Veterans life insurance rates for private policies depend on age, coverage amount, policy length, tobacco use, and health history. Term life usually offers more coverage per dollar than whole life. Compare real quotes with matching death benefits and policy terms.
Life Insurance for Disabled Veterans
A VA disability rating does not by itself decide whether a private insurer will cover you. Private insurers look at your health history, medications, and current condition, and each company weighs them differently. The same veteran can be declined by one insurer and approved by another.
Veterans with a service-connected disability rating may also be eligible for VALife, the VA's guaranteed acceptance whole life program.2 Private options include fully underwritten policies, simplified issue final expense, and guaranteed issue life insurance with no health questions.
"I use a wheelchair, and when I shopped for my own coverage, guaranteed issue was what I could qualify for. I know what it feels like to hear no. I look at every option, VA and private, before I recommend one." Aaron Polk
Should You Choose Term or Whole Life?
Choose term for a temporary financial need, such as protecting income while children are growing up. Consider whole life for lifelong coverage, final expenses, or cash value. Some people combine both. For a deeper look, read our guide to term vs. whole life insurance for veterans, or compare whole life insurance quotes.
For term life, I often compare Mutual of Omaha, Banner Life, and Fidelity Life. For whole life and final expense, I often compare Americo, Baltimore Life, and Ethos, an online platform whose policies are issued by partner insurance companies. Which one fits depends on your age, health, coverage amount, and how each company underwrites.
Choose Term Life
Temporary Need
Mortgage Protection Insurance
Income replacement
Raising children
Budget-friendly coverage
Choose Whole Life
Lifetime Need
Final expenses
Cash value growth
Legacy planning
Lifelong dependents
Compare Term and Whole Life
Feature
Term Life Insurance
Whole Life Insurance
How long it lasts
10, 15, 20, or 30 years
Your entire life, as long as premiums are paid
Monthly cost
Usually lower
Usually higher
Cash value
No
Yes, subject to policy terms
Best for
Temporary financial needs
Permanent financial needs
Coverage amount
Often allows higher death benefits for the same budget
Often purchased in smaller amounts because of the higher premium
Key Takeaway: There is no single best coverage option, only the one that is best for you and your family. The better policy is the one that matches the length of your financial responsibility, your long-term goals, your budget, and the type of coverage you want to own.
What About Existing Military or VA Life Insurance?
Before buying private coverage, check what you already have. Eligible SGLI generally continues for 120 days after leaving service. If you are totally disabled when you separate, the SGLI Disability Extension may keep that coverage at no cost for up to 2 years, but you must apply for it.4VGLI has its own application deadlines and age-based premiums, and VALife is a separate VA whole life program.12
If you are leaving the military, verify your options directly with the VA on VA.gov life insurance or by calling the VA Insurance Center at 800-669-8477. Golden Shield Life Insurance sells private policies, not VA benefits.
VGLI vs. VALife vs. Private Life Insurance
VGLI and VALife are government programs run by the VA. Golden Shield Life Insurance does not sell them. Private policies are issued by commercial insurance companies, and those are the policies we compare for you. Here is how they compare.12
VGLI
VALife
Private Coverage
Who can apply
Former SGLI members, within 1 year and 120 days of separation
Veterans age 80 or younger with a service-connected disability rating, including 0%
Anyone who qualifies with the insurer
Coverage amount
Up to your SGLI amount at separation
Up to $40,000
Varies by insurer and policy
Health questions
None if you apply within 240 days of separation
None, guaranteed acceptance
Usually, depending on the policy
Premiums
Increase with age
Fixed once locked in
Depend on the policy type
Waiting period
None
2 years before the full benefit applies
Usually only on guaranteed issue plans
If you are in good health, a private policy may cost less than VGLI as you get older. If you have serious health conditions, applying for VGLI inside the 240-day window or for VALife may be the stronger choice. Many veterans keep one and add the other.
Why Compare Policies Through an Independent Broker?
Different private insurers may offer different prices, coverage amounts, and underwriting decisions for the same applicant. Golden Shield Life Insurance helps you compare veterans life insurance quotes from multiple insurance companies without charging a fee for quotes.
The best life insurance for veterans depends on age, health, budget, and coverage needs. For term life insurance and income protection, I often recommend Mutual of Omaha, Banner Life, and Fidelity Life for their pricing, flexible coverage amounts, and no-medical-exam options for eligible applicants. For permanent whole life insurance, cash value, and final expense coverage, my preferred choices are Americo, Baltimore Life, and Ethos. Ethos is an online platform, and its policies are issued by partner insurance companies. As a former national medical underwriter and licensed life insurance broker, I recommend comparing multiple carriers to find coverage that protects your family and fits your long-term needs.
Do veterans get life insurance for free?
Not permanently. SGLI coverage generally continues for 120 days after separation at no cost. If you are totally disabled when you leave the military, you may be able to apply for the SGLI Disability Extension, which can continue your coverage at no cost for up to 2 years. It is not automatic. After free coverage ends, veterans pay premiums to keep coverage, whether through VGLI, VALife, or a private policy. Golden Shield Life Insurance helps veterans compare private coverage with guidance from a licensed independent broker.
How much does life insurance for veterans cost?
Prices depend on age, health, tobacco use, policy type, and coverage amount. There is no single veteran rate for private insurance.
Can disabled veterans qualify for private life insurance?
Yes, depending on the insurer and policy. A VA disability rating does not by itself decide private eligibility. Private insurers look at your health history, medications, and current condition. Veterans with a service-connected disability rating may also be eligible for VALife, the VA's guaranteed acceptance whole life program.
What are the VA disability perks compared to private life insurance with living benefits?
VA disability compensation is tax-free monthly income for service-connected conditions, and eligible veterans may also receive VA health care and other assistance. Private life insurance with living benefits adds a different kind of protection: depending on the policy and rider, you may be able to access part of your death benefit while still alive if diagnosed with a qualifying critical, chronic, or terminal illness. Using a living benefit reduces the death benefit your beneficiaries receive, and rider availability varies by insurer and state. Unlike VA disability benefits, private living benefits are not limited to service-connected conditions. Having both can help veterans protect their income, savings, and families when life takes an unexpected turn.
Can veterans buy life insurance without a medical exam?
Some insurers offer no-exam options. Approval may still depend on health questions or records. Guaranteed issue plans typically have smaller benefits and early coverage limitations.
Can I keep VA insurance and buy a private policy?
Yes. Eligible veterans can generally own private life insurance alongside VA coverage. Review existing benefits before adding coverage.
What happens to SGLI after leaving military service?
SGLI coverage generally continues for 120 days after separation at no cost. If you are totally disabled at separation, you may be able to apply for the SGLI Disability Extension, which can continue free coverage for up to 2 years. To keep VA group coverage, you can apply for VGLI within 1 year and 120 days of separation. If you apply within 240 days, you will not have to answer health questions. If you receive the Disability Extension, VGLI can begin when the extension ends.
What is the difference between VGLI and private life insurance?
VGLI is VA group term coverage for former SGLI members, issued up to the SGLI amount you had at separation, with premiums that increase as you age. Private life insurance is issued by a commercial insurer, and rates and coverage depend on your age, health, and the policy you choose. Veterans in good health may find lower private rates, while veterans with serious health conditions may benefit from applying for VGLI within the 240-day no-health-questions window.
Your shield is ready. Are you?
Something went wrong sending your request. Please try again, or call or text us at (678) 884-4653.
Protect what matters, at a premium you can keep paying. Review your existing coverage, compare private policies, and choose an amount that fits your family. We can help you review quotes with no pressure.
Aaron Polk
Founder, Golden Shield Life Insurance
Have Questions? Talk With Aaron Polk
Call, text, or schedule a time that works for you. We listen, explain the fine print, and compare your options with no pressure.
Founder, Golden Shield Life Insurance Former National Medical Underwriter and Licensed Life Insurance Broker · Georgia License 3710928 · NPN 21216745 · Georgia Agency License 242517
Aaron Polk built Golden Shield Life Insurance after his father, a Green Beret, was nearly scammed while trying to buy life insurance before moving to the Philippines. Today the agency helps veterans and their family members shop and buy private life insurance, with an office in Atlanta and licensed agents who work with clients nationwide by phone and video. He compares more than 130 insurance companies rated A- or better by AM Best.
How this guide was made: Written by a licensed agent from first-hand casework, not compiled from other insurance websites. Government program details and deadlines are checked against the numbered references in the disclaimer below, each of which is linked. Terms are confirmed again at the time of quoting.
Disclaimer
Updated November 2026
This page is educational and is not financial, legal, or tax advice.
Golden Shield Life Insurance is not affiliated with, endorsed by, or acting on behalf of the U.S. Department of Veterans Affairs or any government agency.
SGLI, SGLI Disability Extension, VGLI, and VALife details are summarized from VA sources. Government program rules, rates, and deadlines can change. Confirm current terms with the VA Insurance Center at 800-669-8477.
This page does not quote premiums. Private coverage, pricing, riders, issue ages, and availability vary by insurance company, state, age, health, and policy terms.
The family example and coverage worksheet are for educational purposes only. Your needs and available benefits may differ.
Client stories are shared with each client's permission. Individual results vary.
Golden Shield Life Insurance does not promise approval, pricing, or benefit eligibility. The policy contract controls.
References
1U.S. Department of Veterans Affairs. Veterans' Group Life Insurance (VGLI): SGLI coverage continuing for 120 days after separation, VGLI application deadlines, and age-based premiums. va.gov VGLI
2U.S. Department of Veterans Affairs. Veterans Affairs Life Insurance (VALife): a separate VA whole life program for eligible veterans with a service-connected disability rating. va.gov VALife
4U.S. Department of Veterans Affairs. Servicemembers' Group Life Insurance (SGLI), including the SGLI Disability Extension for members who are totally disabled at separation. va.gov SGLI
 Aaron Polk
 founded Golden Shield Life Insurance after his father, a Green Beret, was nearly scammed while shopping for life insurance before moving to the Philippines. As a licensed independent agent in Atlanta, he compares 130+ carriers so veterans and their families can buy private coverage with confidence.
Read more on LinkedIn