Final expense insurance coverage explained by Golden Shield Life Insurance

Final Expense Insurance Coverage

Plan for the costs that come after a death, so your family can focus on each other.

Updated 6 min read

Final expense insurance coverage is a whole life insurance policy that pays a cash death benefit to the beneficiaries you name. Coverage amounts are usually modest, often between about $2,000 and $50,000. After an approved claim, the person you name receives the money and decides how it is used, whether that is a funeral, burial or cremation, remaining medical balances, debts, or travel for family.

Because the benefit goes to a named beneficiary, it generally passes outside probate. How much you can apply for depends on your age, health history, the carrier, and your state.

Listen to This Guide

Final Expense Insurance

Loading the audio...

AI audio made from this written guide and reviewed by a licensed agent.

Google See Our Reviews Start My Quote

Final Expense Insurance Comparison Guide

This guide helps you:

  • Compare policy benefits, limits, and underwriting choices
  • Understand how the stages of a quote affect your real cost
  • Check the fine print, the riders, and the payment details
  • Verify agents and spot common red flags before you buy
Editor's Note

An insurance license confirms someone is authorized to sell. It does not tell you their experience, or how they treat clients after the sale. Working with an independent broker may save you time and effort, and can turn up a lower premium, because we compare several companies side by side instead of leaving you to contact each one.
Hi, I am Aaron. Click to call Golden Shield Life Insurance at (678) 884-4653

No cost, no obligation. No medical exam options may be available for qualified applicants.

Quick Comparison Checklist

Always compare written policy offers, not online estimates. Match the exact coverage amount, then line up premiums, benefit schedules, riders, and payment terms. [1]

  • Written offers only. Compare issued documents, not estimated quotes.
  • Equal payouts. Match the exact coverage amount across every offer, $15,000 against $15,000.
  • Confirm the schedule. Verify in writing when the full death benefit becomes available.
  • Check the premium terms. Payment method, fees, grace period, and how long you pay.
  • Keep existing coverage. Never cancel a current policy until the new one is issued and reviewed. [1] [4]
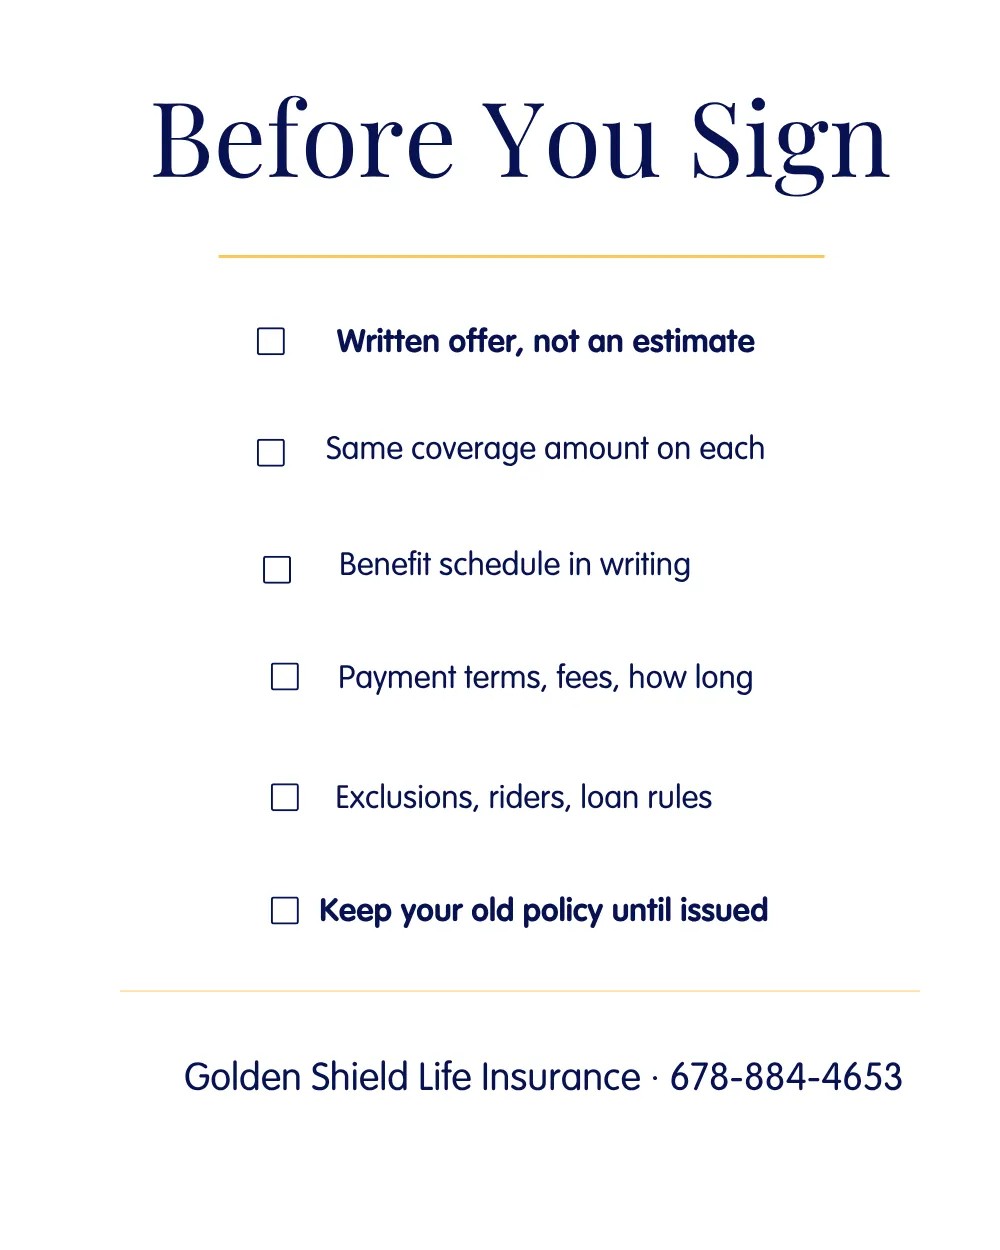
Checklist of six things to confirm before signing a final expense insurance offer

Stages of Getting Quotes

Not every number you are shown is a final offer. Here is what each stage actually is.

StageWhat it actually isAre you covered?
Estimated quoteA price estimate based on what you told us. Nobody has checked anything yet. The number can change.No
ApplicationYour signed request for coverage, plus permission for the company to check records. It starts the review.No
Underwriting decisionThe company's answer. It may approve you as applied for, offer a different price, or decline. This is where the benefit schedule gets set.No
Issued policyThe contract exists, has been delivered, and the first premium is paid. Your free look period starts here.Yes, under the contract terms

Policy Comparison

Always compare identical death benefits. A $15,000 policy cannot be fairly measured against a $10,000 policy. Use this worksheet to track the written details side by side.
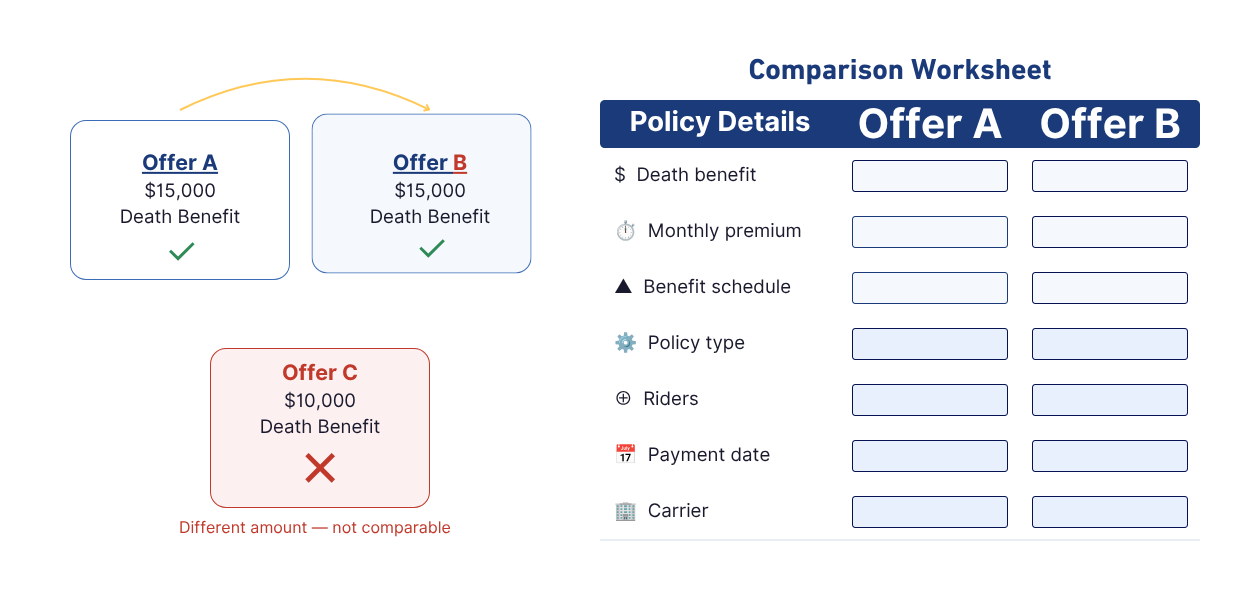
Comparison worksheet showing two matched $15,000 final expense offers alongside a $10,000 offer marked not comparable, with blank rows for death benefit, monthly premium, benefit schedule, policy type, riders, payment date, and carrier

Review Premium Details

Look beyond the monthly price. The billing fine print changes your real cost and decides whether the policy stays in force.

  • Billing method and fees. Check whether the rate assumes an automatic bank draft. Paying by check or card can add a fee.
  • Effective date. Confirm when payment is due and whether coverage begins right away or after the funds clear.
  • Payment length. Ask whether premiums continue for life or stop at a stated age while coverage continues.
  • Grace period and lapses. Find out how many days a late payment is allowed, and whether restarting a lapsed policy requires new health questions.

Policy Rules and Benefit Schedules

The written contract controls your coverage. A marketing brochure does not. Review these terms.

  • Benefit schedule. Confirm whether the full amount is payable from day one, or limited during an early period, often about the first two years.
  • Riders and living benefits. A payout for terminal illness or accidental death may cost extra, and using one early reduces the death benefit. [2]
  • Loans and withdrawals. Borrowing against cash value reduces what your beneficiaries receive and can end the policy.
  • Contestability period. Usually the first two years. In that window the company can review your application answers before paying a claim. [2]
Full definitions of level, graded, and modified benefits are on the final expense insurance guide.
Two daughters with their grandmother, the family a final expense insurance policy is meant to protect
Two daughters with their grandmother.

Agent and Company Verification

Run these checks before you sign anything or send money.

  • Check licenses. Confirm the agent has an NPN (National Producer Number) and that the agent and the insurance company are licensed in your state. [3]
  • Pay the company. Make checks or bank drafts payable only to the insurance company, never to a person.
  • Keep paper records. Save the application, the policy, payment receipts, and the company's contact details.
Your state regulators publish their own Life Insurance Buyer's Guide through the National Association of Insurance Commissioners. Read it before you buy from anyone, including us.

Pre-Purchase Red Flags

Stop and ask questions if you run into any of these.

  • No written schedule. The agent will not put the benefit terms in writing.
  • Unexplained price change. The quoted rate jumps after you apply and nobody explains why.
  • Pressure to cancel. You are told to drop an existing policy before the new coverage is active. [1]
  • Misleading pitch. The policy is sold as a savings account, an investment, or a wealth strategy.
  • No public footprint. No verifiable address, no business profile, no reviews you can find.

The Free-Look Period

State law gives you a window after the policy is delivered, often about 10 to 30 days, to read it and return it for a refund under the policy and state rules. [1]

  • Check the first page. The exact number of days is printed on the policy cover sheet.
  • Verify the information. Names, dates of birth, beneficiaries, coverage amount, and premium.
  • Act quickly. Report anything wrong, or return the policy, before the window closes.

Before You Buy, Let Us Review Your Quotes

Golden Shield Life Insurance compares quotes, benefit schedules, and issued offers side by side, at no extra cost to you.

Why Compare With Us

  • Independent brokerage. We are not captive to one company. We search several top-rated carriers for options that fit your situation.
  • Free to you. No broker fee and no added charge. Licensed agents are paid by the company when a policy is placed. [2]
  • Policy audits. Bring a quote you already have. We will read the fine print, explain the early payout rules, and point out fees that change your real cost.
Compared Across Top-Rated Carriers [5]
Mutual of Omaha Baltimore Life Foresters Financial Corebridge Financial Americo AM Best

Call, compare, and apply today.

New policies may include a free burial guide, and select policies include a free will.
Free will with select life insurance policies Free burial guide for new policyholders

Common Questions

FAQ about Comparing Final Expense Offers

What should I compare in a final expense insurance quote?

Compare the death benefit, monthly premium, benefit schedule, policy type, how long premiums last, riders, exclusions, and the insurance company. Make sure each quote uses the same coverage amount.

Is an online final expense quote the final price?

Not always. An online quote is usually an estimate. The final premium and the policy terms may change after the company reviews your age, health history, medications, tobacco use, and state of residence.

Why do two policies with the same coverage amount cost differently?

Companies use different underwriting guidelines, benefit schedules, policy fees, and pricing. One may view your health history more favorably than another.

Is the lowest-priced final expense policy the best choice?

Not necessarily. A lower premium may come with a more limited early-policy benefit, fewer riders, or different contract terms. Compare the full offer, not only the price.

How do I know whether a policy has a waiting period?

Review the written benefit schedule and the policy specifications. Look for terms such as level, graded, modified, or limited benefit. Ask the agent to show you where the provision appears in writing.

Level, graded, and modified benefits are explained in full on the final expense insurance guide.

Should I cancel my current policy after applying for a new one?

No. Keep existing coverage until the new policy has been approved, issued, delivered, and reviewed. [1]

Can a broker compare policies from several insurance companies?

An independent broker may compare options from multiple companies, subject to the companies the broker represents and the products available in your state.

Does using an independent broker cost more?

Consumers generally do not pay a separate broker fee for a standard life insurance application. Licensed agents are typically compensated by the issuing company when a policy is placed. [2]

Can Golden Shield Life Insurance review a quote I already received?

Yes. Golden Shield Life Insurance can help compare an existing quote or issued offer with other available options, and explain differences in premiums, benefit schedules, and policy terms.

Your shield is ready. Are you?

Thank you. Your request is in. A licensed agent at Golden Shield Life Insurance will reach out shortly to match you with your options.
Something went wrong sending your request. Please try again, or call or text us at 678-884-4653.

Read This Before You Buy From Anyone

National Association of Insurance Commissioners
content.naic.org › publication-lig-lp-consumer-life
Life Insurance Buyer's Guide

National Association of Insurance Commissioners · Consumer publication

Written by the state regulators who oversee insurance companies, not by anyone selling a policy. It walks through deciding how much coverage you need, comparing policy types, and reading what you are sent. Two points are worth carrying into any comparison. A policy that does not require detailed health information usually costs more and provides less coverage than one that does, which is the trade behind most no-exam plans. And a policy should not be cancelled until the replacement has been issued and reviewed. The guide closes with what to check when your contract arrives and how long you have to return it. Read it before you buy from anyone, including us.

Read the full guide

Disclaimers

Aaron Polk, founder and licensed agent at Golden Shield Life Insurance

Aaron Polk

Founder & CEO, Golden Shield Life Insurance · Licensed Life Insurance Agent · NPN 21216745 · Georgia Agency License 242517

Aaron founded Golden Shield Life Insurance after a 2007 accident showed him how fast a steady life can change. He compares more than 130 carriers to help families find honest coverage, with a focus on older applicants and people other agents pass over.

How this page was made: Written by a licensed agent from first-hand casework reviewing quotes, underwriting decisions, and issued policies for clients. The guidance on what to compare, where the benefit schedule appears, and how to verify an agent is checked against the public regulator sources below, each of which is linked so you can read it yourself. No premium figures are published here because a real price depends on your age, health, state, and the company reviewing your application.

Last reviewed: . This page is reviewed and updated as products, regulations, and carrier practices change.

Free Printable Resources

Print or download our free Burial & Cremation Guide, Final Wishes planner, Free Will and Family Planner, Veterans Will & Burial Kit, and more. No sign-up or purchase required.

Visit Free Family Resources
Disclaimers View

Carrier and Product Brochures

Brochures from insurance companies we work with, plus our own living benefits guide. Each opens as a PDF you can read, download, or print.

Brochures are published by each insurance company and describe its own products. Availability, benefits, and pricing vary by state and are governed by the policy you receive.

Facts on This Page Are Supported By

  • 1NAIC Life Insurance Buyer's Guide. Prepared by the National Association of Insurance Commissioners. Supports the guidance on comparing policy types before buying, the point that a policy requiring less health information usually costs more and provides less coverage, the instruction not to cancel an existing policy until the new one is received, the caution against naming a minor child as a beneficiary, and the free-look period stated on the first page of a contract. Accessed July 2026. content.naic.org buyer's guide
  • 2NAIC, National Association of Insurance Commissioners. Consumer guidance on life insurance. Supports the whole life framework behind final expense, the definitions of accelerated death benefit and other riders, and the point that premiums are generally the same whether a policy is bought through an agent or directly. Accessed July 2026. content.naic.org consumer guide
  • 3NAIC State Insurance Department Directory. Supports the instruction to verify an agent and an insurance company with your own state regulator, which also takes consumer complaints. Accessed July 2026. state insurance departments
  • 4Georgia Office of Insurance and Safety Fire Commissioner. "Life Insurance" consumer resource. Supports the guidance not to cancel existing coverage until a new policy has been issued and reviewed. Accessed July 2026. life insurance resource
  • 5AM Best. Insurer financial-strength rating lookup. Supports checking whether an insurance company is rated and able to pay claims before you apply, and the point that no single company is best for every applicant. Accessed July 2026. ambest.com
  • 6NAIC Life Insurance Policy Locator. A free national tool that helps families search for a deceased relative's lost life insurance policy and connect with unclaimed death benefits. There is no cost to use it and no need to contact us first. Accessed July 2026. eapps.naic.org policy locator

Disclaimers

  • Golden Shield Life Insurance is not affiliated with, endorsed by, or acting on behalf of the U.S. Department of Veterans Affairs, the Social Security Administration, Medicare, or any other government agency. Government program information on this page is provided for education only. Confirm benefits and eligibility directly with the agency.
  • Final expense insurance is life insurance. It is not a preneed insurance contract, a prepaid funeral agreement, or a savings plan. The benefit is paid to the person you name, and no policy guarantees that its proceeds will be enough to pay for any particular funeral service, merchandise, or provider.
  • Golden Shield Life Insurance is an independent life insurance agency and brokerage based in Atlanta, Georgia. We are not an insurance company and we do not underwrite, issue, or administer policies. Every policy is underwritten and issued by a third-party insurance carrier licensed in the state where it is sold, and all benefits are paid by that carrier under the terms of its contract.
  • There is no fee for our services. Licensed agents are compensated by the issuing carrier when a policy is placed. The companies a broker can compare are limited to those the broker represents and the products available in your state.
  • This page is educational and is not financial, legal, or tax advice.
  • Coverage, pricing, riders, issue ages, benefit schedules, and product availability vary by carrier, state, age, health, and policy terms. Applying does not guarantee approval.
  • Graded and modified benefit plans may pay less than the full death benefit during an initial period. Read the benefit schedule in your policy.
  • Depending on how long a policy is held, the total premiums paid may exceed the death benefit. A policy that lapses for nonpayment may end coverage, and reinstatement is not guaranteed.
  • Policy loans and withdrawals reduce the death benefit and any cash surrender value, may cause a policy to lapse, and may have tax consequences.
  • Accelerated or living benefits reduce the death benefit left for your beneficiaries, are not long-term care insurance, and may affect eligibility for Medicaid, Supplemental Security Income, or other need-based public assistance. Consult a qualified tax professional or attorney about your own situation.
  • Free-look periods, contestability periods, and replacement rules are set by your policy and your state. Read the first page of the contract.
  • Complimentary items offered with a policy are subject to availability, eligibility, and applicable state law, and are not a condition of purchase.
  • Outbound links are provided for reference. Golden Shield Life Insurance does not control and is not responsible for third-party content, including any sponsorships or advertising those sites carry.