“Thank you for allowing us to build an IUL designed around you: income for later, a safety net for today, and the golden shield every family deserves.”
Aaron PolkFounder & CEO, Golden Shield Life Insurance
How It Works
IUL Quotes in 2 Steps
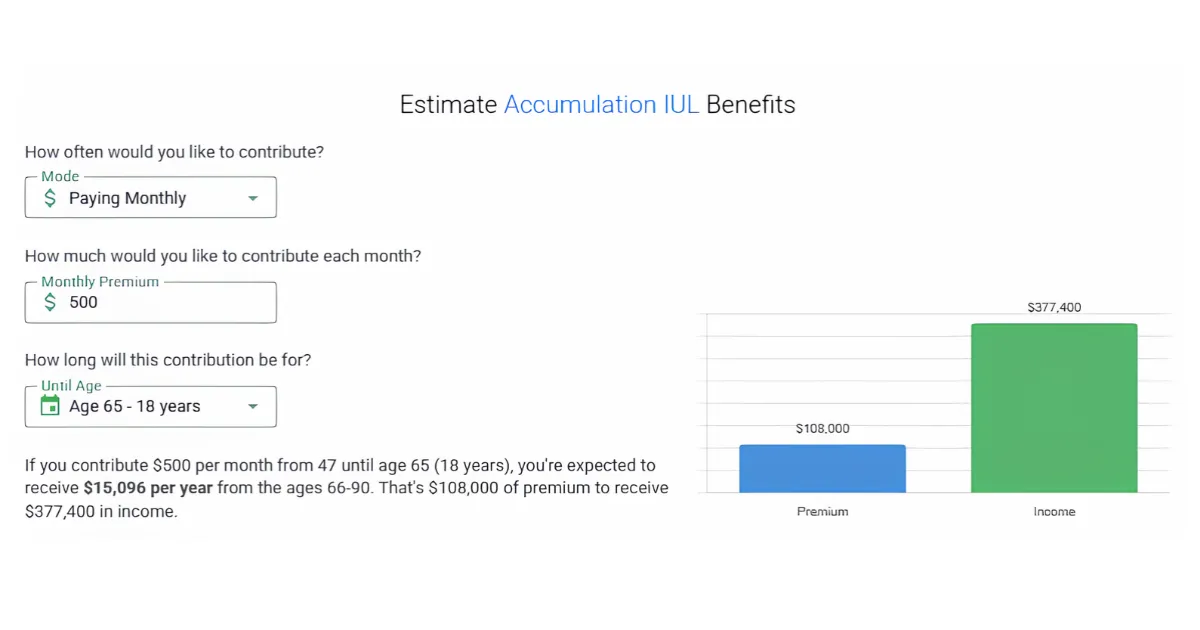
Our quoting tool compares IUL options from multiple insurance companies in minutes. Here is a sample for a 47-year-old male.
Step 1
Choose Your Goal
Pick what matters most to you, and the quotes are built around it:
- Highest Income. Designed to build the most cash value for income later.
- No Physical Exam. Options that may not require a medical exam for eligible applicants.
- Living Benefits. Coverage that can pay part of the death benefit early during a qualifying illness.
- Vitality Rewards. Policies that may reward you financially for healthy habits, with discounts and credits.
Step 2
Compare Your Results
Your results show the details that matter, side by side:
- Monthly premium for the savings you choose
- An illustration of how the policy may grow
- Estimated yearly income starting at the age you pick
- AM Best rating of each insurance company
- Exam or no exam, so you know what to expect

Sample results for a 47-year-old male. Hypothetical and for education only. Values are not guaranteed, and your quotes will depend on your age, health, how you fund the policy, and the insurance company.
Before You Compare
Four Ways People Use IUL
Indexed universal life insurance is permanent life insurance with a death benefit and cash value that can grow based on how a market index performs. The same type of policy can be built very differently depending on your goal, so it helps to know which one you are shopping for.
Lifelong Protection
A death benefit that can last for life, with some cash value growth.
- Coverage meant to last
- No-lapse guarantee options
- Living benefits riders
Paying only the minimum can leave little room for growth.
Supplemental Retirement Income
Another source of retirement income that may be tax-free.
- Funded more heavily
- Policy loans in retirement
- May help delay Social Security
Loans lower the death benefit and can cause a lapse.
Legacy for Two
One policy on two people that pays after both have passed.
- Often costs less than two policies
- Helps heirs with estate taxes and asset preservation
- Divorce or marriage dissolution: may let both parties split cash value and coverage fairly
Usually for couples focused on passing on wealth.
Business Planning
Protect the company and reward the people who keep it running.
- Key person coverage
- Buy-sell and continuation plans
- Benefits for owners and key staff
Death benefits paid to the business or surviving owners are generally income tax-free when IRS notice and consent rules are met.
A Closer Look
Four Ways to Structure an IUL
Choose a goal to see how the policy is built for it and what to know before you buy.
Coverage That Does Not Run Out
Term life insurance ends after 10, 20, or 30 years, often right when your health makes new coverage expensive or hard to get. Lifelong protection is built so your family receives a death benefit whenever you pass, as long as the policy is funded.
Built to Last
When the policy is funded as designed, the death benefit can stay in place for life instead of ending on a set date. Many people use it for final expenses, paying off a home, or leaving something behind.
A No-Lapse Guarantee
Many policies offer a guarantee that keeps the death benefit in force even if the cash value drops, as long as the required premiums are paid on time and no loans or withdrawals are taken. Some can be set to last up to your lifetime.
Help While You Are Living
Chronic and terminal illness riders can let you use part of the death benefit early. The money can be spent however you need, such as paying a family member to care for you, modifying your home, or covering travel.
Room to Grow
Paying more than the minimum can build cash value, protected by a 0% floor in down years. That cash value can be a safety net for emergencies, or it can help grow the death benefit over time.
The death benefit your beneficiaries receive is generally free of federal income tax. Using a living benefit lowers the amount your family receives later.
Another Bucket for Retirement
Many people who already save in a 401k or IRA want a second source of income that is not taxed the same way and is not dragged down by a bad market year. That is where a heavily funded IUL can fit.
Tax-Deferred Growth
Interest credited to your cash value is not taxed each year while it stays in the policy, so more of it can keep growing.
Income That May Be Tax-Free
In retirement, you can take policy loans, which are generally not taxed as long as the policy stays in force and is not a modified endowment contract. Withdrawals up to what you paid in are also generally not taxed.
Fewer Strings Attached
There are no required minimum distributions, and loans from a policy that is not a modified endowment contract do not carry the 10% early withdrawal penalty that retirement accounts can have before age 59½.
A Floor in Down Years
The 0% floor means a market drop does not reduce your cash value. That can help you avoid pulling income from accounts that just lost value.
Room to Delay Social Security
Using policy income in your 60s may let you wait longer to claim Social Security. Your monthly benefit generally grows for each year you wait, up to age 70.
Built Over Time
This strategy usually works best when the policy is funded for many years, often 10 or more, before income starts. It needs regular reviews so loans do not grow faster than the cash value.
Loans charge interest and lower the death benefit. If a policy lapses with a loan, the gain can become taxable all at once. Tax rules can change, so talk with a tax professional about your situation.
Why Families Use Legacy for Two
For couples with a larger estate, a family business, land, or property, a policy that pays after both spouses pass can protect what took a lifetime to build.
Often Costs Less
Because one policy covers two people and pays only once, the cost is based on both life expectancies. That often makes it less expensive than two separate policies, and it can be easier to qualify when one spouse has health issues.
Pays When Taxes Come Due
Under federal law, the unlimited marital deduction generally lets assets pass to a surviving spouse without estate tax. For larger estates, the tax bill and settlement costs usually arrive after the second spouse passes. That is exactly when this policy pays.
Cash Without a Forced Sale
When most of an estate is a business, farmland, or real estate, heirs may have to sell quickly, often at a discount, to cover taxes and fees. The death benefit can give them cash to settle what is owed and keep the assets in the family.
Fair Inheritances
If one child wants to run the family business or farm and another does not, the business can go to one while the life insurance goes to the other, so each receives a fair share.
Care for a Child With Special Needs
Parents of a child with a lifelong disability often use this coverage to fund a special needs trust, so support continues after both caregivers are gone.
If the Marriage Ends
Some policies include an option to split into two individual policies after a divorce, so both people can keep coverage and cash value is divided fairly.
Estate planning often involves an attorney. Many families have the policy owned by an irrevocable life insurance trust so the death benefit is not counted as part of the taxable estate. Rules vary, and this is general information, not tax or legal advice.
Protect the Business You Built
A business can be thrown off course by the death of an owner or a key person. Life insurance gives the company cash at the moment it needs it most, and the cash value can be an asset while everyone is still here.
Key Person Coverage
The business owns the policy on someone whose loss would hurt sales or operations. The death benefit can help cover lost profits, hiring and training a replacement, or paying down business debt.
Buy-Sell and Continuation Plans
Owners agree ahead of time to buy a partner’s share if that partner dies. The policy provides the cash, so the family is paid a fair price and the business stays with the people running it.
Rewarding Key People
A business can pay for a policy on an owner or valued employee as a bonus or deferred benefit. The cash value can add to that person’s retirement, which can help keep good people from leaving.
Tax Treatment
Death benefits paid to the business or surviving owners are generally income tax-free. For policies the business owns on an employee, the IRS requires written notice and consent before the policy is issued.
The right setup depends on how the business is organized. We work alongside your attorney and CPA so the policy, the agreement, and the tax treatment line up.
How the Growth Works
How IUL Cash Value Can Grow
Your money is not invested in the stock market. Instead, the insurance company credits interest based on how an index such as the S&P 500 performs over a set period, using a few rules:
- Floor. The lowest you can be credited for that period, usually 0%. When the index goes down, your cash value is not reduced by the market drop.
- Cap. The most interest you can be credited for that period, even if the index rises more.
- Participation rate. The share of the index gain used to figure your interest, mainly on uncapped options.
- Segment. The time period measured, often one year and sometimes six months.
- Fixed account. An option that pays a declared rate with a guaranteed minimum, for people who want steadier credits.
A Simple Example
| Year | Index | Credited |
|---|---|---|
| 1 | +7% | 7% |
| 2 | −10% | 0% |
| 3 | +18% | 10% |
Your Money, Your Plans
Ways People Use IUL Cash Value
Once a policy builds cash value, you can reach it through policy loans or withdrawals for almost any reason.
- Add to retirement income
- Wait longer to take Social Security
- Pay for college or training
- Renovate or modify a home
- Cover an emergency, illness, or injury
- Leave it to grow for later
Living Benefits
Help If You Become Seriously Ill
Many IUL policies can include riders that let you use part of your death benefit early if you become chronically or terminally ill. Chronic illness usually means you cannot do two of six daily activities, such as bathing or dressing, often for at least 90 days. Terminal illness usually means a life expectancy of 6 to 12 months or less, depending on the policy and your state. Some of these riders cost extra, and any amount you use lowers what your family receives later.
of Americans turning 65 will develop a disability serious enough to need long-term help, according to the U.S. Department of Health and Human Services.
Learn how these benefits work in our guide to living benefits of life insurance.
The Fine Print
What We Walk You Through Before You Apply
IUL can be a strong fit for the right person. It can also disappoint people who were never shown the fine print. Here is what we go over with every client:
- Charges. Cost of insurance and policy fees come out of your cash value every month, and they usually rise as you get older.
- Surrender charges. Canceling in the early years can cost a large share of your cash value. These charges often last 10 to 15 years.
- Loans and withdrawals. They lower the cash value and death benefit, loans charge interest, and a policy that runs out of value can lapse and create a tax bill.
- Funding limits. Putting in more than the tax rules allow turns the policy into a modified endowment contract, which taxes loans and withdrawals less favorably.
- Changing rates. Caps and participation rates are not locked for life. Your illustration shows what is possible, not what is promised.
- Guarantees. Guarantees depend on the claims-paying ability of the insurance company, which is why we compare companies rated A- or better by AM Best.
See What an IUL Could Look Like for Your Future
A licensed agent at Golden Shield Life Insurance will compare options from multiple insurance companies and walk you through a personal illustration at no cost.
Start My IUL Quote Or call or text (678) 884-4653