Life Insurance With No Medical Exam

Updated September 2026 14 min read

Life insurance with no medical exam uses a faster underwriting process that may let you skip the needles, bloodwork, and nurse visit required with a traditional exam. No medical exam describes the underwriting process, not one specific type of life insurance. Instead, insurers use health questions and electronic records to evaluate your application, with some decisions made in minutes. Coverage may include term life, whole life, indexed universal life, and burial insurance, also known as final expense insurance. Some policies may also offer living benefits for qualifying illnesses or events.

Applying for life insurance with no medical exam online

Life insurance without a medical exam has become a faster, more convenient way to buy coverage, from small permanent policies to substantial amounts of life insurance. For larger needs, term life insurance can provide up to $4 million in coverage, while whole life insurance and final expense insurance provide permanent coverage, with final expense policies commonly ranging from $2,000 to $50,000.

If you were sitting across from me, I’d first explain how no-exam underwriting compares with the traditional process. You’ll still answer health questions, and some applicants are approved within minutes. Others need a short phone interview, electronic record review, or a free nurse visit before a final decision. The online application itself is quick and noninvasive.

About 100 million Americans say they need life insurance or need more of it.

No-exam underwriting helps remove one of the biggest obstacles: getting the application completed and a decision made faster.

Life Insurance with No Medical Exam
Buyer's Guide

Life insurance with no medical exam is an underwriting process, not a type of policy. It uses health questions and electronic information to match your health profile with a carrier's underwriting decision and available coverage options.

  • Accelerated underwriting: typically term life, up to $4 million for qualified applicants.
  • Simplified issue: term or whole life with a shorter health questionnaire.
  • Guaranteed issue: whole life or final expense with no health questions, commonly up to $25,000 to $50,000.

Life insurance is inherently confusing and can quickly become overwhelming. Let's face it, you don't get to test drive it. That's why it helps to have a broker who compares the options and explains the fine print before you buy.

2025 Best of Georgia award badge, Golden Shield Life Insurance

Named Best Life Insurance Agency in Georgia 2025 by the Georgia Business Journal and a 2025 Best of Georgia Regional Winner for Insurance Agencies.

Key Takeaways

Get the right amount of coverage from the right carrier without applying everywhere.

Replace income for your family, pay off a mortgage or debts, fund your family's future needs, or use permanent coverage for final expenses.

Your age, health history, medications, nicotine use, and coverage amount can produce different results from one insurance company to another, so we match you with carriers that fit your benefits and budget.

We explain riders, conversion options, exclusions, and waiting periods, so you can compare price, living benefits, and when full coverage begins, not just approval speed.

Shop multiple carriers quickly with personal help. Golden Shield Life Insurance helps with the search and application from start to finish, without a separate fee for our help.

What Is No Medical Exam Life Insurance?

No medical exam life insurance is an underwriting process that uses modern technology and does not automatically require a physical exam, blood work, urine testing, or a nurse visit. Instead, insurers may use health questions, prescription history, medical records, driving records, and other electronic information to evaluate your application.

How No-Exam Life Insurance Works

No medical exam life insurance starts with a short application. You answer questions about your health and lifestyle, and the insurer uses electronic information to verify your answers and decide whether it has enough information to make an offer without a physical exam.

Some applicants receive a decision in minutes. Others need additional information before the carrier makes a final decision.

How Your Application Is Reviewed

Even without a physical exam, the insurer can review:

  • Health questions: Medical history, medications, nicotine use, surgeries, and recent treatment.
  • Prescription history: Pharmacy records help confirm medications and related health history.
  • MIB information: With your authorization, participating insurers can compare information in your MIB Consumer File with your application.
  • Medical records: Records can be requested when a diagnosis or recent treatment needs clarification.
  • Driving history: DUIs and serious driving violations can affect underwriting.
  • Identity and application data: Electronic systems confirm your identity and flag information that needs a closer look.

People often look for no exam life insurance, no health exam life insurance, no health check life insurance, or life insurance without a medical exam because they want to avoid needles, get covered faster, or have concerns about their medical history. These searches generally lead to the same modern underwriting process, where insurers may review electronic medical and prescription records in minutes.

No Exam Does Not Mean an Exam Can Never Be Requested

Choosing a no-exam application does not guarantee that an exam will never be needed. If the insurer needs more information, it may request a short phone interview, medical records, or a free nurse exam before making a final decision.

If that happens, it is simply part of the underwriting process and does not automatically mean you are being declined.

How Much Does No-Exam Life Insurance Cost?

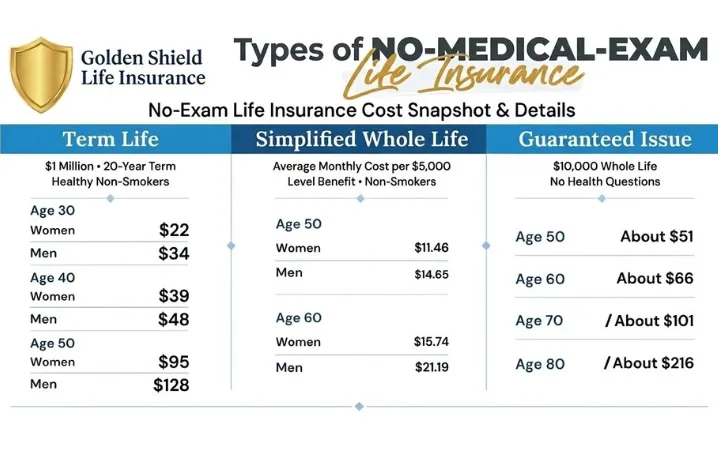
Life insurance without a medical exam can be surprisingly affordable, especially for younger, healthy non-smokers. In our September 2026 sample rates, 20-year no-exam term life insurance quotes for $1 million of coverage are about $22 a month for a healthy 30-year-old woman and $34 for a man. At age 40, sample rates are about $39 and $48, and at age 50 about $95 and $128.

Whole life insurance quotes are priced differently. Simplified-issue whole life in our samples averaged about $11 to $21 per month for every $5,000 of coverage at ages 50 and 60. Guaranteed-issue whole life requires no health questions, with our $10,000 examples ranging from about $51 per month at age 50 to $216 at age 80. Whole life provides permanent coverage and a guaranteed death benefit as long as required premiums are paid and the policy remains in force.

No-Exam Term Life Insurance

Sample monthly rates for $1 million of 20-year coverage. Healthy non-smokers.

Sample monthly rates for $1 million of 20-year no-exam term life insurance, healthy non-smokers
AgeWomenMen
30$22$34
40$39$48
50$95$128

Simplified-Issue Whole Life Insurance

Average monthly cost per $5,000 of coverage. Level benefit, non-smokers.

Average monthly cost per $5,000 of simplified-issue whole life insurance, level benefit, non-smokers
AgeWomenMen
50$11.46$14.65
60$15.74$21.19

Guaranteed-Issue Whole Life Insurance

Sample monthly cost for $10,000 of coverage. No health questions.

Sample monthly cost for $10,000 of guaranteed-issue whole life insurance
AgeAverage Monthly Cost
50About $51
60About $66
70About $101
80About $216

How to Apply for No-Exam Life Insurance?

Applying for life insurance without a medical exam takes five easy steps:

Applying for no-exam life insurance online with Golden Shield Life Insurance

5 Easy Steps

  1. Choose Your Coverage

    Pick your policy type, amount, and term.

  2. Complete Your Application

    Answer basic health and lifestyle questions.

  3. Authorize Records

    Allow the insurer to review available electronic data.

  4. Get Your Decision

    Receive an offer or request for more information.

  5. Payment & Verification

    Add beneficiaries, banking details, verify identity, and accept coverage.

Types of Life Insurance Without a Medical Exam

You can buy term or whole life insurance without a medical exam, and the policy itself works the same way. What changes is the approval. Technology speeds up underwriting, and your approval, rate, and timing depend on how your health matches each carrier's risk tolerance and rating classes.

Term Life Insurance Without a Medical Exam

No-exam term life insurance provides coverage for a set period, commonly 10, 20, or 30 years, with some companies offering longer terms. It generally provides more coverage for a lower initial premium than permanent life insurance, making it useful for income replacement, mortgage protection, debt, and other financial needs that may change over time.

Many no-exam term policies use accelerated underwriting. Instead of automatically requiring blood work, urine samples, or a nurse visit, the insurer can review your health answers along with available electronic records. Qualified applicants may be able to purchase millions of dollars in coverage without completing a medical exam.

Whole Life Insurance Without a Medical Exam

Whole life insurance provides permanent coverage with premiums that generally stay level for life and a death benefit designed to be paid whenever the insured dies, as long as the policy remains in force. Because it does not expire after a set term, it is priced differently from temporary term coverage.

Whole life is commonly used for final expenses, burial costs, family support, legacy planning, and cash value accumulation. People buying coverage primarily for funeral and family expenses often choose $10,000 to $50,000, although larger policies are available.

Depending on the product, no-exam whole life may be simplified issue or guaranteed issue.

How No-Exam Approval Works

Accelerated underwriting typically offers the largest coverage amounts. You answer health questions and authorize the insurer to review available electronic information instead of automatically completing a physical exam.

Simplified issue also skips the traditional medical exam but usually uses a shorter health questionnaire and electronic underwriting. It is commonly found with whole life insurance and some term policies.

Guaranteed issue requires no medical exam and no health questions. If you meet the product's age and eligibility requirements, health conditions generally do not prevent approval. Coverage amounts are smaller, and most guaranteed-issue policies include a graded death benefit for natural death during the first years of the policy.

Guaranteed Issue Life Insurance

Guaranteed issue life insurance is a type of whole life insurance with no medical exam or health questions. If you meet the policy’s age and eligibility requirements, health conditions generally will not prevent approval.

Coverage amounts are usually smaller and premiums are typically higher than other no-exam options, so these policies are often used for final expenses.

Many policies include a graded death benefit during the first two years. If death from natural causes occurs during that period, the beneficiary generally receives the premiums paid plus interest, which may be around 10% depending on the policy. After the graded period, the full death benefit becomes available.

Term Life Insurance With No Medical Exam

Term life insurance without a medical exam provides coverage for a set period, commonly 10, 20, or 30 years, without automatically requiring blood work or a nurse exam. Many policies use accelerated underwriting, which reviews your health questions and available electronic records to determine eligibility.

Qualified applicants may be able to purchase $1 million or more in coverage, depending on age, health, income, and the insurance company. Unlike guaranteed-issue coverage, no-exam term policies generally provide the full death benefit once the policy is issued and in force, subject to the policy terms and exclusions.

Explore our full guide to Term Life Insurance Without a Medical Exam for coverage limits, underwriting, rates, term lengths, and carrier options.

Whole Life Insurance Without an Exam

Whole life insurance provides permanent coverage with premiums that generally stay level for life and a death benefit designed to be paid whenever the insured dies, as long as the policy remains in force. Because it does not expire after a set term, it is priced differently from temporary term coverage.

Whole life is commonly used for final expenses, burial costs, family support, legacy planning, and cash value accumulation. People buying coverage primarily for funeral and family expenses often choose $10,000 to $50,000, although larger policies are available.

Depending on the product, no-exam whole life may be simplified issue or guaranteed issue.

No Exam Life Insurance for Seniors

Senior couple on a park bench reviewing no-exam life insurance options on a tablet

Many of our senior clients compare Mutual of Omaha, Americo, and Corebridge Financial because all three offer both simplified-issue and guaranteed-issue life insurance options without a traditional medical exam.

  • Simplified issue: No physical exam, but health questions are used to determine eligibility and pricing.
  • Guaranteed issue: No medical exam or health questions, with smaller coverage amounts and typically a graded death benefit for natural death during the first years.

The better option depends on your age, health, coverage amount, and whether you qualify for immediate coverage rather than a graded benefit.

No Medical Exam Life Insurance Online

Golden Shield Life Insurance can help you compare no-medical-exam coverage online from companies including Mutual of Omaha, Banner Life, Ethos, Americo, Principal, Pacific Life, and Corebridge Financial.

You can request a quote, complete an application, and review available options online. Some applicants may receive a quick decision, while others may be asked for additional information before approval.

$250,000 Life Insurance With No Medical Exam

$250,000 of term life insurance may be available without a medical exam for applicants who qualify.

Sample monthly rates for $250,000 of no-exam term life insurance by age and sex
AgeWomenMen
20$10$12
30$11$12
40$15$17
50$30$38
60$73$104

Pricing depends on age, sex, health, nicotine use, term length, and underwriting.

Best No Exam Life Insurance

The best no-medical-exam life insurance depends on your age, health, coverage amount, and whether you want term or permanent coverage.

  • Banner Life

    Up to $4 million in no-exam term coverage for eligible applicants, with term lengths up to 40 years.

    AM Best rating: A (Excellent)

  • Mutual of Omaha

    A well-known name in insurance with more than a century of experience, offering simplified-issue and guaranteed-issue whole life options for seniors and families.

    AM Best rating: A+ (Superior)

  • Nationwide

    Up to $5 million in accelerated underwriting for qualified applicants ages 18 to 50.

    AM Best rating: A+ (Superior)

  • Pacific Life

    Up to $3 million in term coverage with no medical exam for qualified applicants ages 18 to 60.

    AM Best rating: A+ (Superior)

AM Best ratings measure an insurance company’s financial strength and ability to pay claims. They are not a recommendation of a specific policy. Ratings as of September 2026.

FAQ about No Medical Exam Life Insurance

Is No Medical Exam Life Insurance Worth It?

Yes, especially if speed, convenience, or avoiding an exam matters to you. I recommend comparing it with fully underwritten coverage because some applicants can save money by completing the traditional process.

Is No Medical Exam Life Insurance More Expensive?

Sometimes, but not always. Healthy applicants using accelerated underwriting can receive very competitive rates, while simplified or guaranteed-issue policies generally cost more for the amount of coverage.

Does No Medical Exam Life Insurance Ask Health Questions?

Usually, yes. Most no-exam policies still ask health questions and may review prescriptions, medical records, driving history, and other electronic information.

Is Guaranteed Acceptance Life Insurance the Same as No Exam Life Insurance?

No. Guaranteed acceptance is one type of no-exam insurance that does not ask health questions, while many other no-exam policies still use health information to determine approval and price.

Does No Exam Life Insurance Have a Waiting Period?

Not necessarily. Many term and simplified-issue policies provide the full death benefit once coverage is in force, while guaranteed-issue policies commonly have a graded period for natural death.

Does No Exam Life Insurance Pay the Same Death Benefit?

It can. Many no-exam term and simplified-issue policies pay the full stated death benefit, while guaranteed-issue policies may limit natural-death benefits during the first years.

What Is the Difference Between No Exam and Traditional Life Insurance?

The biggest difference is the underwriting process. Traditional underwriting may require blood work and a nurse exam, while no-exam underwriting relies more heavily on health questions and electronic records.

Can You Get Life Insurance Without a Medical Exam After Age 80?

Yes, but your choices become more limited after age 80. Coverage is usually smaller and more likely to be permanent whole life or final-expense insurance rather than large term policies.

What Is the Cheapest Term Life Insurance With No Medical Exam?

There is no single company that is cheapest for everyone. In my experience, comparing several carriers matters because age, health, medications, nicotine use, coverage amount, and term length can change which company offers the lowest rate.

How Much Whole Life Insurance Can I Get Without a Medical Exam?

No-exam whole life commonly ranges from a few thousand dollars to around $50,000, depending on the product and your eligibility. Simplified-issue policies generally offer more coverage than guaranteed-issue policies.

What Our
Clients Say

Atlanta SkyView Ferris wheel Georgia State Capitol gold dome in Atlanta
★★★★★
“

Aaron's Closing Thoughts

No-medical-exam life insurance has changed a lot.

Avoiding a nurse visit no longer automatically means settling for a small policy or paying substantially more. Depending on your age, health, and the coverage you need, you may qualify for term life insurance with substantial coverage, simplified whole life, or guaranteed-issue coverage without completing a traditional medical exam.

The part I would pay the most attention to is how the policy is underwritten, not simply whether it says “no exam.” Two insurance companies can review the same person and reach different decisions based on health history, medications, nicotine use, driving history, age, and the amount of coverage requested.

That is why I would not choose a policy based only on the fastest approval or the first quote you see online. Compare the premium, coverage amount, policy length, riders, conversion options, and whether the full death benefit begins immediately.

My advice is simple: buy the coverage you understand, can comfortably afford, and can reasonably keep in force. No-exam life insurance can make the process easier, but choosing the right policy still deserves a careful comparison.

Aaron Polk

Founder & CEO, Golden Shield Life Insurance

Your shield is ready. Are you?

Thank you. Your request is in. A licensed agent at Golden Shield Life Insurance will reach out shortly to match you with your options.
Something went wrong sending your request. Please try again, or call or text us at 678-884-4653.

No Medical Exam Life Insurance Explained

A short walkthrough of how no-exam underwriting works, what insurers can still review, and how to compare term, simplified whole life, and guaranteed issue before you apply.

Watch on YouTube · No-exam approval, coverage amounts, and pricing vary by age, health, state, and insurance company.

Read the video transcript

Welcome back to the explainer. So, today we're diving straight into something that usually makes people groan: life insurance. Specifically, we're talking about getting it without the dreaded medical exam. If you've been kicking the can down the road because you literally just don't have the time or the patience for the old-school process, you're in the right spot. Let's get right into it.

Be honest for a second. When you think about life insurance, what's the first thing that pops into your head? For a lot of us, it's a stranger showing up at the house, the super uncomfortable physical, the blood draw, the little plastic cup, and then weeks of just waiting around in the dark for an underwriter to get back to you. Honestly, that physical invasion and the massive time drain are huge deterrents.

It's a massive pain point, and it keeps so many people totally unprotected. And guys, the scale of this problem is just staggering. Roughly 100 million Americans say they either need life insurance or they need more of it. Think about that. That is a massive chunk of the population just walking around without a safety net for their loved ones.

But here's the good news. The industry has actually evolved. Getting an application done and getting a decision fast is completely possible now. There's basically a modern life hack to bypass that physical exam entirely.

So here's our road map for today's explainer. One, the no-exam reality. Two, the invisible medical exam. Three, three ways to qualify. Four, breaking down the costs. And five, smart shopping and advice.

The No-Exam Reality

All right, section one, the no-exam reality: busting the biggest myth. Okay, so the absolute most crucial thing to understand right out of the gate is this. No medical exam is not a product. It describes how you're evaluated, not what you're actually buying. You are not getting some lesser, watered-down policy just because you skip the doctor's visit. The actual coverage is exactly the same. You can still get term, whole life, or final expense insurance.

The whole point of the insurance hasn't changed one bit. It still transfers financial risk from your pocket to the insurance company. What has totally been revolutionized is the speed and the method they use to evaluate that risk.

The Invisible Medical Exam

Which brings us straight to section two, the invisible medical exam, behind the scenes. Let's look at the old way versus the new way. Traditional underwriting relies incredibly heavily on a physical snapshot, right? A nurse visit, urine tests, getting your blood drawn. It literally takes weeks.

But no-exam underwriting is accelerated. Instead of poking and prodding you, insurers use your answers to health questions and combine them with a deep dive into your electronic records. Basically, technology has replaced the needle. And because of that, you can actually get a decision in minutes sometimes and have the coverage in force that exact same day.

Now, you might be wondering how they actually know you're healthy. Well, your electronic footprint is surprisingly transparent, and this invisible exam is rigorous. When you give them the green light to review your data, they are checking your pharmacy records, which, let's be real, tells them a whole lot about your health history and what you're currently treating. They also check the Medical Information Bureau to see your past application history. And they even pull your driving record. Things like DUIs or serious moving violations heavily impact your risk profile. So, yeah, they know a ton about you without ever actually needing to take your pulse.

But there is a catch, and we definitely want to be totally transparent about this. Choosing a no-exam application doesn't always guarantee the exam just magically disappears. If the insurance carrier spots something in that electronic footprint that needs a bit more clarification, maybe a past medical diagnosis, or if you just ask for a massive amount of coverage that goes over their no-exam limit, they can absolutely bump your application back into traditional underwriting. But hey, that's not necessarily a bad thing. If you're super healthy, actually doing the exam might score you a lower premium in the long run.

Three Ways to Qualify

Moving on to section three, three ways to qualify: pathways to approval. So, there are three distinct pathways, or tiers, for getting approved.

First up is accelerated underwriting. This one is for healthy applicants and usually applies to term life. We're talking huge amounts here, up to $4 million with some carriers, just by passing that electronic data check.

Number two is simplified issue. This is really common for whole life and some term policies. It skips the physical exam but uses a shorter, streamlined health questionnaire instead.

And finally, number three, guaranteed issue. This is exactly what it sounds like. No medical exam, zero health questions, period. As long as you meet the age requirements, you're in. The trade-off, though: the coverage amounts are much smaller, usually capped around 25 to 50 grand. Plus, there's typically a graded death benefit, meaning the full payout isn't available for natural causes during the first couple of years.

Breaking Down the Costs

All right, section four, breaking down the costs: the financial reality. Okay, let's actually look at the numbers. This is for a $1 million, 20-year term policy for healthy non-smokers. It's surprisingly affordable. Look at this. A healthy 30-year-old woman is looking at about 22 bucks a month. A 40-year-old man, $48 a month. To secure a million dollars of tax-free protection for your family without ever seeing a doctor, for roughly the cost of a couple of streaming subscriptions. That's an absolutely incredible value.

Now, flip the script and contrast those rates with guaranteed issue whole life insurance. This is for just $10,000 in coverage. Notice how ridiculously steep this pricing curve gets as you get older. At age 50, it's about $51 a month, but by age 80, it spikes to $216 a month.

Why the huge jump? Well, the insurance company is taking on your risk completely blind. They ask zero health questions, so they essentially have to charge way more per dollar of coverage to offset that unknown risk. It's an absolutely vital tool for seniors who need final expense coverage, but you really have to understand why the cost structure works the way it does.

Smart Shopping and Advice

Which brings us to our final section, section five, smart shopping and advice: navigate like a pro. The modern online application process is incredibly streamlined into five really simple steps. One, you choose your coverage amount and type. Two, you complete a basic lifestyle and health questionnaire. Three, you basically just click a button to authorize the release of your electronic records. Four, you get your decision, often in literally minutes. And five, you add your beneficiaries and payment details. That's the whole shebang. It is fast, super easy, and totally non-invasive.

But listen, this is absolutely critical. You still have to act like a smart shopper here. Do not just blindly click and accept the very first flashy quote you see online. You really need to compare carriers. Why? Because two completely different insurance companies can look at your exact same electronic profile, your meds, your driving record, past surgeries, whatever, and offer you wildly different rates.

You've got to look beyond just that monthly premium. Check out the policy length. See what living benefit riders are included. And most importantly, especially for whole life policies, find out exactly when the full death benefit actually begins.

I love this quote from Aaron Polk. He's a former national medical underwriter and the founder of Golden Shield Life Insurance, and this really hits the nail on the head. He says, "Buy the coverage you understand, can comfortably afford, and can reasonably keep in force." It's so true. It is not just about getting the fastest approval out there so you can just check a box and move on. It's really about taking a consultative approach to finding a totally sustainable policy that is actually going to protect your family in the long term.

Final Thoughts

And that wraps up our explainer for today. The technology is finally here to secure massive financial protection using nothing but your electronic footprint, all in a matter of minutes. But you know, it really begs a much larger question. As these algorithms and our data footprints get even sharper, will the traditional medical physical soon become entirely extinct across all parts of our healthcare system? It's wild to think about. Thank you so much for joining me today, and I really hope this empowered you with the knowledge you need to get covered. See you next time.
Disclaimer

Last reviewed: September 2026. This page is reviewed and updated as carrier programs, rates, and state requirements change.

Facts on This Page Are Supported By

  • National Association of Insurance Commissioners. "Accelerated Underwriting." How life insurers use external data and analytics to issue policies without a medical exam. Accessed September 26, 2026. content.naic.org/insurance-topics/accelerated-underwriting
  • National Association of Insurance Commissioners, Accelerated Underwriting (A) Working Group. Regulatory guidance for state insurance departments reviewing accelerated underwriting programs. Adopted by the Life Insurance and Annuities (A) Committee, August 14, 2024. View the guidance, PDF
  • National Association of Insurance Commissioners. "Life Insurance Buyer's Guide." Types of policies and questions to ask before you buy. View the buyer's guide, PDF
  • MIB, Inc. "Request Your MIB Consumer File." Explains when a consumer file exists and how to request or dispute it. Accessed September 26, 2026. mib.com/request_your_record.html
  • Consumer Financial Protection Bureau. Consumer reporting companies list: MIB, Inc. and Milliman IntelliScript. Describes what each company collects for life insurance underwriting and how to request your report. Accessed September 26, 2026. MIB, Inc. listing · Milliman IntelliScript listing
  • Milliman IntelliScript. "For Consumers: Insurance." How prescription records are gathered with your authorization and delivered to the insurance company. Accessed September 26, 2026. rxhistories.com/for-consumers/insurance
  • U.S. Department of Veterans Affairs. "Veterans Affairs Life Insurance (VALife)." A federal example of guaranteed acceptance whole life with a 2-year waiting period that returns premiums plus interest. Accessed September 26, 2026. va.gov/life-insurance/options-eligibility/valife
  • Nationwide Financial. "Nationwide Life Underwriting Guide," Intelligent Underwriting program eligibility by age and face amount. Accessed September 26, 2026. View the underwriting guide, PDF
  • Banner Life Insurance Company (Legal & General America). "Underwriting Experience," accelerated underwriting eligibility and limits. Accessed September 26, 2026. bannerlife.com/advisor/our-approach/underwriting-experience
  • AM Best. Rating action on Banner Life Insurance Company, financial strength rating A (Excellent), March 13, 2026. news.ambest.com
  • AM Best. Ratings affirmed for Mutual of Omaha Insurance Company and subsidiaries, including United of Omaha Life Insurance Company, financial strength rating A+ (Superior), April 2, 2026. news.ambest.com
  • AM Best. Ratings affirmed for Nationwide Life Insurance Company and affiliates, financial strength rating A+ (Superior), November 2025. news.ambest.com
  • Pacific Life Insurance Company. "PL Promise Term," accelerated underwriting up to $3 million with no medical exam, ages 18 to 60. Accessed September 26, 2026. plpromise.pacificlife.com · View the Pacific Life term consumer guide, PDF
  • Pacific Life Insurance Company. "Financials and Insurance Ratings," AM Best financial strength rating A+ (Superior), report dated January 16, 2026. pacificlife.com

Rate Sources and Supporting Documents

The sample rates shown on this page are based on current carrier quote examples and published carrier rate materials reviewed by Golden Shield Life Insurance. Rates are provided for educational purposes only and are not guaranteed. Actual premiums and eligibility are determined by the issuing insurance company.

Disclaimers

  • This page is educational and is not financial, legal, tax, or medical advice.
  • "No medical exam" describes an underwriting path, not a type of policy. An insurance company may still request a phone interview, medical records, a paramedical exam, or lab work before making a final decision.
  • Eligibility for accelerated underwriting depends on age, coverage amount, health history, and each insurance company's guidelines. Applicants who do not qualify may be moved to traditional underwriting, offered a different rate class, or declined.
  • With your authorization, insurance companies may review prescription history, MIB information, motor vehicle records, medical records, and other consumer reports. You may request a free copy of these reports and dispute information you believe is inaccurate.
  • Answer every health question completely and accurately. Incorrect or incomplete answers can lead an insurance company to change or rescind a policy or deny a claim during the contestable period.
  • "Guaranteed issue" and "guaranteed acceptance" mean eligible applicants within the product's age limits are accepted without health questions. Most guaranteed-issue policies include a graded death benefit that pays premiums plus a stated amount, rather than the full face amount, for a non-accidental death during the first policy years. Terms vary by insurance company and state.
  • Whole life guarantees apply only while required premiums are paid and the policy remains in force. Policy loans and withdrawals reduce cash value and can reduce the death benefit.
  • Term conversion options, riders, and their deadlines vary by policy and insurance company. Some riders must be selected when you apply and may increase the premium.
  • Sample rates on this page are illustrations, not quotes. Your premium depends on age, sex, health, nicotine use, state, coverage amount, term length, and underwriting.
  • Insurance company names and coverage limits mentioned on this page reflect program materials reviewed at the time of writing and may change without notice. Not every insurance company, product, or coverage amount is available in every state.
  • Golden Shield Life Insurance is an independent insurance agency and does not underwrite policies. Carrier availability depends on licensing, appointments, state of residence, and applicant eligibility.
  • Golden Shield Life Insurance does not guarantee approval, pricing, or benefit eligibility. The issuing insurance company makes all underwriting and claim decisions.